
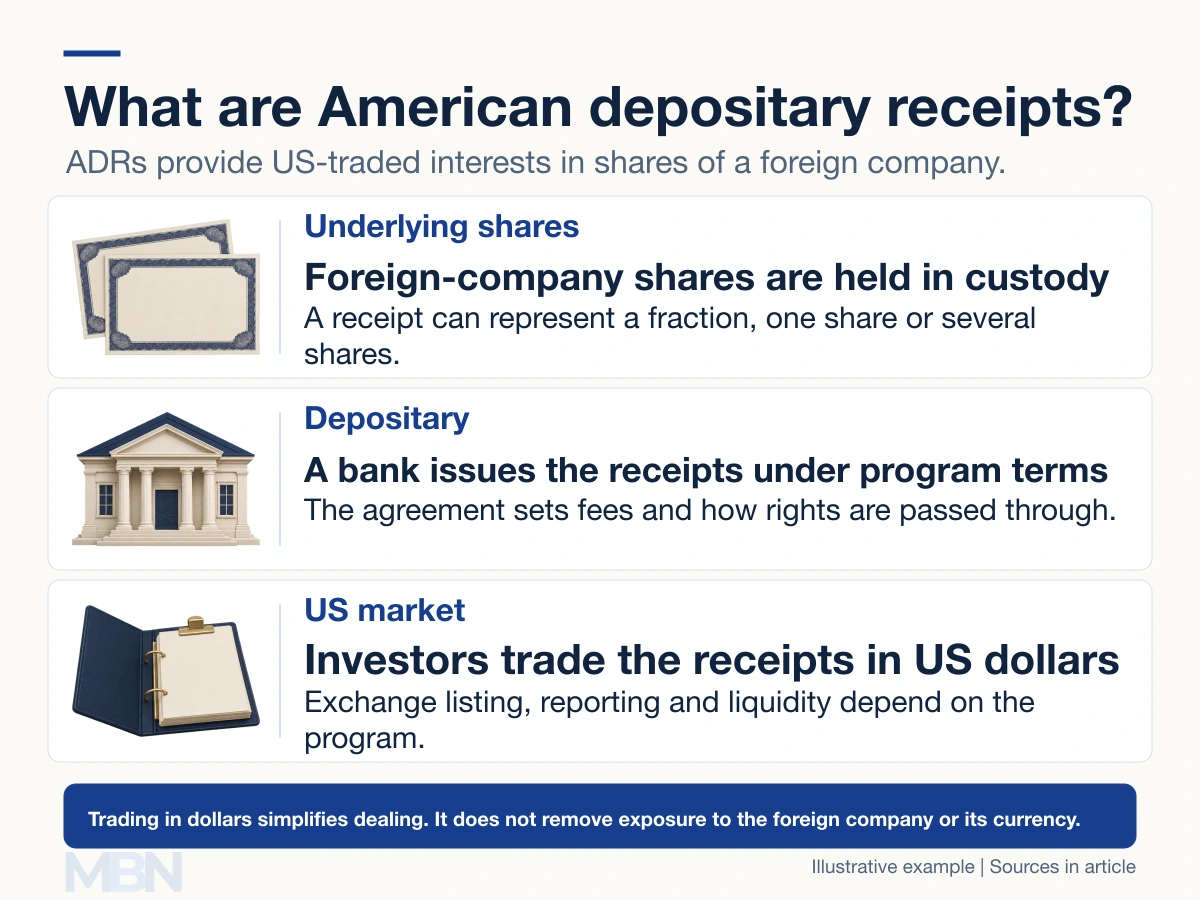
American depositary receipts, or ADRs, are US-traded securities representing interests in shares of foreign companies. A depositary bank issues the receipts against underlying shares held in custody, commonly in the company’s home market.
The US Securities and Exchange Commission (SEC) explains how receipts are created and canceled. A receipt can represent one ordinary share, several shares or a fraction. ADRs are not simply the name for every foreign share that trades in the United States.
What is the difference between ADR and ADS?
An American depositary share, or ADS, is the underlying unit of interest represented by the receipt. ADR is the certificate evidencing that interest, rather than the name for the entire issue. Market participants commonly use ADR and ADS interchangeably.
The deposit agreement determines how dividends, voting instructions, fees and withdrawal rights work. Exchanging receipts for ordinary shares can involve costs and restrictions; it should not be assumed to be an instant, free transaction.
Sponsored and unsponsored programs
A sponsored program involves an agreement between the foreign company and a depositary. An unsponsored program is established by a depositary without that contractual involvement from the company. Sponsorship does not simply mean the bank subsidizes investor costs.
Deutsche Bank’s program guide distinguishes three sponsored levels:
- Level I: over-the-counter trading using existing shares, with Form F-6 registration for the receipts and an exemption from full issuer reporting where the conditions are met.
- Level II: exchange listing using existing shares, with fuller registration and issuer reporting requirements.
- Level III: a registered capital-raising offering and exchange listing, with additional offering disclosure.
Level I does not mean no SEC registration of the receipts. Likewise, the levels are not categories of partial or full compliance with US generally accepted accounting principles (GAAP).
The SEC permits eligible foreign private issuers to use International Financial Reporting Standards (IFRS), as issued by the International Accounting Standards Board (IASB), without US GAAP reconciliation. Reporting obligations and accounting eligibility must be assessed separately.
How does the share ratio affect price?
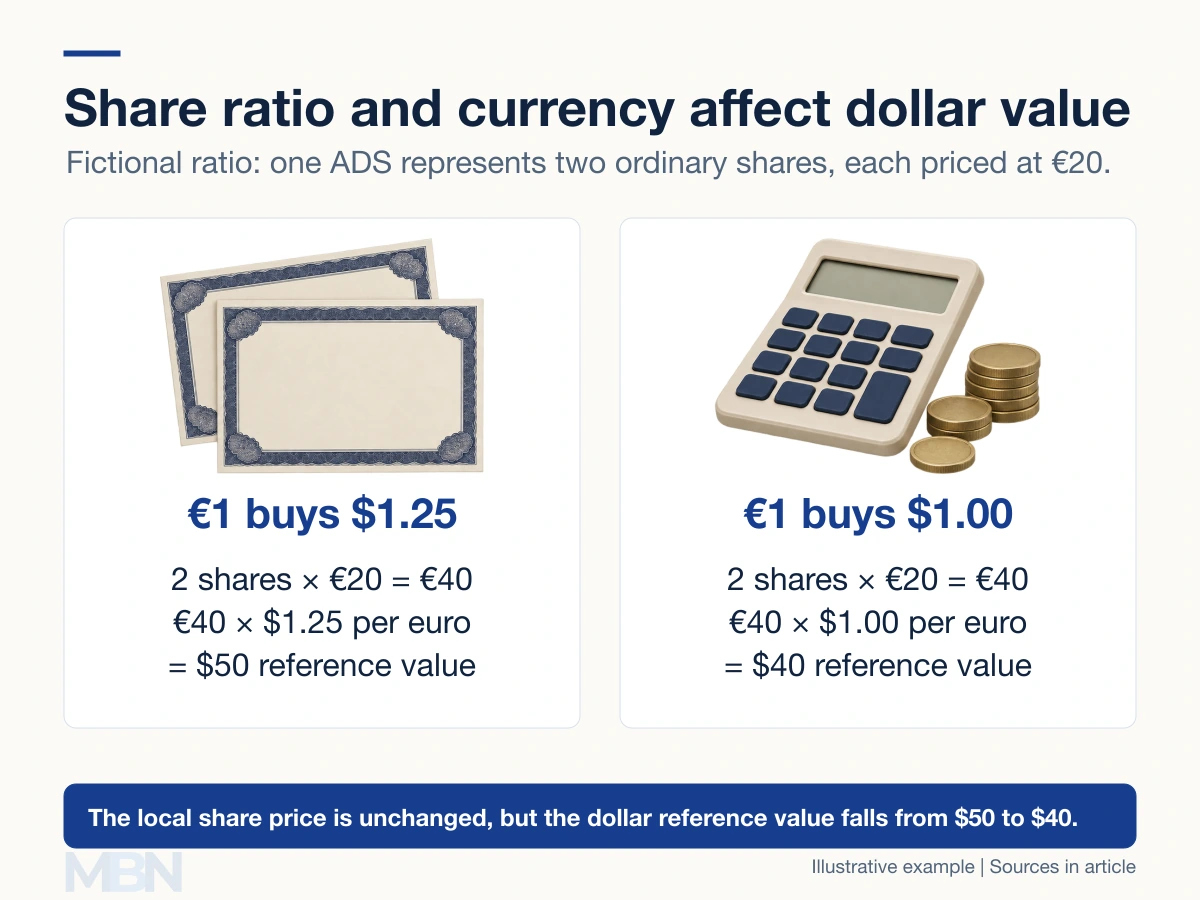
The SEC’s ADR glossary links pricing to the home-market share price and receipt ratio. Currency conversion also matters.
Assume one ADS represents two ordinary shares, each worth €20. At $1.25 per euro, their combined reference value is $50. At $1 per euro it is $40, even though the local share price is unchanged. Actual trading prices can differ because of market timing, liquidity and costs.
Fees and risks still matter
Depositary service fees can be deducted from dividends or collected separately. Currency-conversion charges, foreign withholding taxes and brokerage costs may also affect the amount received. ADRs are not automatically free of custody-related charges or always cheaper than direct ownership.
The SEC’s international-investing guide describes currency, information, liquidity and legal risks. Dollar quotation does not turn a foreign-company investment into a US domestic business exposure. US trading also does not guarantee identical disclosure, shareholder rights or legal remedies across programs.
Last checked and updated on November 4, 2026 by the MBN editorial team.