
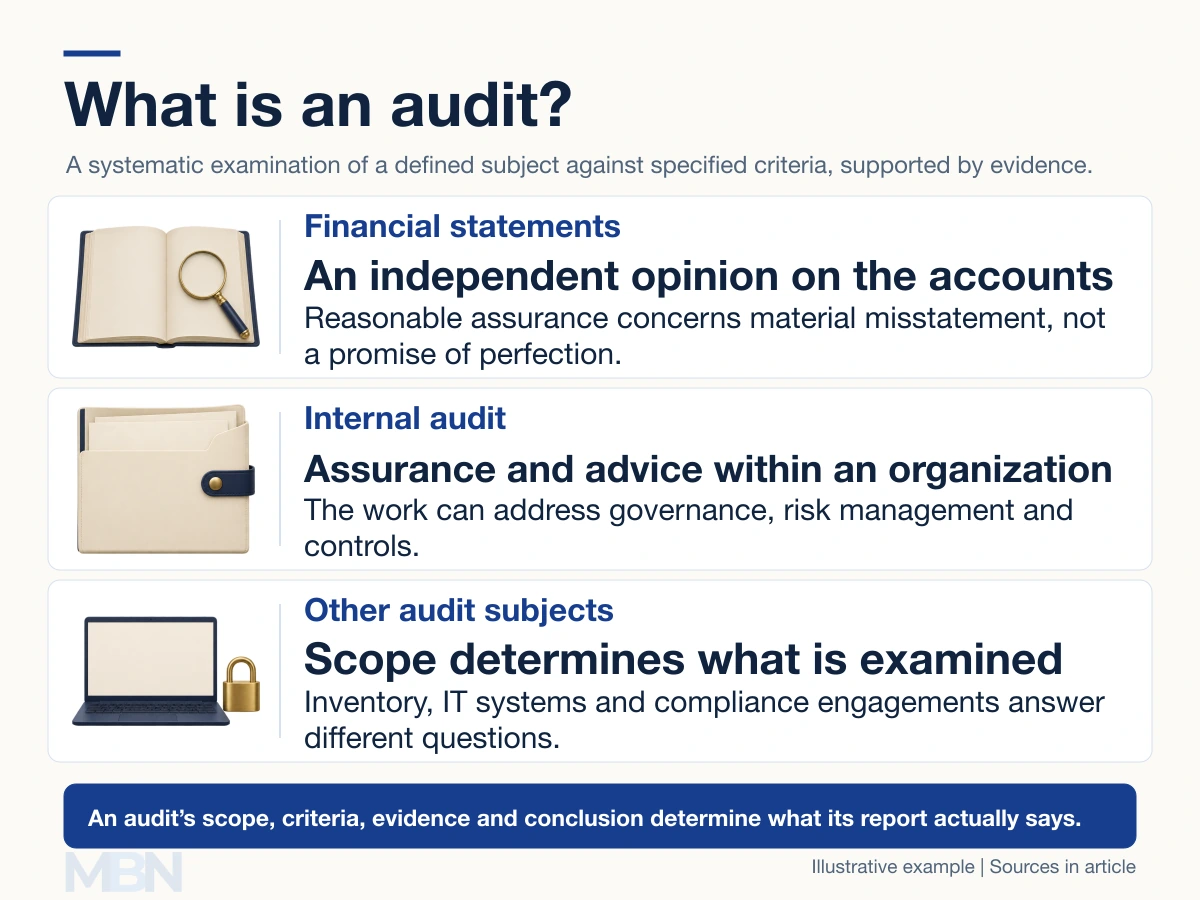
An audit is a systematic examination of a defined subject against specified criteria. In a financial-statement audit, an independent auditor gathers evidence to form an opinion on whether the accounts are presented fairly under the relevant reporting framework.
Audit work also covers areas such as internal controls, compliance, inventory and information technology. The subject and agreed scope determine what is examined and what the resulting report means.
Reasonable assurance is not a guarantee
The US Public Company Accounting Oversight Board’s AS 1000 describes reasonable assurance as a high, rather than absolute, level of assurance. A financial-statement audit addresses material misstatement, whether caused by error or fraud.
Material means significant enough to matter to users’ decisions in the circumstances. An audit does not promise to find every minor mistake, detect every fraud or certify that a company will remain profitable.
Management remains responsible for preparing the financial statements. The auditor’s role is to examine evidence and report an opinion, rather than take over management’s responsibilities.
What are auditors?
Auditors are people who carry out audit engagements. External financial-statement auditors must meet the independence and professional requirements applicable to their work. They may work for an accounting firm, while internal auditors can be employees or external service providers.
The Institute of Internal Auditors’ standards describe independent, objective, risk-based assurance and advice for boards and management. Internal audit can address governance, risk management and controls. It is not simply another name for the external audit of annual accounts.
Tax-authority examinations and operational audits have their own purposes and powers. A home energy assessment is another use of the word audit; it does not provide an opinion on company accounts.
How evidence changes the conclusion
PCAOB AS 1105 describes evidence-gathering procedures including inspection, observation, confirmation and recalculation. Depending on the risks, auditors can test selected items, examine particular transactions or use other procedures. They do not necessarily check every transaction.
Suppose a fictional warehouse ledger records 20 units at a particular date, while a physical count finds 18 at that location. The difference is two units. The auditor investigates documents, movements and timing rather than immediately concluding that someone stole two items.
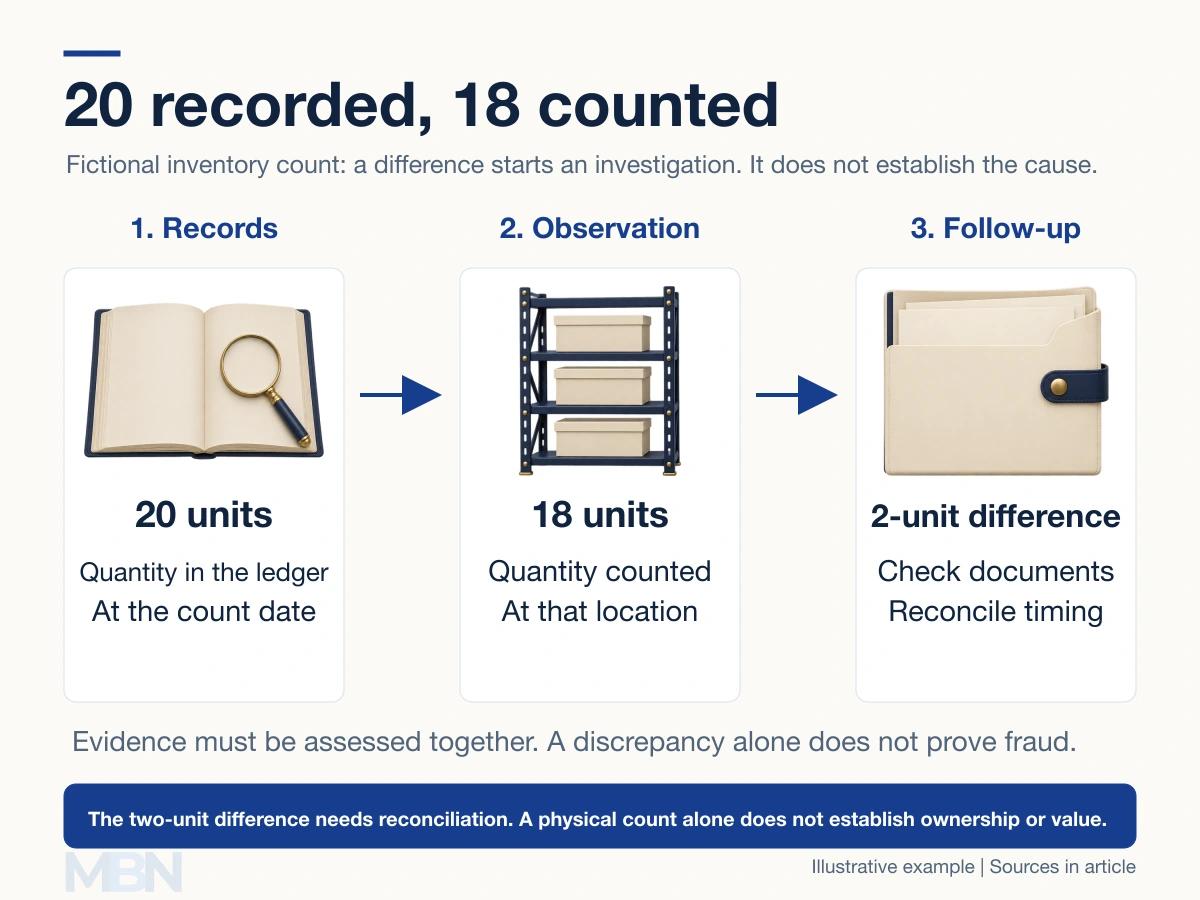
A count can support evidence about existence. It does not, alone, prove ownership or the correct valuation. Those questions need other evidence.
An audit report can express different outcomes
An unqualified, often called clean, opinion is not a guarantee of investment quality. Other reporting outcomes can include qualified or adverse opinions, or a disclaimer of opinion. A disclaimer means the auditor does not express an opinion; it is not a passing grade.
Who must obtain an audit?
Requirements depend on jurisdiction, legal form and applicable exemptions. A US Form 10-K includes audited annual financial statements. That does not mean every public company worldwide follows an identical rule or is stock-exchange listed.
In the UK, eligible private companies may qualify for audit exemption, subject to conditions and exclusions. Companies House is the company register, rather than a stock exchange. Filing accounts there and having them audited are separate requirements.
Last checked and updated on November 4, 2026 by the MBN editorial team.