
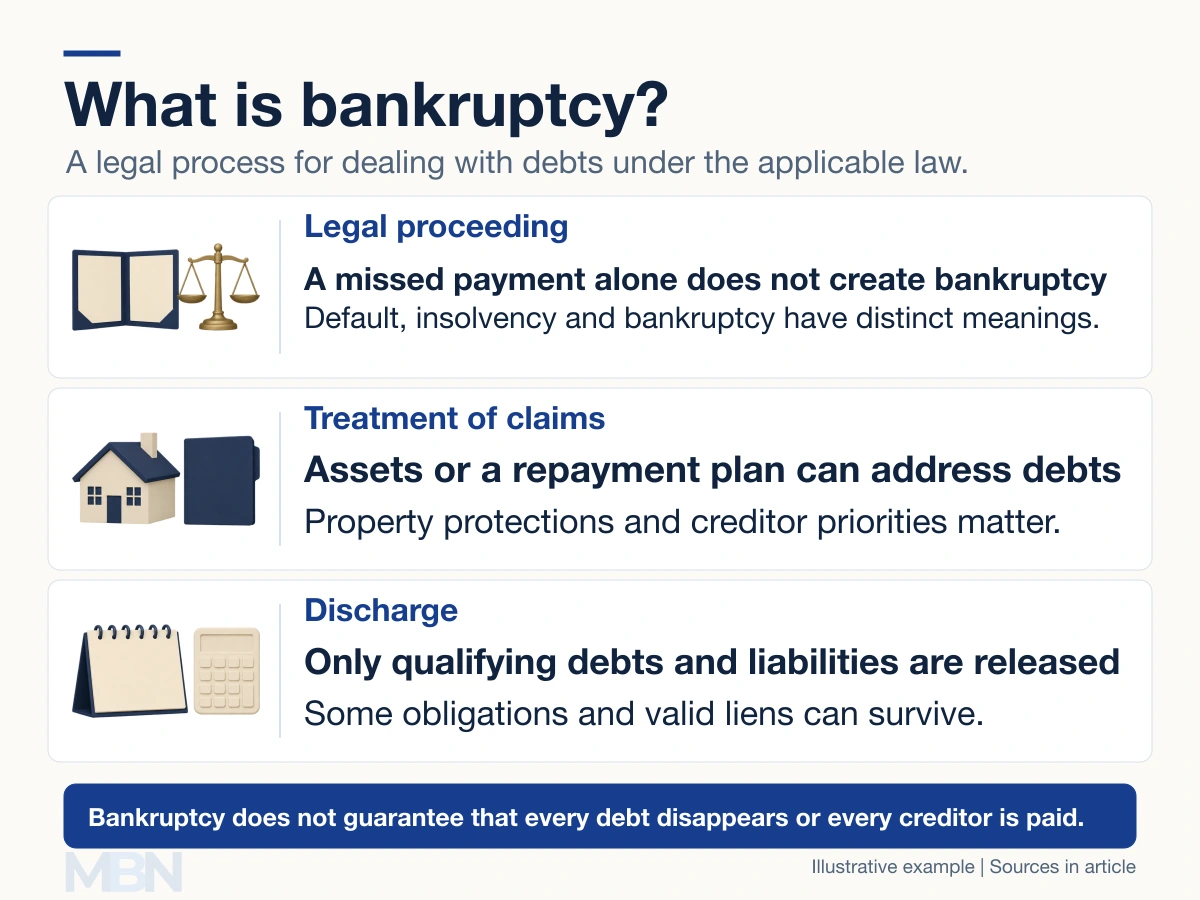
Bankruptcy is a legal process for addressing debts under a country’s insolvency law. In the United States, federal bankruptcy law can provide liquidation, reorganization or repayment procedures for eligible individuals and entities. Filing a case does not automatically erase every debt.
A debtor owes an obligation; a creditor has a claim against the debtor. Default means failing to meet an obligation. Insolvency concerns financial condition under the relevant legal test. Neither term, by itself, means a bankruptcy case has begun.
How does a US bankruptcy case begin?
The US Courts’ guide explains the federal bankruptcy process. A debtor usually starts a voluntary case by filing a petition. Creditors can initiate an involuntary case only when the legal conditions are met.
A filing generally creates an automatic stay that pauses many collection actions. Exceptions, limits and court-ordered relief can apply. The stay is distinct from a discharge, which addresses personal liability for qualifying debts.
Are all assets sold?
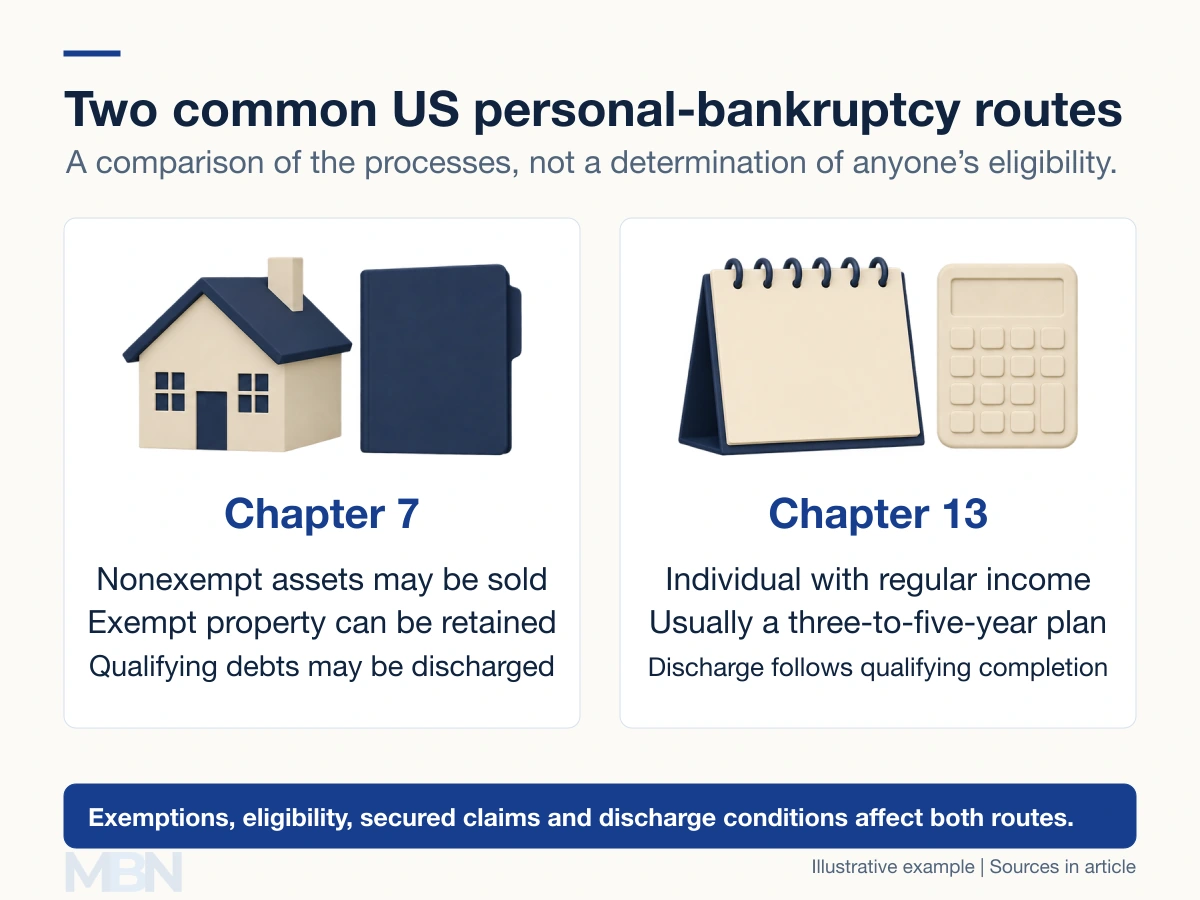
No. Under Chapter 7, a trustee can sell nonexempt property and distribute proceeds under the Bankruptcy Code. Exemptions can protect specified property. Some cases have no assets available for ordinary unsecured creditors, so recovery is not guaranteed.
By contrast, Chapter 13 lets eligible individuals with regular income propose a repayment plan, generally lasting three to five years. Keeping property still depends on meeting the relevant requirements, including how secured claims are treated.
What does a discharge remove?
A discharge releases personal liability for specified debts and bars collection of those discharged obligations. It can be denied or revoked in defined circumstances. Domestic-support obligations and certain taxes are among the debts that can survive.
Most student-loan obligations covered by the statutory exception also survive unless the applicable discharge conditions are established. A valid property lien that has not been avoided can remain even where personal liability is discharged.
For example, release from personal repayment liability is different from removing a lender’s valid security over a house. Bankruptcy does not automatically transfer the house to the debtor free of that claim.
What do the other US chapters cover?
The Justice Department outlines the principal chapters. Chapter 11 commonly addresses business reorganization and is also available to individuals. It does not guarantee continued operation or a successful restructuring.
Chapter 12 addresses eligible family farmers and fishermen. Chapter 9 deals with eligible municipalities. Chapter 15 concerns cross-border cooperation and recognition of foreign proceedings, rather than automatically clearing foreign debts.
A Chapter 7 discharge is available to individuals, not corporations or partnerships. The result therefore depends on both the chapter and the type of debtor.
Does bankruptcy mean the same thing everywhere?
No. The Insolvency Service’s guide for England and Wales describes bankruptcy as an individual procedure; companies use other processes. Personal applications can be made online, so describing every country’s process as starting with a court order would be inaccurate.
Rules differ across jurisdictions, including within the UK. Eligibility, protected property, continuing obligations and the procedure for ending a case must be understood within the applicable system.
Last checked and updated on November 3, 2026 by the MBN editorial team.