
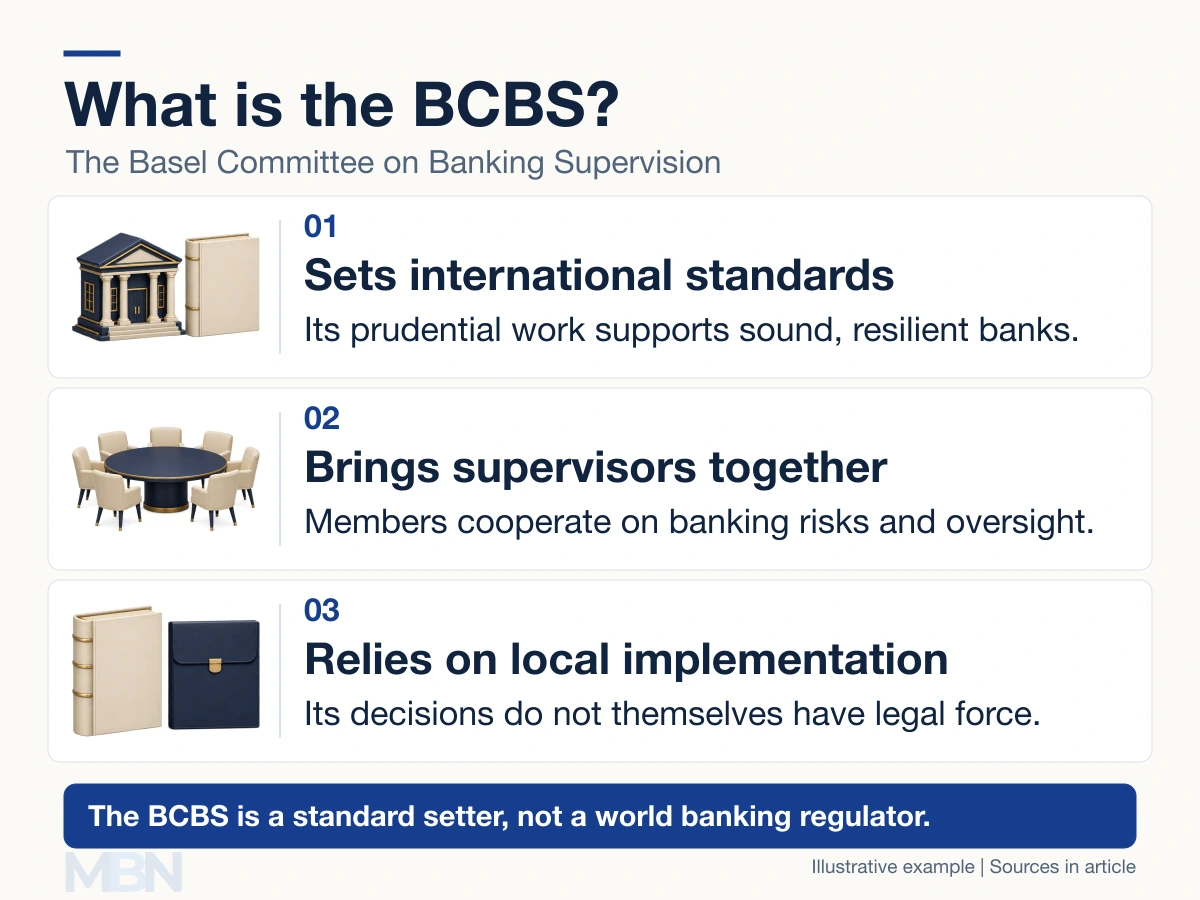
BCBS stands for Basel Committee on Banking Supervision. It is the main international standard setter for prudential banking regulation, bringing central banks and banking supervisors together to strengthen financial stability.
Prudential regulation concerns the financial soundness of banks, including their ability to absorb losses and meet obligations. The Committee develops standards and supervisory guidance, exchanges information about risks and monitors implementation.
Does the BCBS make binding law?
No. The Committee’s Charter states that it has no formal supranational authority and that its decisions do not have legal force. Its influence depends on member commitments and implementation through the relevant jurisdictions’ legal and supervisory systems.
For example, agreeing an international capital standard does not automatically change a bank’s domestic legal requirements that day. A jurisdiction must put applicable rules into effect, and its supervisors oversee compliance. Implementation dates and details can differ.
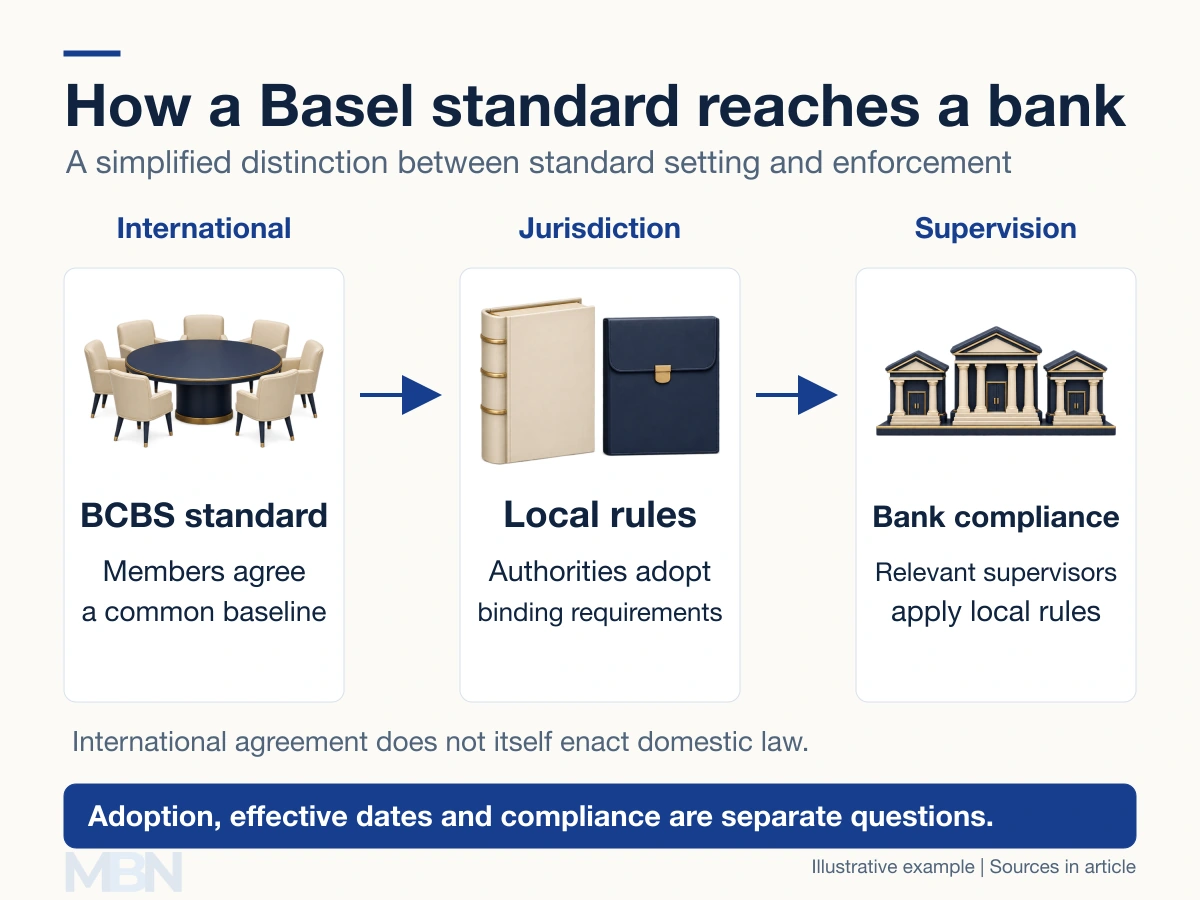
This distinction explains why the BCBS should not be called the world’s highest banking authority. It does not replace national or regional regulators, issue every bank’s license or directly enforce all banking law.
What the Basel standards cover
The consolidated Basel Framework includes capital, leverage, liquidity, large exposures, supervisory review and disclosure. It also contains the Core Principles for effective banking supervision. The standards are more extensive than a single required capital percentage.
Capital provides loss-absorbing financial resources. Liquidity concerns meeting payments as they fall due. A bank can face a liquidity problem even when its measured capital ratio looks adequate, so the two concepts should not be treated as synonyms.
For a simplified arithmetic example, $10 million of qualifying capital divided by $100 million of risk-weighted assets gives a 10% ratio. Risk-weighted assets reflect regulatory risk measurements, rather than simply the bank’s total assets. The example does not establish a required minimum or prove compliance with all rules.
Why implementation needs its own date
Basel III strengthened the framework following the global financial crisis. Its reforms have been introduced through multiple stages, with further changes finalized in 2017 and market-risk standards in 2019.
The Committee’s October 5, 2026 update reported further implementation progress and said almost all member jurisdictions had announced application by April 2027 or earlier. An announcement about future application is different from rules already being applied by banks.
Who runs the Committee?
The BCBS originated in 1974 under central-bank cooperation arrangements. Its governance structure includes oversight by the Group of Central Bank Governors and Heads of Supervision, known as GHOS. The Bank for International Settlements, or BIS, provides its Secretariat.
As of November 6, 2026, the chair is Erik Thedéen. Ben Gully became Secretary General on August 14, 2026. Earlier references to Stefan Ingves and Wayne Byres as the current officeholders are outdated.
Common standards can reduce weaknesses and inconsistencies across borders. They do not guarantee that no bank will fail or that credit will remain available in every crisis. Resilience also depends on implementation, supervision and how individual banks manage their risks.
Last checked and updated on November 6, 2026 by the MBN editorial team.