
A central bank is a public institution responsible for monetary policy and core parts of a country’s monetary system, or those of a currency union. Its mandate, powers and accountability are established by law.
The European Central Bank (ECB) distinguishes central banks from commercial banks. Central banks generally serve banks and public institutions rather than offering ordinary household checking accounts or business loans.
What a central bank does
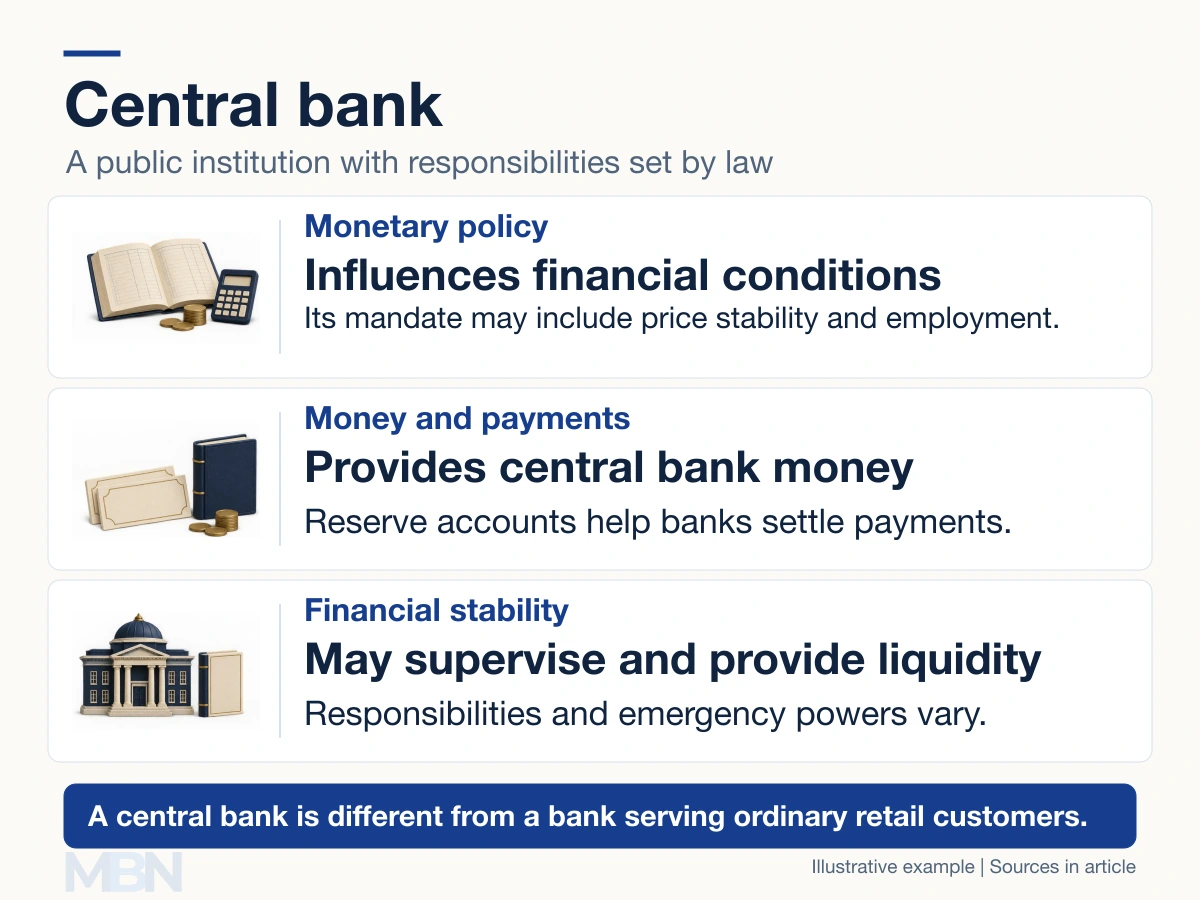
Monetary policy influences financial conditions to pursue the objectives in the bank’s mandate. In the United States, Congress assigns the Federal Reserve goals commonly described as maximum employment and stable prices, its dual mandate.
Central banks typically issue banknotes and provide reserve accounts, balances that banks hold at the central bank to complete payments between them. They also support payment systems. Some also supervise banks or have broader financial-stability responsibilities. The division of duties varies between countries.
Examples include the Federal Reserve, Bank of England, Bank of Japan and Reserve Bank of India. The ECB works with euro area national central banks in the Eurosystem. Bulgaria adopted the euro on January 1, 2026, bringing the euro area to 21 EU member countries.
How monetary policy works
The Federal Reserve explains that policy influences short-term interest rates and wider financial conditions, affecting borrowing, spending, employment and prices. The effects take time and depend on how households, businesses and markets respond.
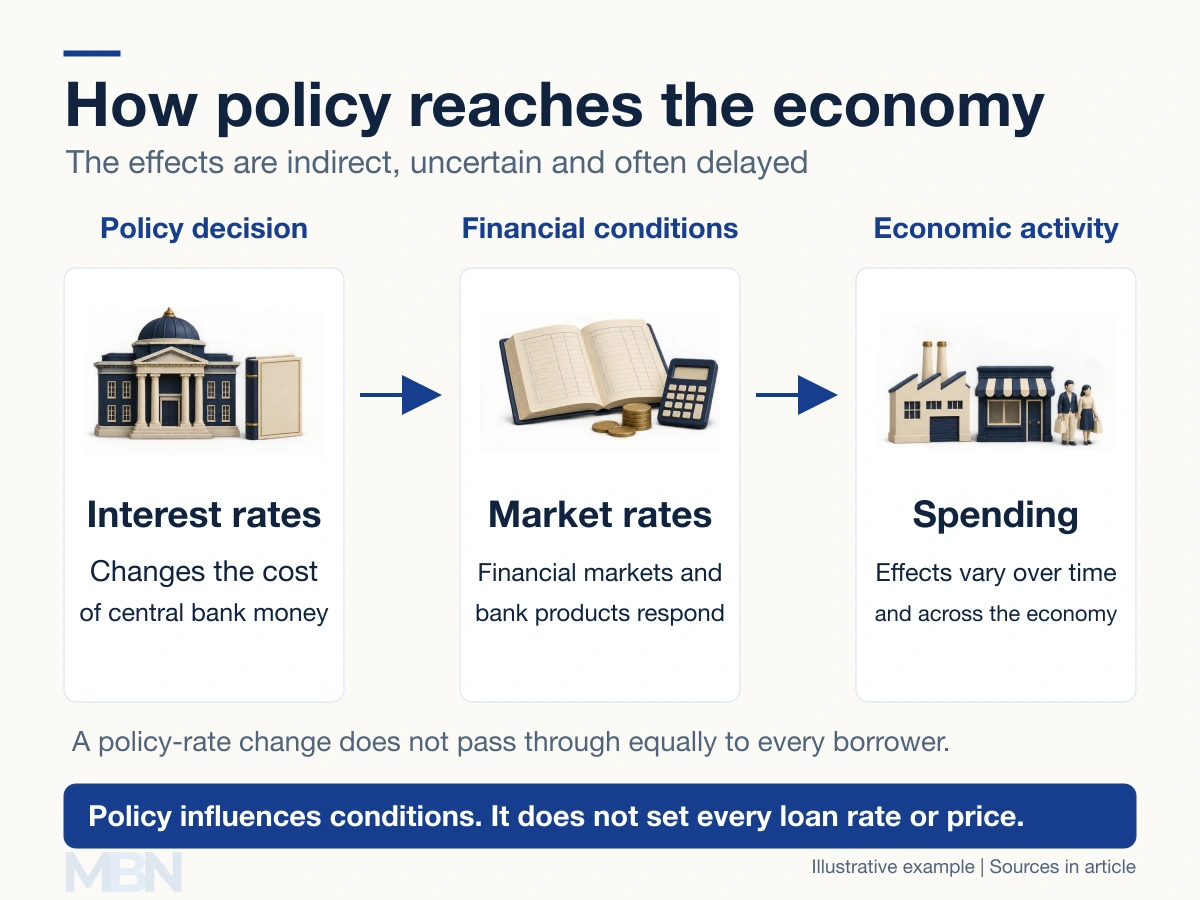
Tools can include policy interest rates, interest paid on reserve balances, lending facilities and purchases or sales of securities. Asset purchases change central bank balance sheets and can influence yields; they do not guarantee a fixed increase in commercial bank lending.
Reserve requirements are not a universal active policy tool. The Federal Reserve reduced its reserve requirement ratios to zero effective March 26, 2020. Banks still face capital, liquidity, risk and funding constraints.
Nor does a fixed reserve multiplier mechanically control deposit money. The Bank of England’s money-creation explanation describes how bank lending creates deposits within those constraints.
What lender of last resort means
Emergency central bank lending can provide liquidity when normal funding is disrupted. Eligibility, collateral (assets pledged as security) and legal safeguards matter. This is different from promising to rescue every failing institution or cover every economic shortage.
A liquidity problem concerns meeting payments when due; insolvency concerns the adequacy of assets and capital relative to obligations. Lending liquidity does not automatically repair underlying losses.
Independence does not mean choosing every objective
The Federal Reserve’s legal framework combines statutory objectives, operational independence, transparency and accountability. This illustrates the distinction between setting a mandate and deciding how to pursue it.
The amount of independence and the process for setting targets differ. It is inaccurate to say every central bank freely sets its own goals, or that it simply follows the government’s immediate political preferences.
A brief historical perspective
Sveriges Riksbank dates from 1668, and the Bank of England was founded in 1694. Their responsibilities developed over time. Early banking institutions were not created with identical versions of today’s monetary-policy and supervisory functions.
Last checked and updated on November 10, 2026 by the MBN editorial team.