
Commercial paper, or CP, is short-term debt issued as a promissory note, a promise to repay under specified terms. Financial and nonfinancial businesses use it to obtain market funding, often for working capital and other short-term needs.
Investors lend to the issuer by buying the note. The Federal Reserve’s CP explanation describes issuance directly or through dealers and its role as an alternative to bank borrowing. Access and cost depend on the issuer’s credit standing and market conditions.
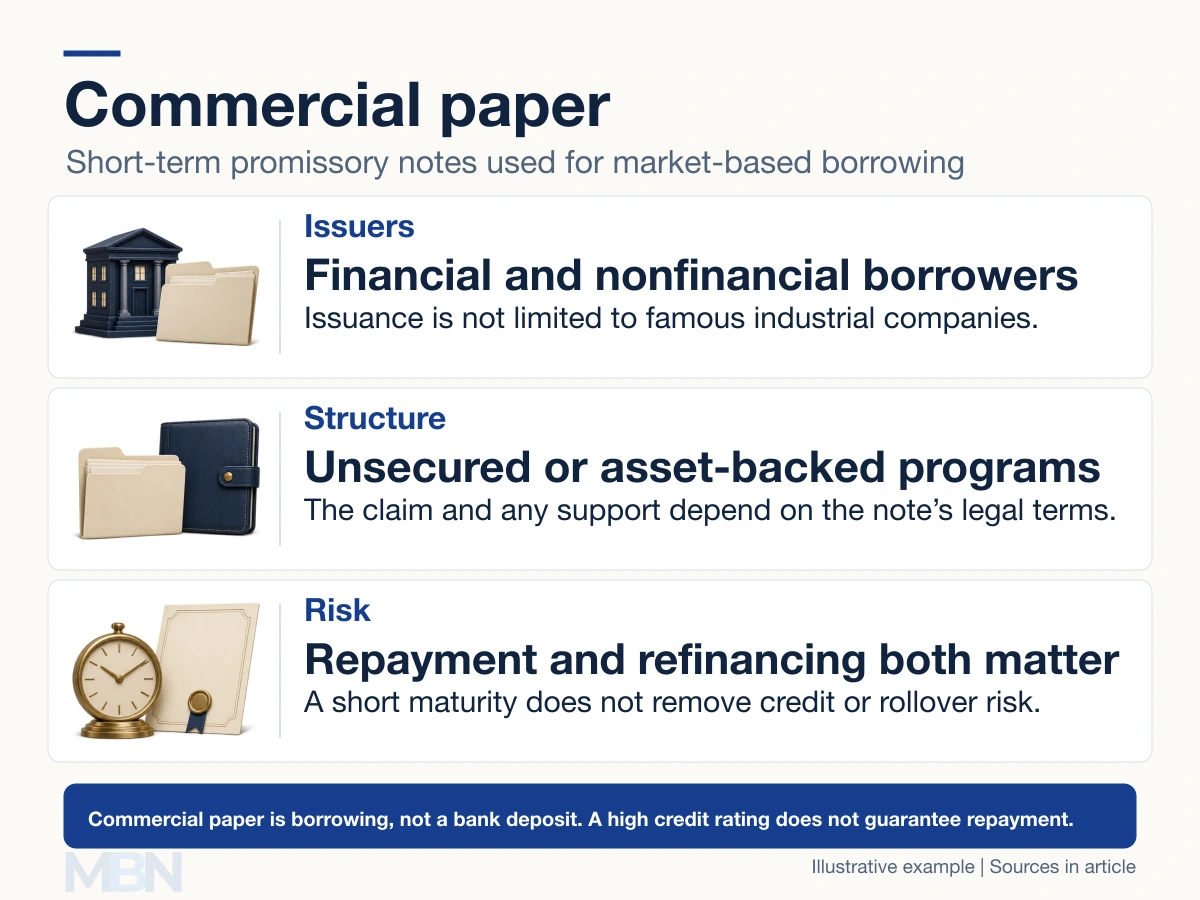
Who issues it, and what backs it?
Issuers include industrial companies, financial companies and banks. Specialized vehicles can issue asset-backed commercial paper supported by pools of receivables, loans or other assets. The Federal Reserve’s supervisory description distinguishes these structures and credit support.
Ordinary unsecured paper relies on the issuer’s ability to pay without a specified collateral pool. Asset backing, guarantees or a bank credit line can change the risk, but their terms and limits matter. Issuance is not legally restricted to a short list of “blue-chip” companies.
Why 270 days appears in US descriptions
The Federal Reserve’s US commercial-paper release covers notes with maturities of 270 days or less. The familiar number also relates to US securities-registration treatment.
SEC interpretations of Section 3(a)(3) discuss a maturity requirement of no later than nine months and the use of proceeds for current transactions. Short maturity alone does not establish that every note meets every condition of an exemption.
The 270-day figure should therefore be read in its US context, rather than as a universal worldwide ceiling. Other markets and programs have their own conventions; the ECB’s money-market statistical framework uses a different short-term maturity scope.
How discount pricing works
Commercial paper is often sold below its face value, with face value paid at maturity. Some notes instead bear interest. The method affects how quotations and returns are interpreted.
Suppose an investor pays $995,000 for a 90-day note promising $1 million at maturity. If paid in full, the difference is $5,000. Dividing that gain by the amount invested produces a holding-period return of about 0.503% before costs and taxes.
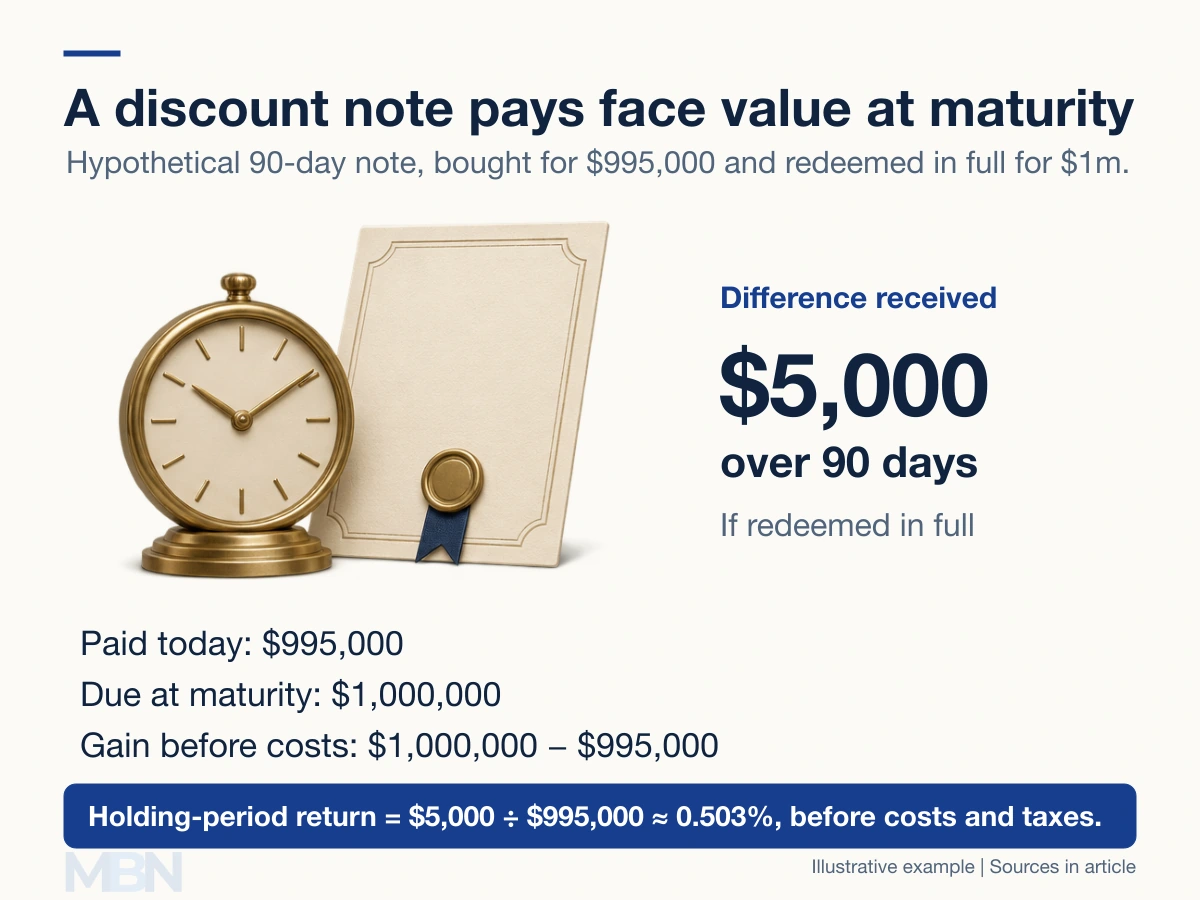
That is a 90-day return. Annualized discount rates and investment yields can use different denominators and day-count conventions, so apparently similar quotations need not be identical.
Credit, liquidity and rollover risk
Credit risk is the possibility of missed repayment. Liquidity risk is difficulty selling a note before maturity on acceptable terms. Rollover risk arises when an issuer expects to repay maturing paper by issuing new paper but cannot obtain replacement funding.
Longer maturity does not always mean a higher quoted rate. Credit quality, liquidity, the shape of market interest rates and investor demand also affect pricing.
The market experienced serious disruption during financial crises. The Fed’s Commercial Paper Funding Facility history describes its 2020 intervention. That episode does not mean CP ceased to exist after 2008. The current Federal Reserve release provides rates and amounts outstanding. Figures need an observation date and a clear statement of the market category covered.
Last checked and updated on November 11, 2026 by the MBN editorial team.