
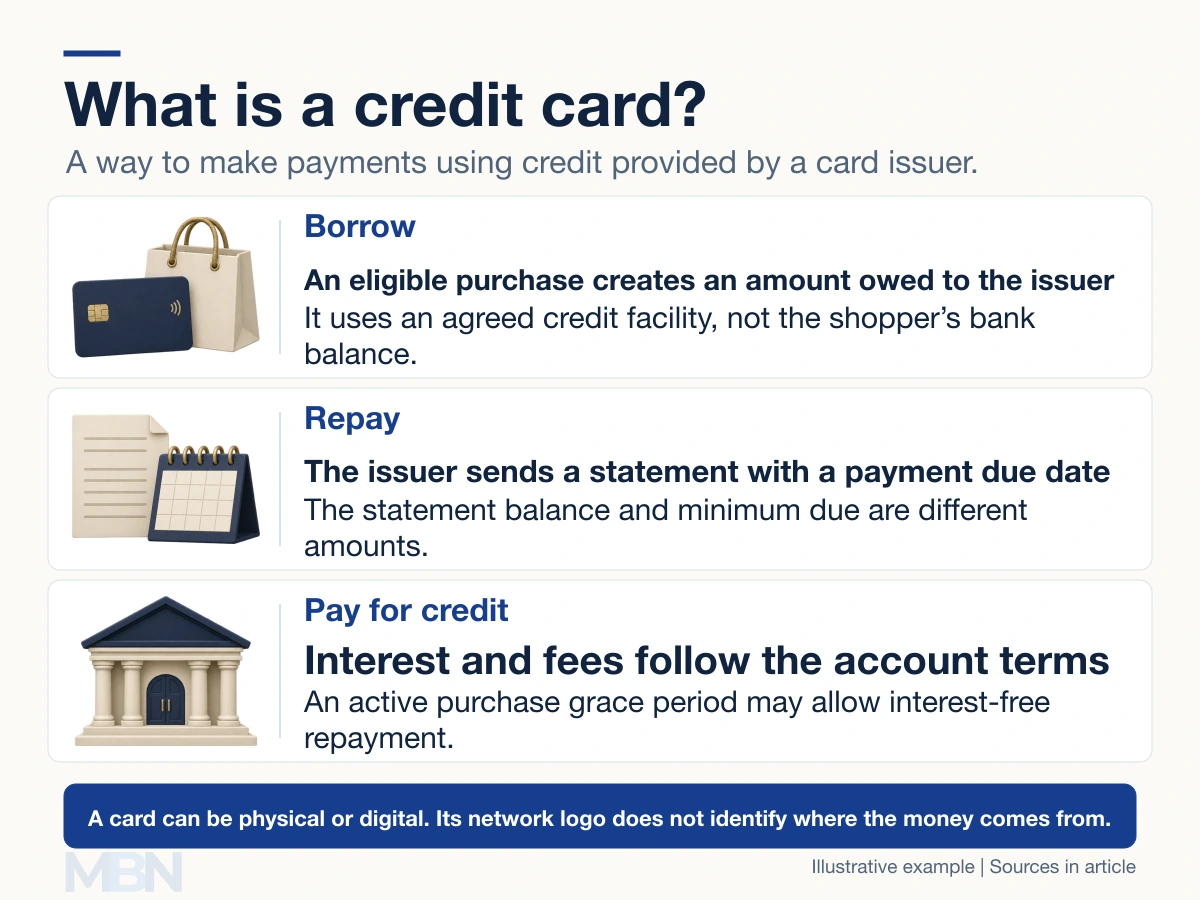
A credit card lets its holder make payments using credit provided by an issuer. Spending creates an amount owed to that issuer, rather than automatically using the money in the cardholder’s bank account.
The card may be physical, virtual or represented by payment credentials in a digital wallet. Most ordinary credit-card accounts allow repeated borrowing and repayment within an agreed limit.
How is it different from a debit or prepaid card?
The CFPB separates credit-card borrowing from debit and prepaid spending. A debit card normally uses money in a linked bank or credit-union account. A prepaid card uses money loaded into its card account. Overdraft or other credit features can add separate borrowing.
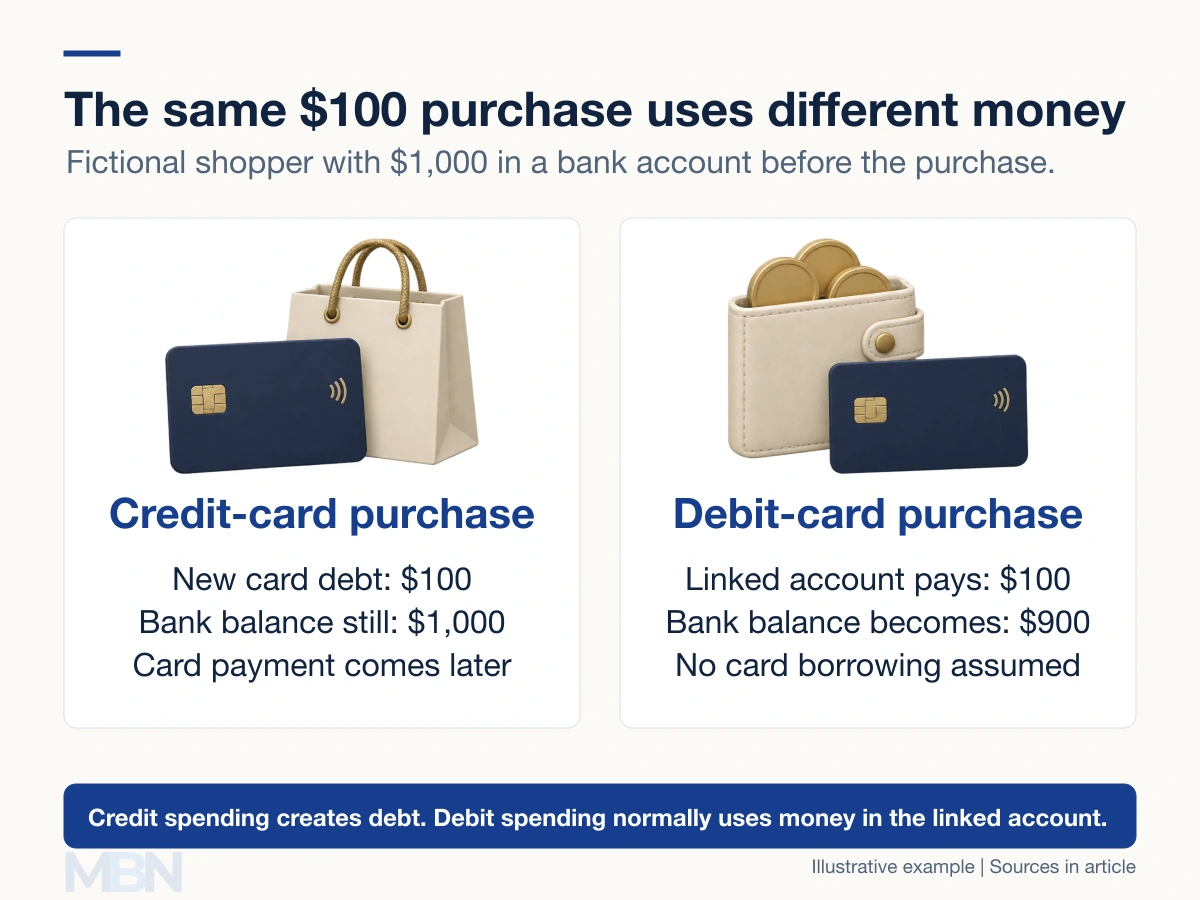
A fictional $100 credit-card purchase creates $100 owed to the issuer. With no automatic repayment, it leaves a $1,000 bank balance unchanged at that moment. A $100 debit purchase normally reduces that bank balance to $900 once settled.
A charge card traditionally requires payment in full. Some modern products also allow eligible charges to be carried with interest, as American Express’s Pay Over Time terms illustrate. The agreement determines which amounts must be paid in full.
How do statements and interest work?
The statement records activity for a billing period and sets out the balance, minimum payment and due date. New transactions after the statement closes can make the current balance different from the statement balance.
A purchase grace period depends on the card’s terms and payment history. With an eligible balance and an active grace period, paying the full statement balance by the due date can avoid purchase interest. Cash advances generally start accruing interest immediately.
Paying only the minimum can leave debt outstanding. The annual percentage rate, or APR, expresses a yearly borrowing rate, while actual charges depend on balances and timing. Rewards, insurance and purchase protections are product benefits with conditions, not universal features.
Who issues a card and who runs its network?
The issuer provides and services the account. The payment network helps route transactions between participating institutions and merchants. Visa explains that account management is handled by its client financial institutions. A network mark alone does not say whether a card is credit, debit or prepaid.
Some corporate groups combine issuing and network businesses. Capital One completed its acquisition of Discover Financial Services on May 18, 2025. Describing Discover as a separate independent company is now outdated.
When did modern cards develop?
Diners Club dates the launch of its multipurpose charge card to 1950. That differs from earlier single-merchant arrangements and from a revolving bank credit card.
Federal Reserve History traces BankAmericard to 1958 and its Visa rebranding to 1976. Modern card payments developed through several products and institutions, rather than one universally agreed “first credit card”.
Last checked and updated on November 4, 2026 by the MBN editorial team.