
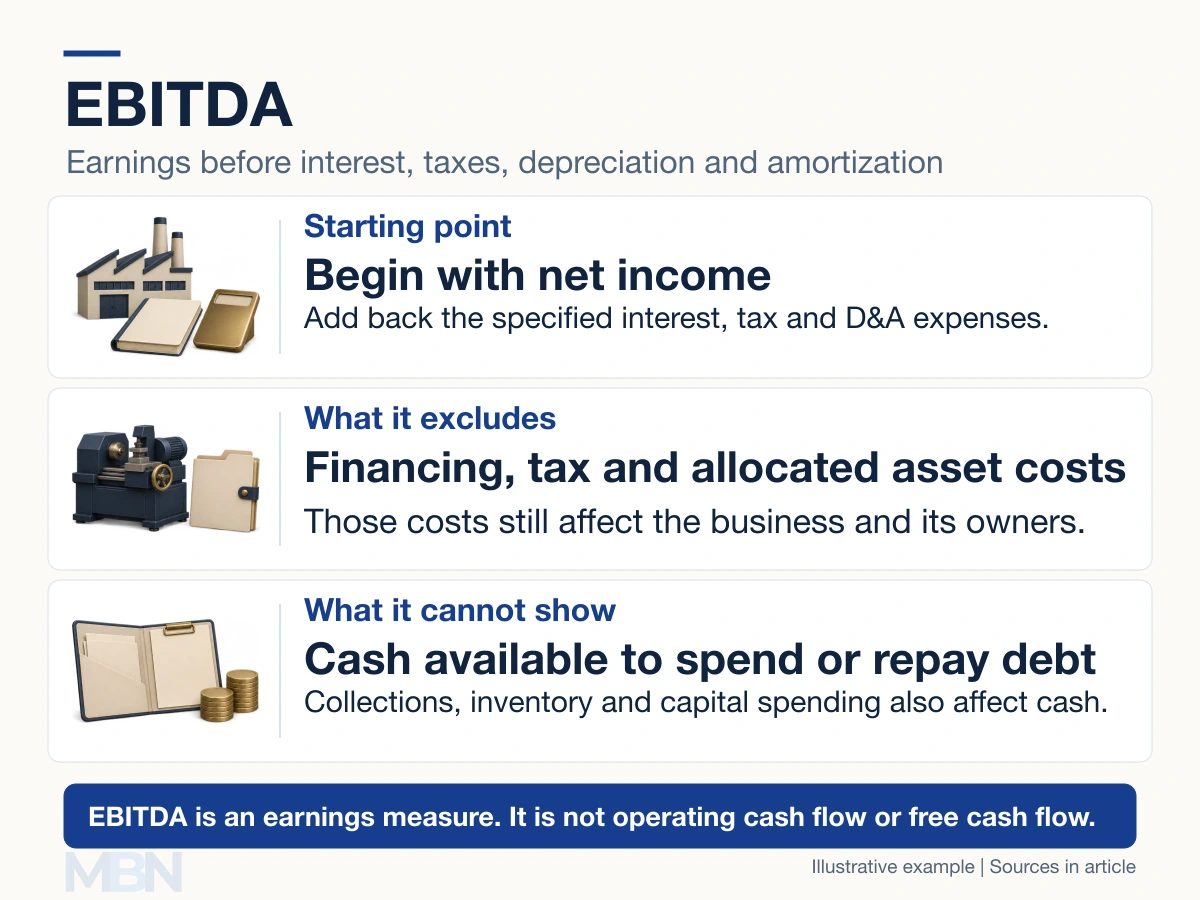
EBITDA means earnings before interest, taxes, depreciation and amortization. It is an earnings measure that adds specified expenses back to net income. It does not measure the cash a company has available to spend or repay debt.
Companies and analysts use EBITDA to compare earnings before some effects of financing, income taxes and the allocation of long-lived asset costs. For US public-company reporting it is a non-GAAP measure, meaning it is outside generally accepted accounting principles.
How EBITDA is calculated
The basic formula is: EBITDA = net income + interest expense + income tax expense + depreciation + amortization. The exact reconciliation must explain the treatment of interest income and any other relevant items.
Depreciation allocates the depreciable cost of a tangible asset, such as machinery, over its useful life. Amortization generally allocates the cost of a finite-lived intangible asset, such as certain purchased licenses. These allocations recognize costs; they are not automatically accounting distortions.
The SEC’s EBITDA guidance defines earnings as GAAP net income. It also says a measure with additional adjustments should have a different name, such as adjusted EBITDA.
Operating profit plus depreciation and amortization is sometimes used as a shortcut. It can produce a different figure if net income contains non-operating items that the shortcut omits. The reconciliation identifies what was actually included.
A worked calculation and margin
Suppose a company reports annual revenue of $500,000 and operating expenses of $400,000 excluding depreciation and amortization. Its depreciation and amortization total $20,000, interest expense is $10,000 and income tax expense is $14,000. Assume no other income or expenses.
Operating profit is $80,000 and net income is $56,000. Adding back $10,000 interest, $14,000 tax and $20,000 depreciation and amortization gives EBITDA of $100,000.
EBITDA margin = EBITDA ÷ revenue × 100. The example’s margin is $100,000 ÷ $500,000 × 100 = 20%. Its net profit margin is 11.2%. The percentages answer different questions because they include different costs.
Why EBITDA is not cash flow
A company can recognize revenue before receiving the customer’s payment. It can also use cash to build inventory or buy equipment. Those cash movements do not appear in EBITDA in the same way they appear in the cash-flow statement.
Continue the example. Assume interest and tax paid equal the expenses above, working capital absorbs $40,000 of cash, and there are no other operating cash adjustments. Operating cash flow is $56,000 net income + $20,000 noncash depreciation and amortization − $40,000 working-capital outflow = $36,000.
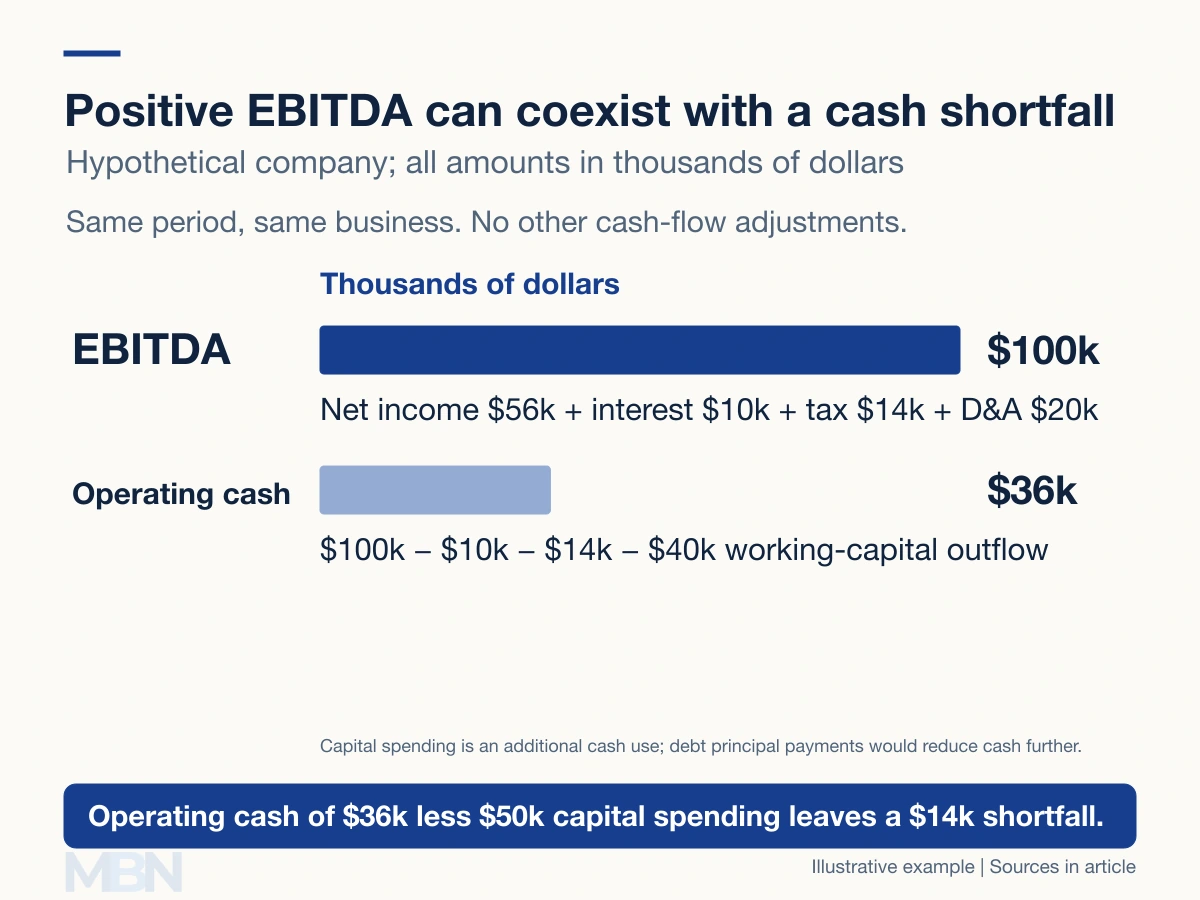
If the company then spends $50,000 on equipment, operating cash flow less capital spending is negative $14,000. Positive EBITDA of $100,000 has coexisted with a cash shortfall before borrowing or other financing. These are hypothetical figures, not a forecast.
The SEC’s financial-statement guide explains how the cash-flow statement adjusts earnings for noncash items and changes in operating assets and liabilities. Cash-flow classifications can differ between accounting frameworks, so comparisons need a consistent basis.
Adjusted EBITDA and debt ratios
Adjusted EBITDA may exclude restructuring charges, share-based compensation or other items selected by management. Two companies using that name can exclude different costs. A recurring cost can still consume resources even when management removes it from an adjusted figure.
Debt-to-EBITDA ratios compare a debt balance with a period’s earnings measure. A $300,000 debt balance divided by $100,000 annual EBITDA is 3 times. That is not a three-year repayment schedule: interest, taxes, reinvestment, working capital and loan terms affect repayment capacity.
The SEC reporting manual identifies EBITDA and adjusted EBITDA as non-GAAP measures. Their definitions and reconciliations should be read alongside net income, operating cash flow, capital spending and debt obligations.
Last checked and updated on November 11, 2026 by the MBN editorial team.