
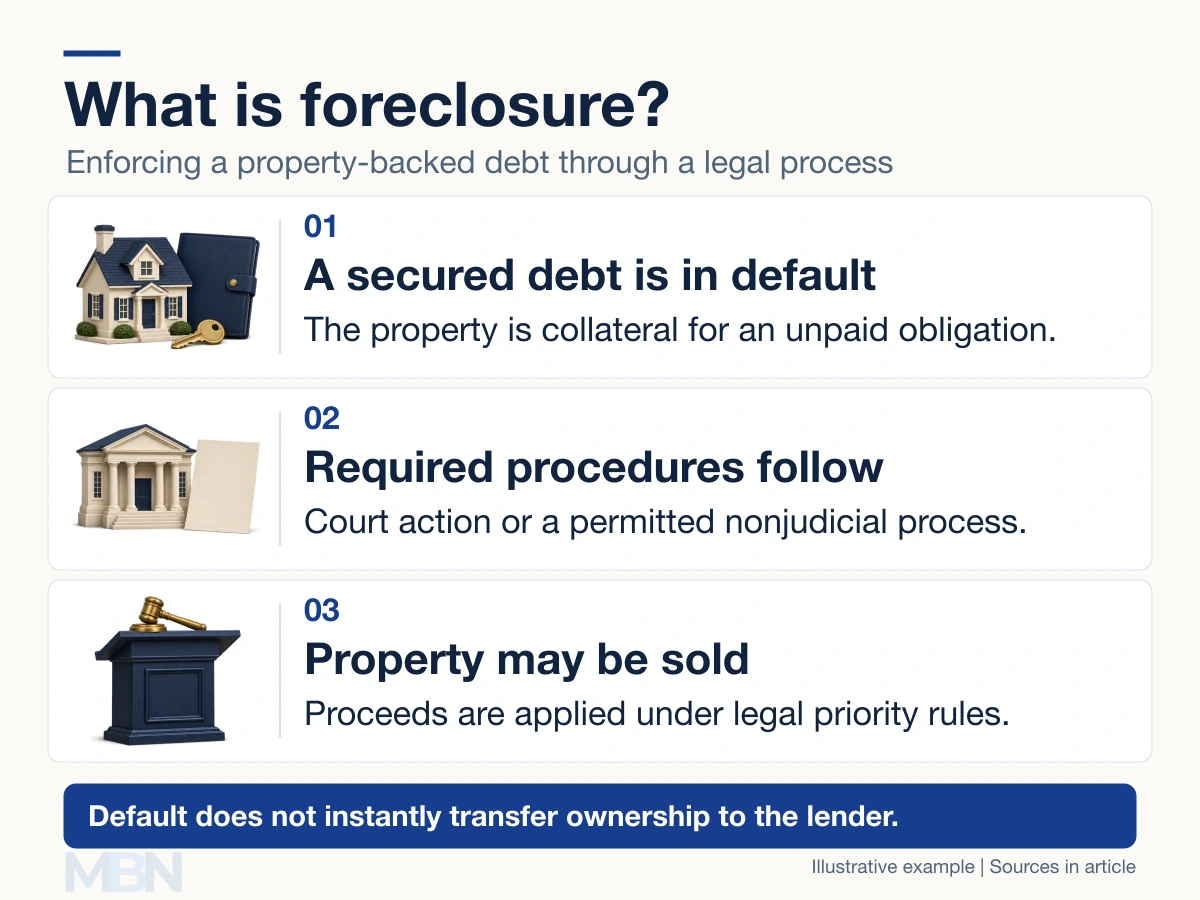
Foreclosure is a legal process used to enforce a debt secured by property after default. In a home mortgage foreclosure, the property may be sold so the proceeds can be applied to the unpaid obligation.
A lender does not necessarily take ownership before the sale, and a missed payment does not instantly transfer the home. The process, notices and borrower protections depend on the jurisdiction and loan documents. The examples below explain US mortgage foreclosure.
Judicial and nonjudicial foreclosure
The Consumer Financial Protection Bureau describes two main US processes. Judicial foreclosure involves a lawsuit and court proceedings. The borrower can raise defenses in court.
Nonjudicial foreclosure uses a power-of-sale procedure permitted by state law and the mortgage or deed of trust. It generally proceeds through required notices and a sale without the lender first bringing a foreclosure lawsuit. Nonjudicial does not mean that the lender can ignore legal safeguards.
The lender may bid at the sale, but another buyer may purchase the property. Foreclosure sale, transfer of title and any later eviction or possession proceedings are separate steps governed by applicable law.
What happens before the sale
“Pre-foreclosure” commonly describes a period after serious payment trouble or a default notice but before foreclosure is completed. It is not a uniform legal status with one national starting date.
For mortgage loans covered by the relevant US federal servicing rules, the first notice or filing generally cannot be made until the loan is more than 120 days delinquent. Regulation X contains exceptions and additional loss-mitigation procedures. The 120-day rule is not a promise that a property will be sold on day 121, or a universal rule for every secured debt.
Loss mitigation means arrangements intended to address payment difficulty or avoid foreclosure, such as a repayment plan or loan modification. Eligibility, application timing and the protections triggered by a complete application depend on the rules. Submitting an application does not guarantee a particular modification.
What is a deficiency judgment?
A deficiency is a shortfall when the amount legally credited from a sale is insufficient to satisfy the relevant debt. A deficiency judgment is a court order establishing a borrower’s liability for an allowed shortfall.
Suppose a simplified hypothetical mortgage debt is $280,000 and net sale proceeds, after sale costs, are $250,000. The arithmetic shortfall is $30,000. Whether that amount can be recovered requires a separate legal assessment.
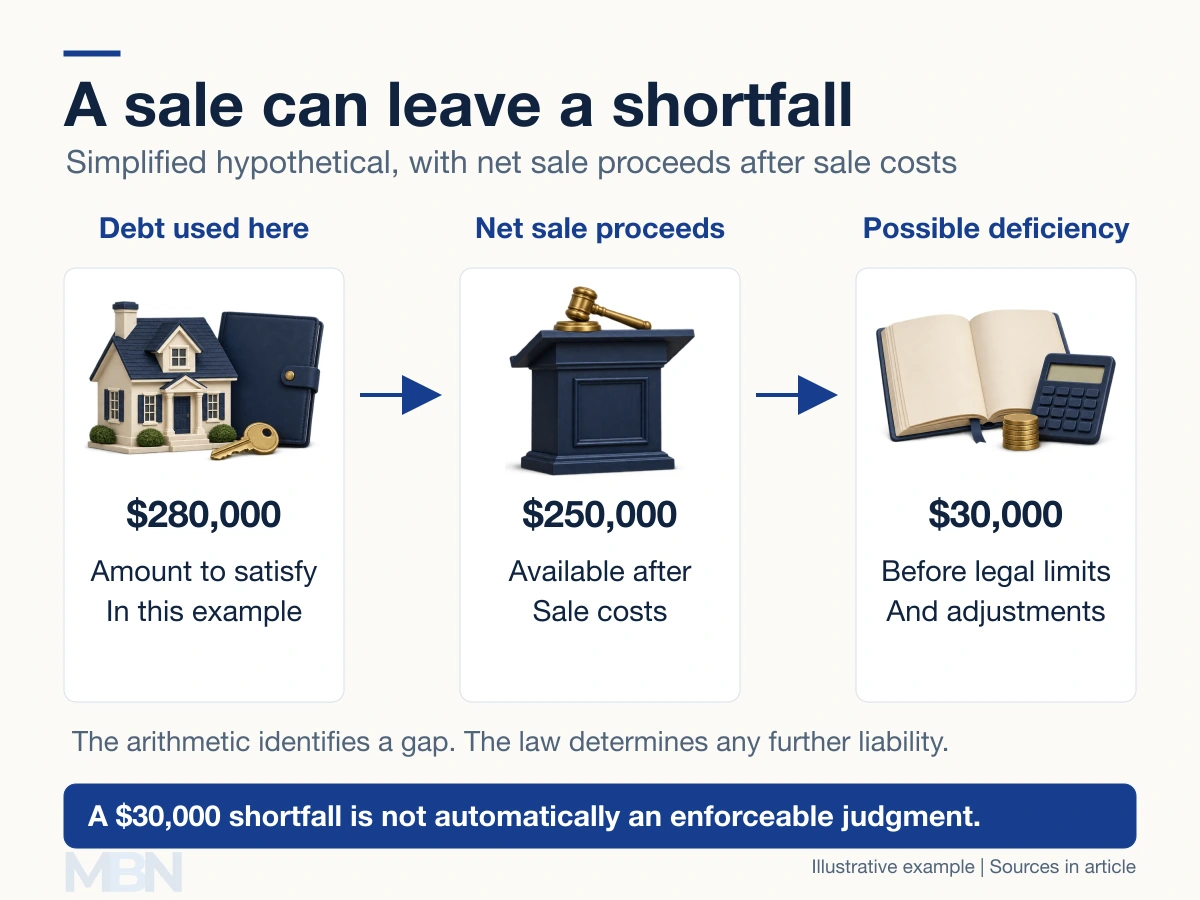
The CFPB’s mortgage disclosure rules explain that continued liability after foreclosure varies by state. Anti-deficiency protections, the kind of loan, the foreclosure procedure and other legal limits can restrict or prohibit recovery. A lender cannot simply declare its own judgment or seize anything the borrower owns.
Texas provides one example of a further adjustment: its state law library explains fair-market-value protections that may reduce a deficiency claim. That rule should not be assumed to apply everywhere.
How sale proceeds are treated
Sale proceeds are distributed according to applicable costs and lien priorities. A surplus may remain for someone entitled to it after the relevant claims are satisfied. The gross sale price alone does not establish the borrower’s final position.
Foreclosure is different from a voluntary sale, a lender-approved short sale or a deed in lieu of foreclosure, in which property is transferred by agreement. Those alternatives can also leave questions about remaining debt. For an actual case, the controlling documents, notices and local law determine the result.
Last checked and updated on November 5, 2026 by the MBN editorial team.