
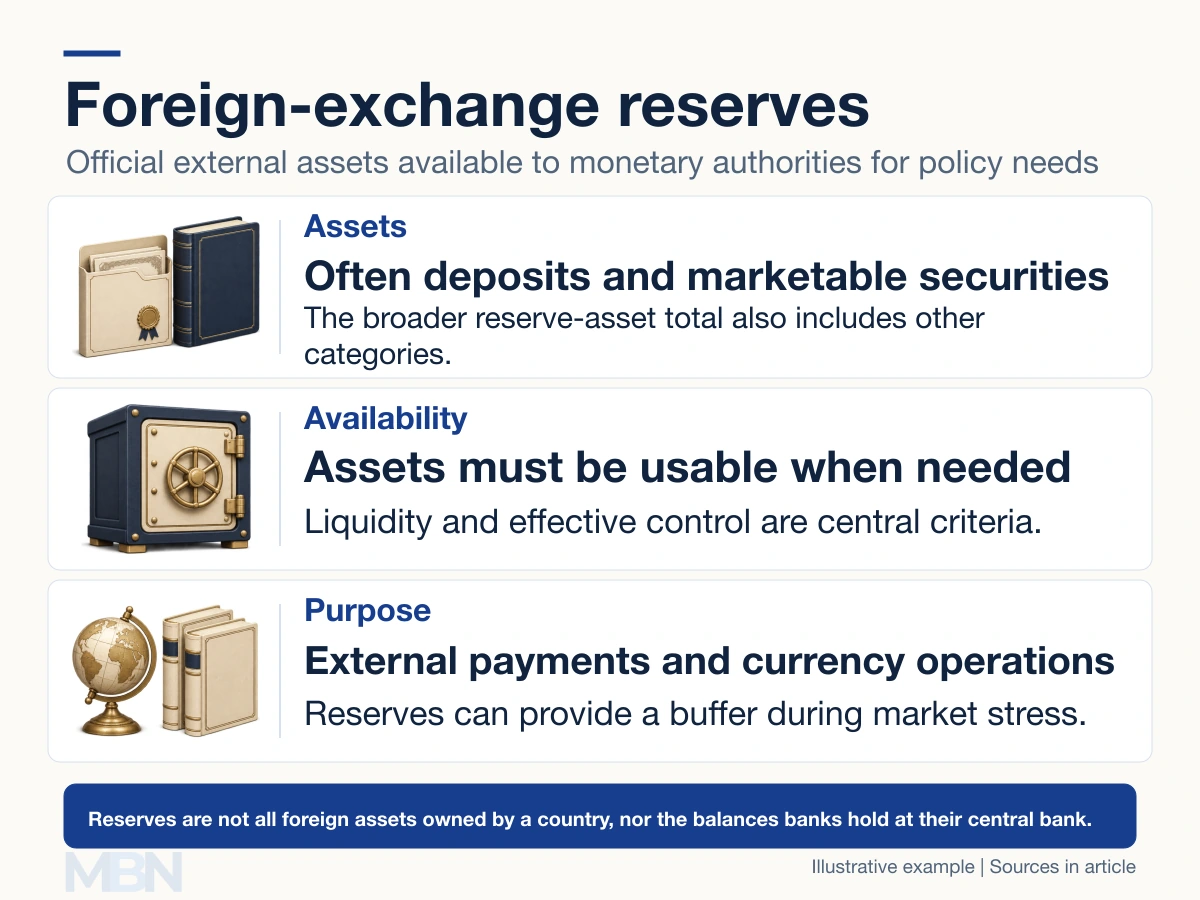
Foreign-exchange reserves are official foreign-currency assets available to a country’s monetary authorities for external payments and policy operations. They commonly include foreign-currency deposits and marketable securities, rather than only physical notes held in a vault.
The broader term “official reserve assets” also covers monetary gold, Special Drawing Rights and the reserve position in the International Monetary Fund. Published totals therefore need to be read with their stated definition.
What qualifies as a reserve asset?
The IMF’s reserve-asset framework emphasizes external assets that are readily available to and controlled by monetary authorities. A foreign investment does not automatically qualify simply because the government owns it.
Foreign-currency deposits and securities are one category. Monetary gold is gold held as a reserve asset. Special Drawing Rights, or SDRs, are IMF-created international reserve assets that can be exchanged for usable currencies. The reserve position in the IMF is another liquid claim available under the Fund’s arrangements.
These official assets are different from a commercial bank’s reserves at its central bank, and from all foreign investments owned by the country’s households, companies or sovereign wealth funds.
Why monetary authorities hold reserves
Reserves can provide foreign-currency liquidity, support external financing and enable exchange-market operations. The ECB describes its reserve-management priorities as liquidity, security and returns, in that order. Maximizing investment return is not the sole objective.
To support a currency under selling pressure, an authority may sell foreign reserves and buy domestic currency. To resist upward pressure, it may buy foreign currency and supply domestic currency. The transactions can affect the domestic monetary base unless offset by other operations.
A fixed exchange-rate commitment can require intervention to keep the rate near its target. Fixing the rate does not remove the need for reserves; defending it can consume them. A floating-rate country can also hold reserves without targeting a fixed exchange rate.
Transactions and valuation changes
A change in the reported reserve total does not equal the amount bought or sold in the market. Exchange rates and security prices can change the reporting value of existing holdings. The Bank of England explains end-period market-price and exchange-rate valuation.
Suppose reserves open at $100 billion. Purchases of $5 billion and sales of $2 billion add $3 billion through net transactions. A further $3 billion valuation gain takes the closing stock to $106 billion, assuming no other changes.
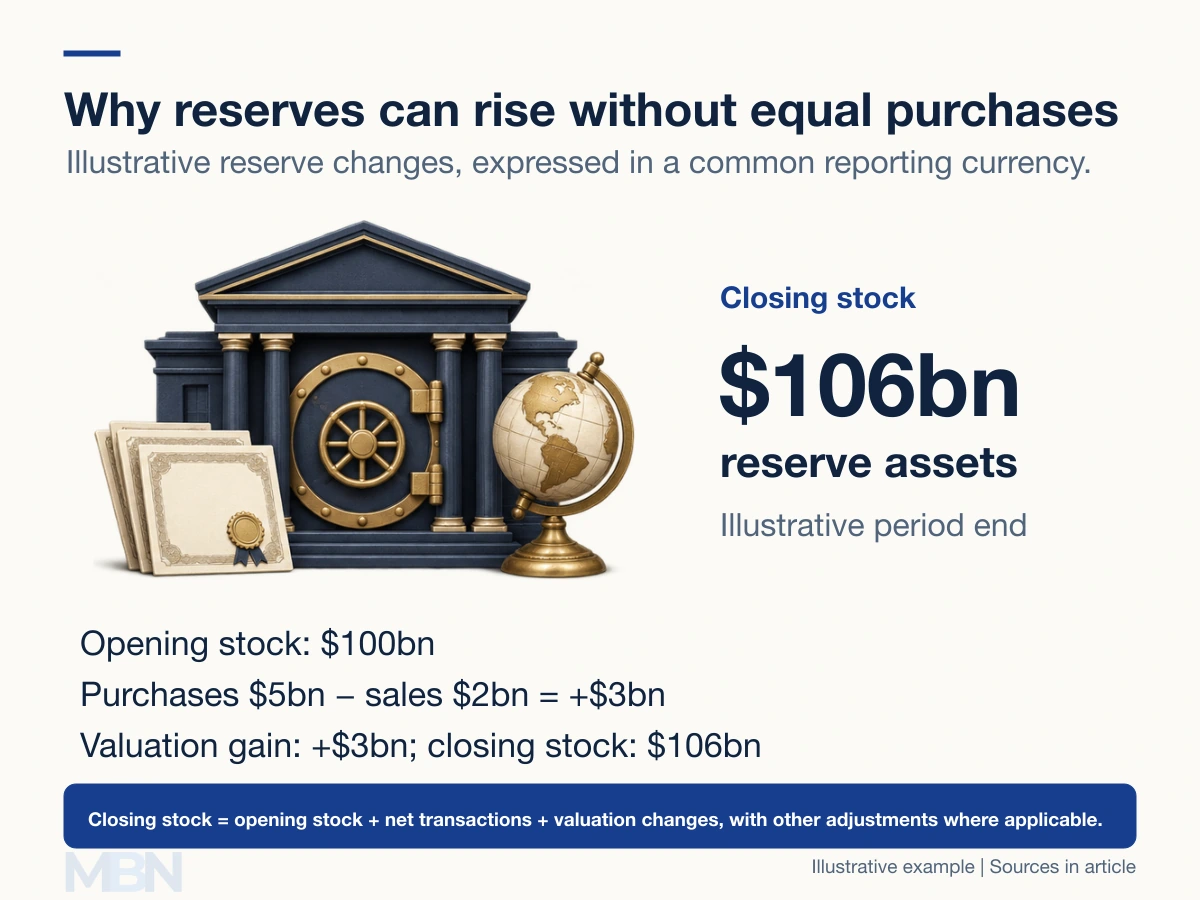
Only half of the $6 billion increase in that example comes from net purchases. A valuation loss could instead offset purchases or reduce reported reserves even without an intervention sale.
How much is enough?
Reserve adequacy depends on potential foreign-currency needs, including imports, short-term external debt, capital-flow pressures and the exchange-rate regime. The IMF’s reserve-adequacy guidance assesses these circumstances rather than imposing one universal total.
Gross reserve assets also differ from measures that deduct specified liabilities or commitments. Availability, maturity, currency composition and possible drains matter alongside the headline amount. Large reserves can provide resilience, but they do not guarantee a stable currency or prevent every financial crisis.
Last checked and updated on November 11, 2026 by the MBN editorial team.