
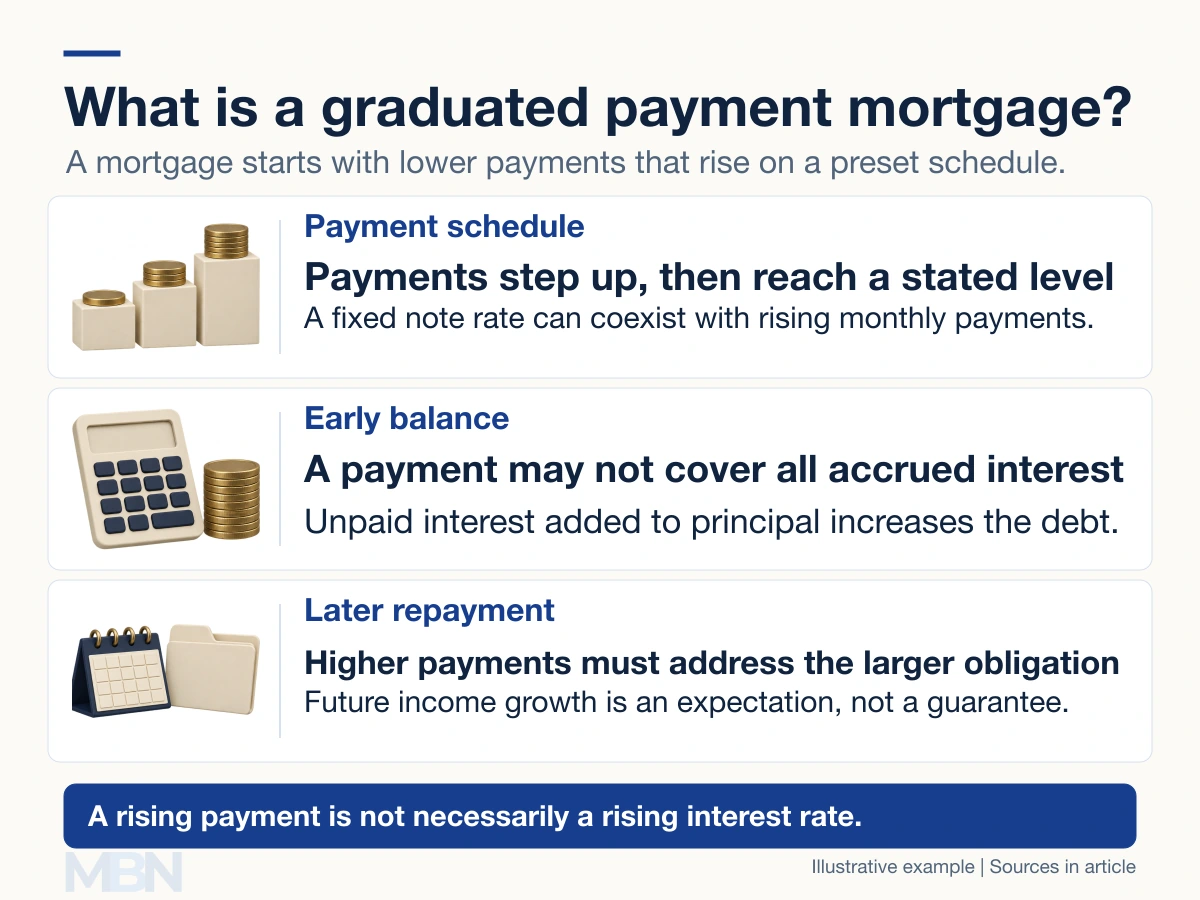
A graduated payment mortgage, or GPM, starts with relatively low scheduled payments that increase at agreed intervals before leveling off. In the traditional fixed-rate version, the payment schedule changes while the interest rate stays the same.
The arrangement shifts more of the repayment burden into later years. It does not guarantee that a borrower’s earnings will rise enough to match the higher payments.
Payments and interest rates are different
The note rate is the contractual interest rate. The scheduled payment is the amount due at a particular time. A GPM can increase that amount without changing the note rate.
For covered US mortgages, Regulation Z distinguishes step-payment features from adjustable interest rates. An adjustable-rate mortgage changes its rate under a separate contractual mechanism. The two features should not be treated as interchangeable.
What is negative amortization?
Amortization is repayment that reduces the loan balance. Negative amortization occurs when unpaid interest is added to the balance, so the debt grows despite payments being made.
Traditional GPM designs can produce negative amortization during the low-payment stage. The later schedule must account for that larger balance. A low initial payment is therefore different from a low financing cost.
A two-month example
Suppose a fictional mortgage has a $100,000 balance and a fixed nominal annual rate of 6%, calculated monthly. The first month’s interest is $100,000 × 0.5% = $500. A $400 payment leaves $100 unpaid. If that interest is added to principal, the balance becomes $100,100.
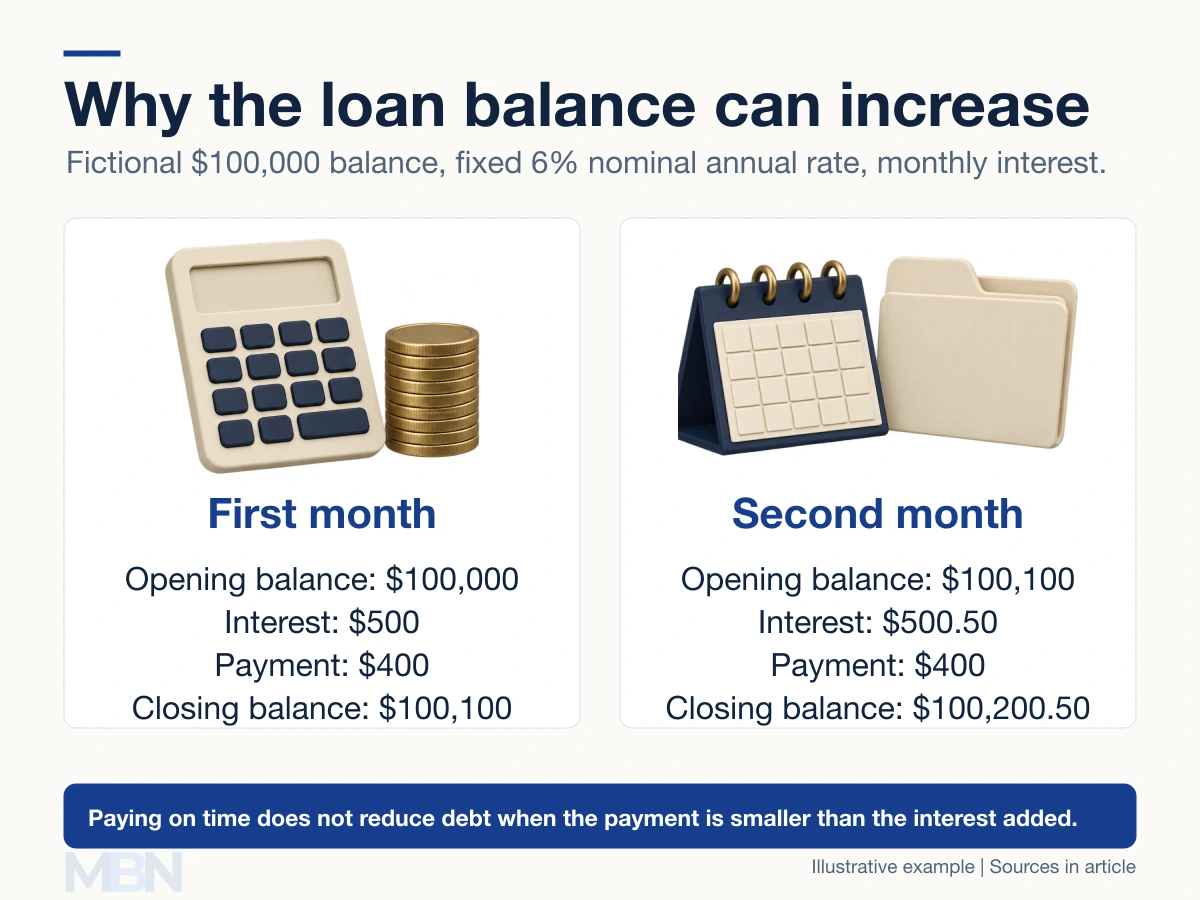
The next month’s interest is $500.50. Another $400 payment leaves $100.50 to be added, producing a $100,200.50 balance. This simplified example isolates negative amortization, rather than showing a complete GPM repayment plan.
How payment increases are specified
A contract states how much payments rise and how long the increases continue. A fictional 5% annual payment increase would turn $400 into $420, then $441. Those percentages apply to payments, not necessarily to the loan’s interest rate.
HUD’s FHA Connection documentation lists Section 245(a) GPM plan codes with payment increases of 2.5%, 5% or 7.5% for five years, and 2% or 3% for ten years. This is program documentation, last revised in 2010, rather than evidence that a particular lender offers those plans today. HUD also retains its Graduated Payment Mortgage Program handbook.
How it differs from a growing equity mortgage
As HUD’s loan-closing guidance explains, a growing equity mortgage uses scheduled payment increases to accelerate principal repayment rather than create negative amortization. The similar names describe different balance paths.
For a GPM, the full schedule, maximum payment, potential balance increase and total financing cost explain the obligation. A borrower’s occupation or expected promotion does not establish that the future payments will be affordable.
Last checked and updated on November 4, 2026 by the MBN editorial team.