
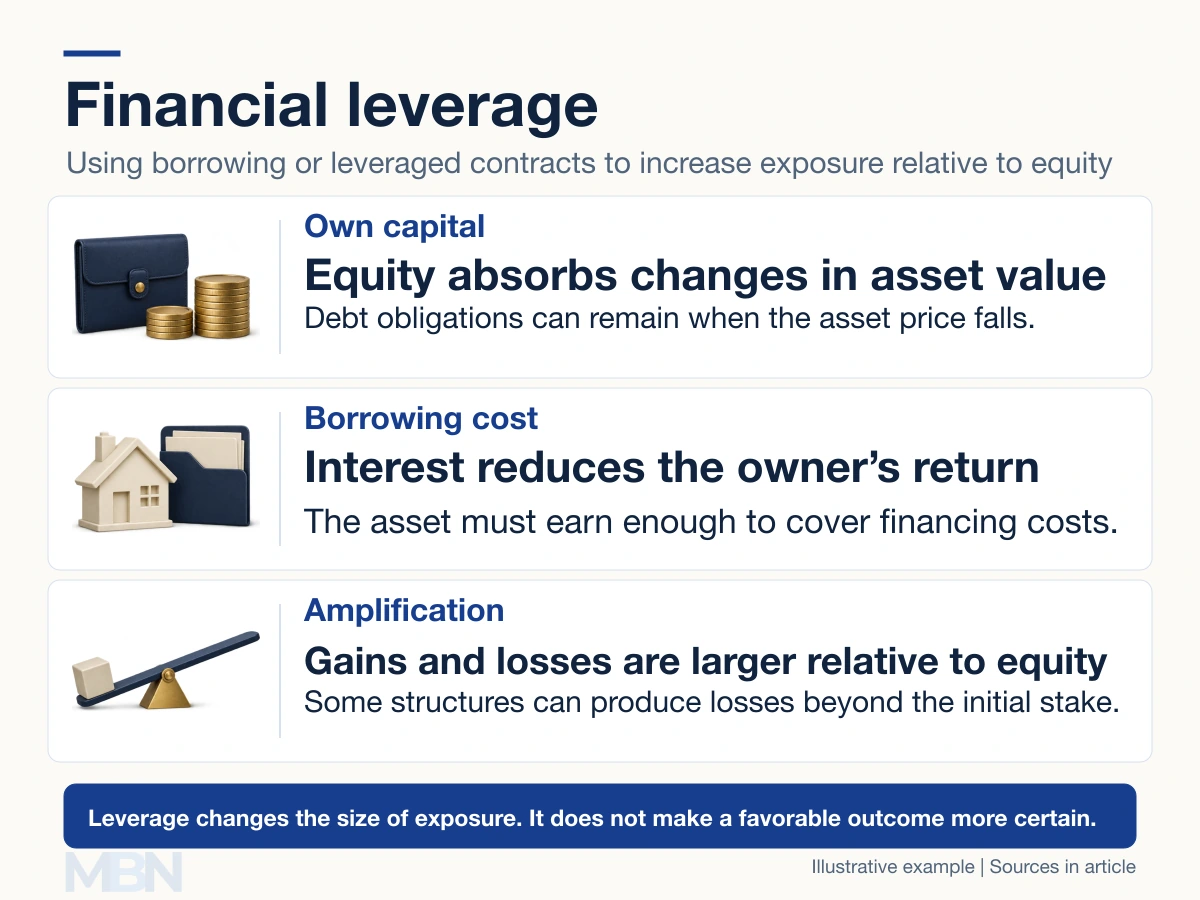
Financial leverage uses borrowing, or contracts with a similar effect, to increase exposure relative to the owner’s capital. It magnifies gains and losses on that capital, while interest and other financing obligations can remain payable even when the investment performs badly.
A business borrowing to buy equipment, a household financing a home with a mortgage and an investor buying securities on margin all use financial leverage. The rights and risks differ between those arrangements. Gearing is a related term, especially in British financial usage.
How borrowing changes the owner’s return
Suppose an asset costs $100. An investor supplies $20 and borrows $80 for one year at 5% interest, producing a $4 interest bill. Assume the loan is fully repayable, the asset pays no income and there are no taxes, fees or earlier forced sales.
If the asset sells for $110, repaying $80 principal and $4 interest leaves $26. The investor’s profit is $6 on the original $20 stake, a 30% return. The asset itself rose 10%.
If the asset sells for $90, just $6 remains after the same loan and interest payments. The investor loses $14, or 70% of the initial stake, even though the asset fell 10%.
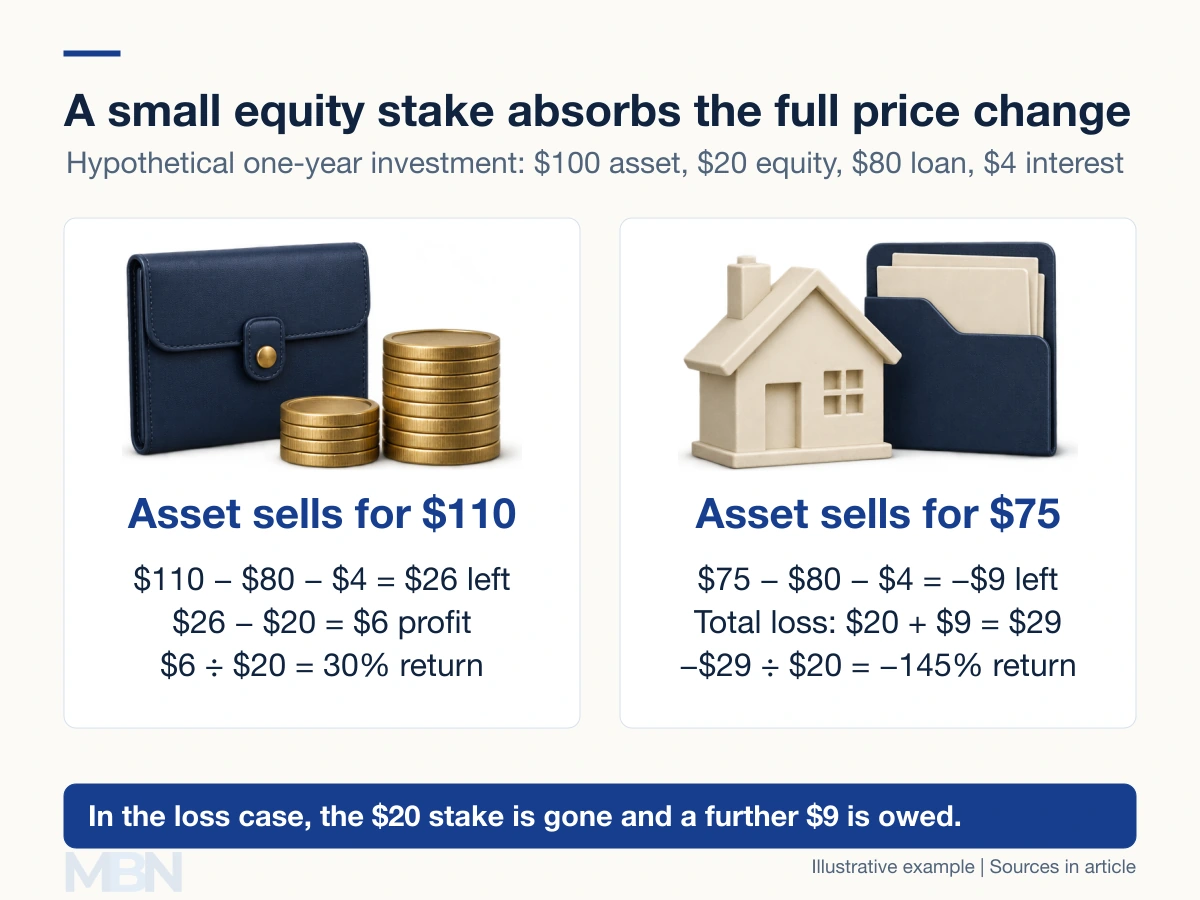
If it sells for $75, proceeds are $9 short of the $84 owed. The investor has lost the original $20 and owes another $9, a total loss of $29 or 145% of the initial investment. Whether a borrower can face that additional claim depends on the contract and applicable law.
The SEC’s margin-account bulletin explains that securities bought with borrowed money can produce losses greater than the initial investment. The hypothetical financing above illustrates the arithmetic; it is not a statement of permitted brokerage margin levels.
Interest and forced sales
The asset’s gain must cover financing costs before leverage improves the owner’s result. In the example, an unchanged $100 sale price leaves $16 after repayment and interest, a 20% loss on equity despite no change in asset price.
Interest rates can also reset. The SEC explains how margin-interest terms affect investment costs. Fees and the period for which borrowing remains outstanding also matter.
In a margin account, falling collateral values can trigger a demand for more cash or securities. A broker can sell holdings under the account agreement, including before a hoped-for recovery. A later market rebound does not undo a loss from an earlier forced sale.
Different ratios measure different things
Debt-to-equity divides a stated debt balance by equity. For the opening example it is $80 ÷ $20 = 4 times. Asset-to-equity is $100 ÷ $20 = 5 times. These figures describe the same opening position using different numerators.
For a company, the definition may use interest-bearing debt, all liabilities, book equity or another specified measure. OpenStax explains debt within a company’s capital structure. A ratio with a very small or negative equity denominator needs special care.
Banking regulation uses another convention. The Basel leverage ratio compares Tier 1 capital with a defined exposure measure, including specified off-balance-sheet exposures. A higher capital-to-exposure ratio represents more capital backing each unit of exposure, whereas a higher debt-to-equity ratio represents more debt.
Financial leverage and operating leverage
Operating leverage concerns fixed operating costs, not borrowing. Once fixed costs are covered, an extra sale can produce a relatively large increase in operating profit. Falling sales can reduce profit quickly because those costs remain.
A factory can have substantial operating leverage even without debt. Borrowing to finance that factory adds financial leverage. The OpenStax operating-leverage explanation connects this effect to the mix of fixed and variable costs. When both are high, a sales decline and financing payments can place simultaneous pressure on the business.
Last checked and updated on November 11, 2026 by the MBN editorial team.