
In pricing, markup is the amount added to a chosen cost to arrive at a selling price. A markup percentage normally expresses that addition as a percentage of cost, not as a percentage of the selling price.
A business can state markup in dollars or as a rate. The cost basis needs to be clear, because a percentage added to purchase cost is different from the same percentage added to a fully allocated cost that includes overhead.
How markup is calculated
For a positive cost, markup percentage = (selling price − cost) ÷ cost × 100. The selling price can also be written as cost × (1 + markup rate), with the rate expressed as a decimal.
The Australian Government’s export-pricing guide distinguishes the cost denominator used for markup from the revenue denominator used for gross margin. The calculation applies beyond a retailer buying from a wholesaler; manufacturers and service businesses can also use cost-based pricing.
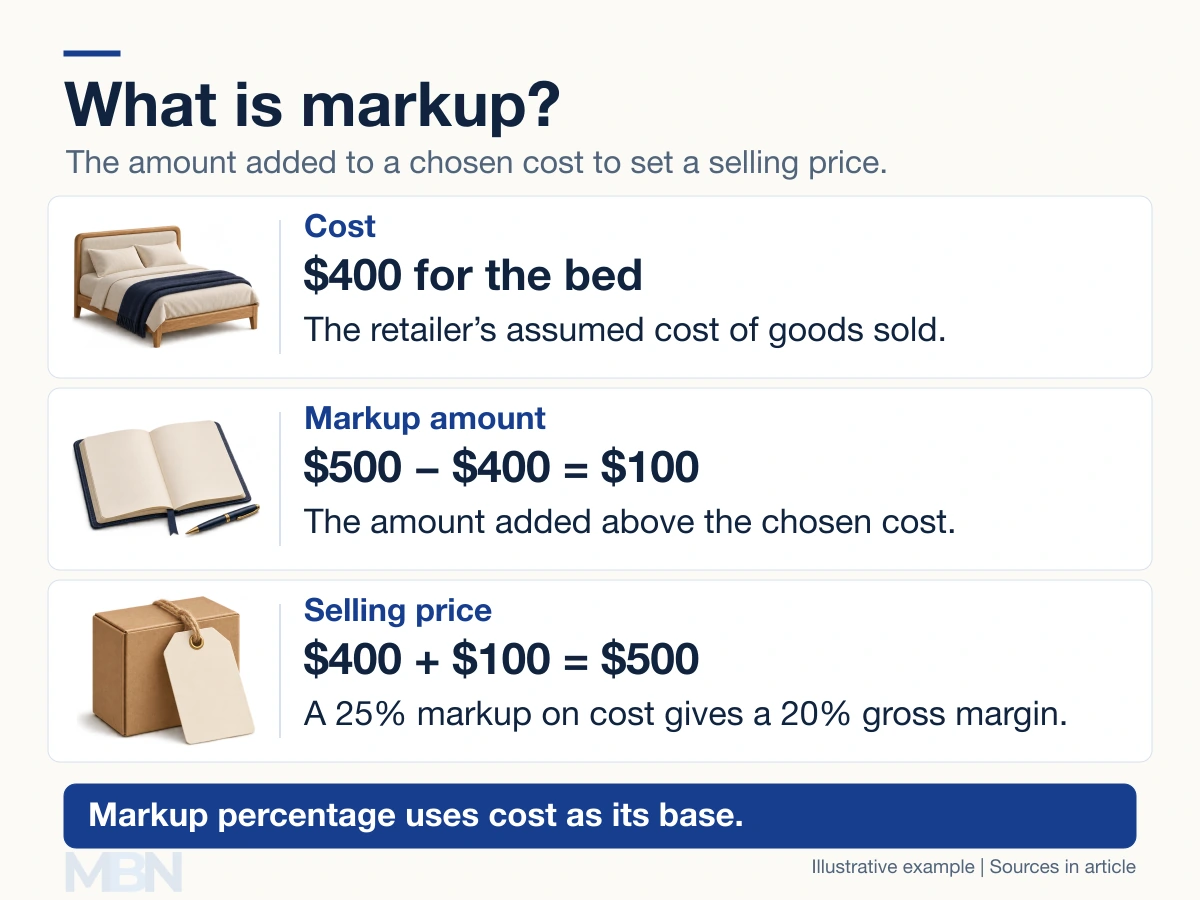
A $400 bed sold for $500
Suppose a fictional retailer’s cost of goods sold for one bed is $400 and its selling price is $500. The difference is $100. Markup on cost is $100 ÷ $400 × 100, or 25%.
Gross profit on the sale is also $100 in this example. Its gross margin percentage is $100 ÷ $500 × 100, or 20%. The same $100 is divided by a different base.
BDC’s gross-margin explanation separates gross profit, an amount of money, from gross margin, a percentage of revenue. Other operating expenses, interest and taxes still affect the business’s eventual net profit.
Why a 30% markup is not a 30% margin
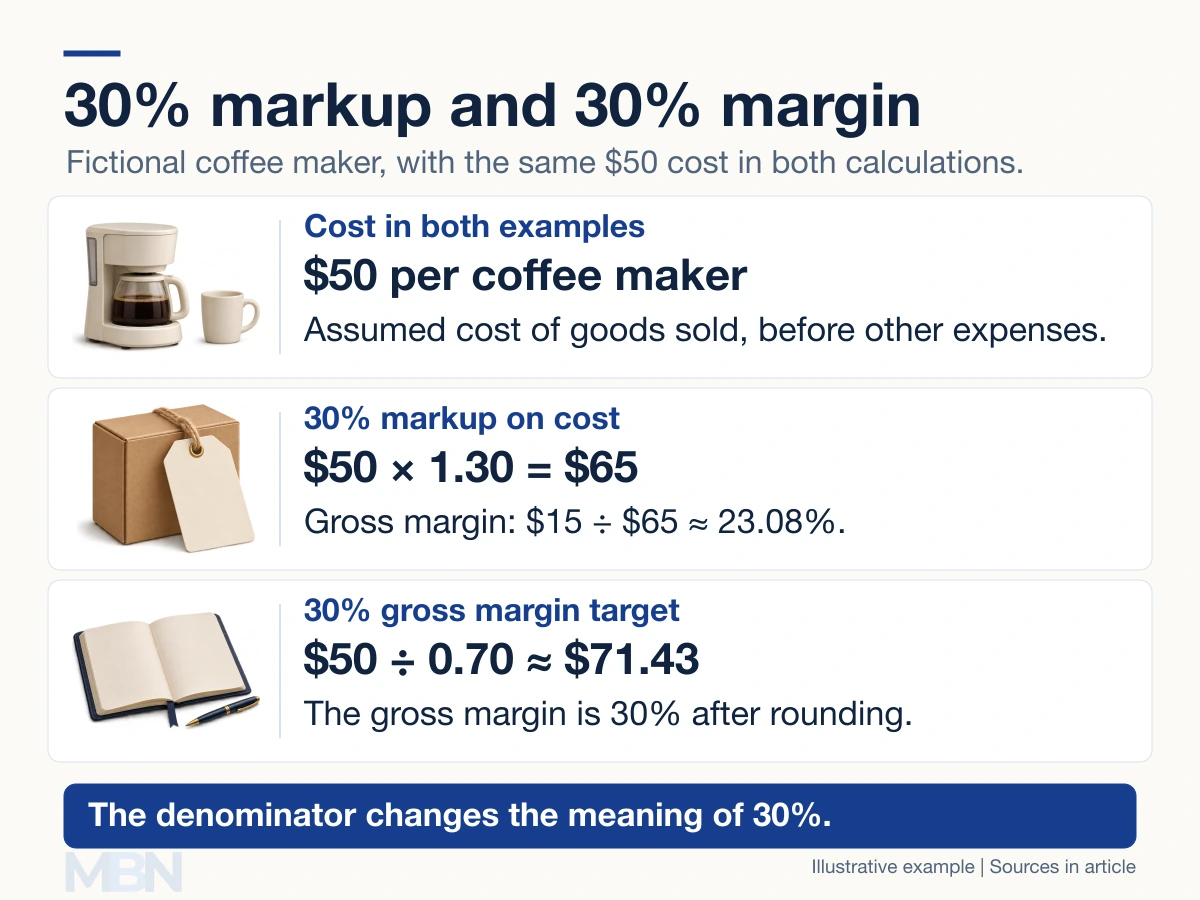
For a fictional coffee maker costing $50, a 30% markup adds $15 and produces a $65 selling price. The gross margin is $15 ÷ $65 × 100, approximately 23.08%.
To obtain a 30% gross margin on the same $50 cost, the calculation is $50 ÷ (1 − 0.30), approximately $71.43. Prices are rounded to cents and exclude sales tax in these examples.
Keystone markup and cost-plus pricing
A keystone markup doubles the selected cost. A $400 cost becomes an $800 price, a 100% markup. If that $400 is the cost of goods sold, the gross margin is 50%.
Cost-plus pricing adds a stated amount or percentage to a defined cost. Depending on the method, that cost may already include production overhead or other allocations. A markup on total cost cannot automatically be interpreted as gross profit above cost of goods sold.
A positive markup creates room to cover costs outside its chosen base. The business’s sales volume, discounts, returns and other expenses determine whether it ultimately earns a profit. Doubling cost or applying a familiar percentage does not guarantee a profitable business.
Last checked and updated on November 2, 2026 by the MBN editorial team.