
A profit margin expresses a specified profit measure as a percentage of revenue. Gross margin, operating margin and net margin use different profit figures, so the word “margin” needs a clear label.
Profit margin (%) = specified profit ÷ revenue × 100.
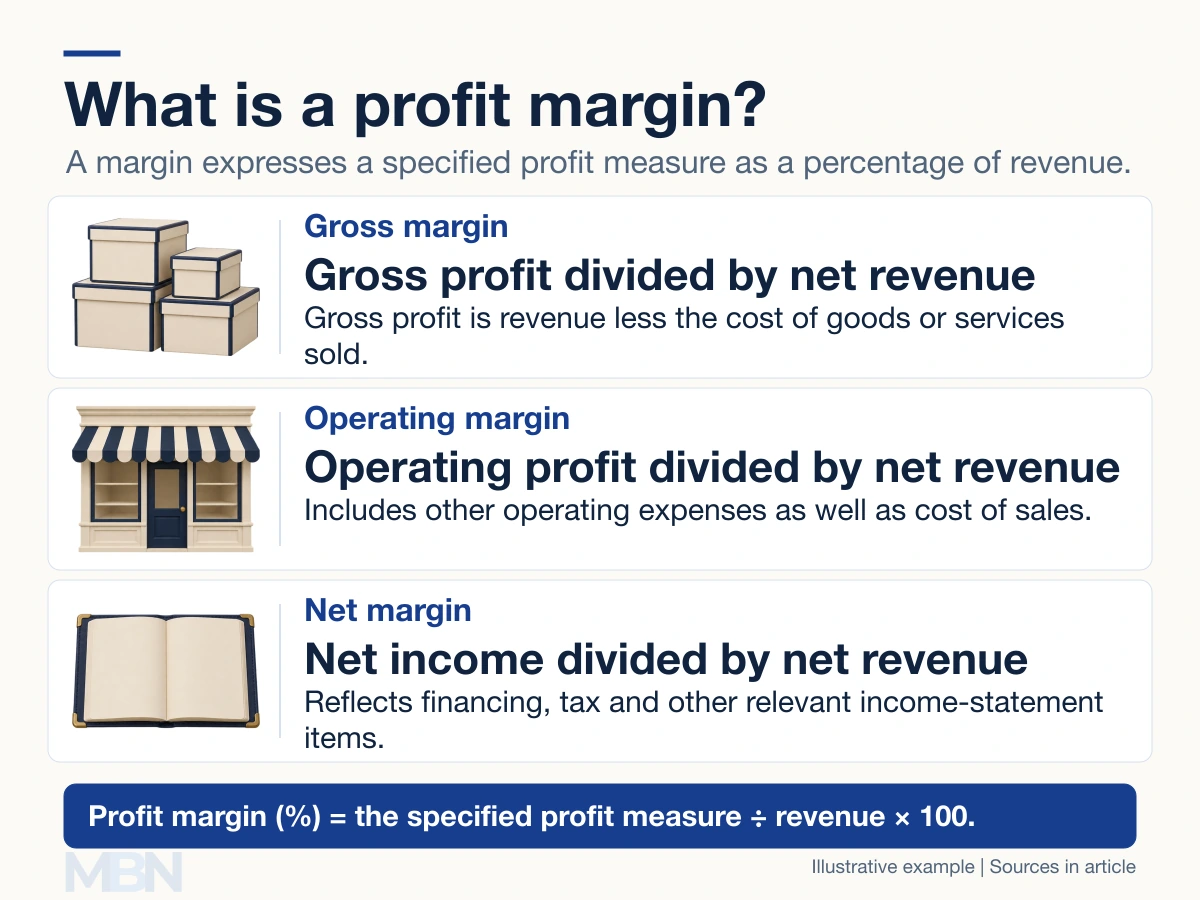
Gross, operating and net margins
Gross profit margin compares revenue less cost of sales with revenue. Cost of sales covers the recognized cost of goods or services sold. Gross profit is not simply all the money received from sales.
Operating profit margin also reflects other operating expenses, such as the relevant administrative and selling costs. Net profit margin uses net income after financing, tax and other applicable income-statement items.
OpenStax’s income-statement explanation shows how these profit levels fit together. Profit margin is an umbrella term, although people sometimes use it to mean net margin.
A worked example
Suppose a fictional business reports $1 million in net revenue and $600,000 cost of sales. Gross profit is $400,000, giving a 40% gross margin.
Subtract $250,000 of other operating expenses and operating profit is $150,000, or 15% of revenue. With $30,000 interest expense, $24,000 tax expense and no other items, net income is $96,000. Net margin is 9.6%.
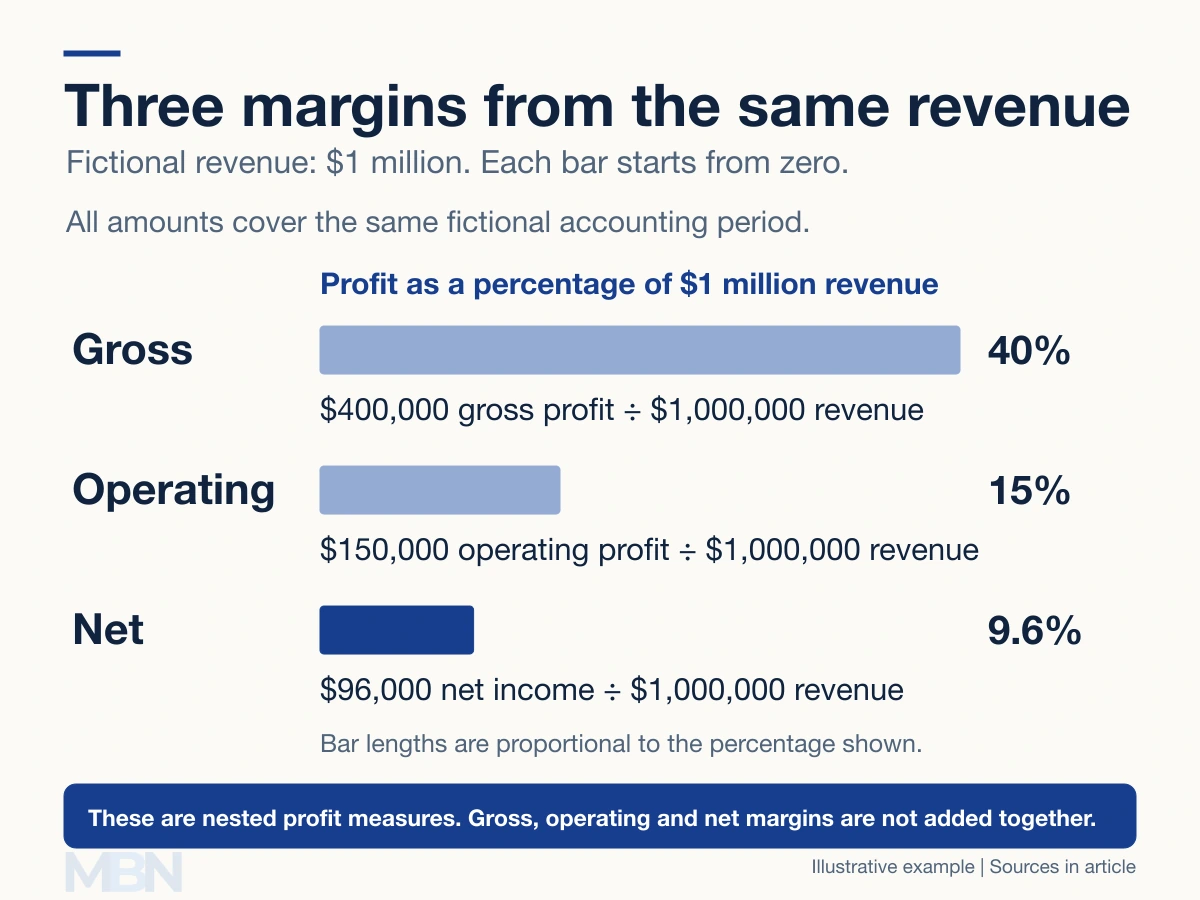
The margins describe different stages of the same income statement. They are not separate portions to add together.
Are dividends and debt repayments expenses?
Ordinary dividends on equity shares distribute earnings to owners; they are not income-statement expenses. They should not be subtracted to calculate net profit margin. Similarly, repaying loan principal reduces a debt balance rather than creating an interest expense. Interest and principal have different accounting effects.
Can profit rise while margin falls?
Yes. Suppose another fictional company earns $50 million on $100 million revenue, a 50% net margin. A year later it earns $60 million on $400 million revenue, a 15% margin. Profit rose, but the margin fell by 35 percentage points.
A percentage-point change is the difference between the two percentages. It is distinct from a percentage change in profit or revenue.
Does a higher margin mean a better investment?
Not by itself. Industry structure, growth, capital requirements, debt, risk and the price paid for the shares all matter. A high-margin company can still be an expensive investment, and a lower-margin business can generate substantial total profit.
Margin also differs from markup. If an item costs $80 and sells for $100, its $20 gross profit is a 20% margin on sales but a 25% markup on cost. The denominator changes the answer.
Last checked and updated on November 4, 2026 by the MBN editorial team.