
Profit is the excess of recognized income over the expenses included in a particular measure for a period. A company can report gross profit, operating profit or net profit, and those figures answer different questions.
Profit is also different from cash received. An income statement measures financial performance; cash-flow information shows receipts and payments.
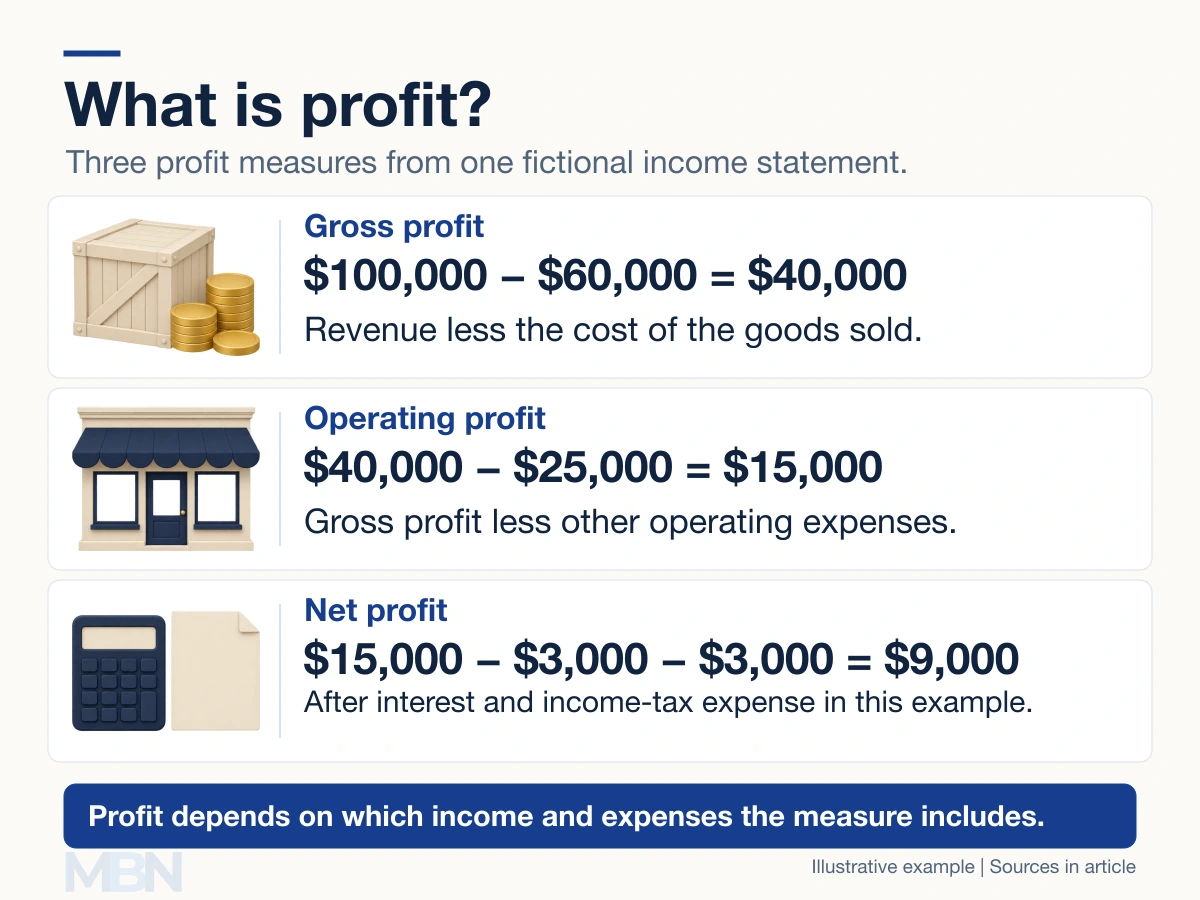
Gross, operating and net profit
The SEC’s financial statements guide explains the deductions between revenue and net income. Gross profit is revenue less the cost of sales. It is not every form of income received before tax.
Consider our fictional trading business. Revenue of $100,000 less $60,000 of goods sold leaves $40,000 gross profit. Another $25,000 of operating expenses, including depreciation, reduces operating profit to $15,000.
Assume $3,000 of interest expense, no other income or expense, and $3,000 of income-tax expense. Profit before tax is $12,000 and net profit is $9,000. Tax expense is not necessarily tax paid during the period.
Net profit margin divides net income by revenue. Here it is $9,000 ÷ $100,000 = 9%. The dollar profit and percentage margin describe different aspects of the same result.
Why profit can arrive before cash
In a separate example, suppose a business completes a qualifying $1,000 credit sale, recognizes $600 of related expense and has already paid that cost. Before the customer pays, the sale contributes $400 of profit but a cash movement of minus $600.
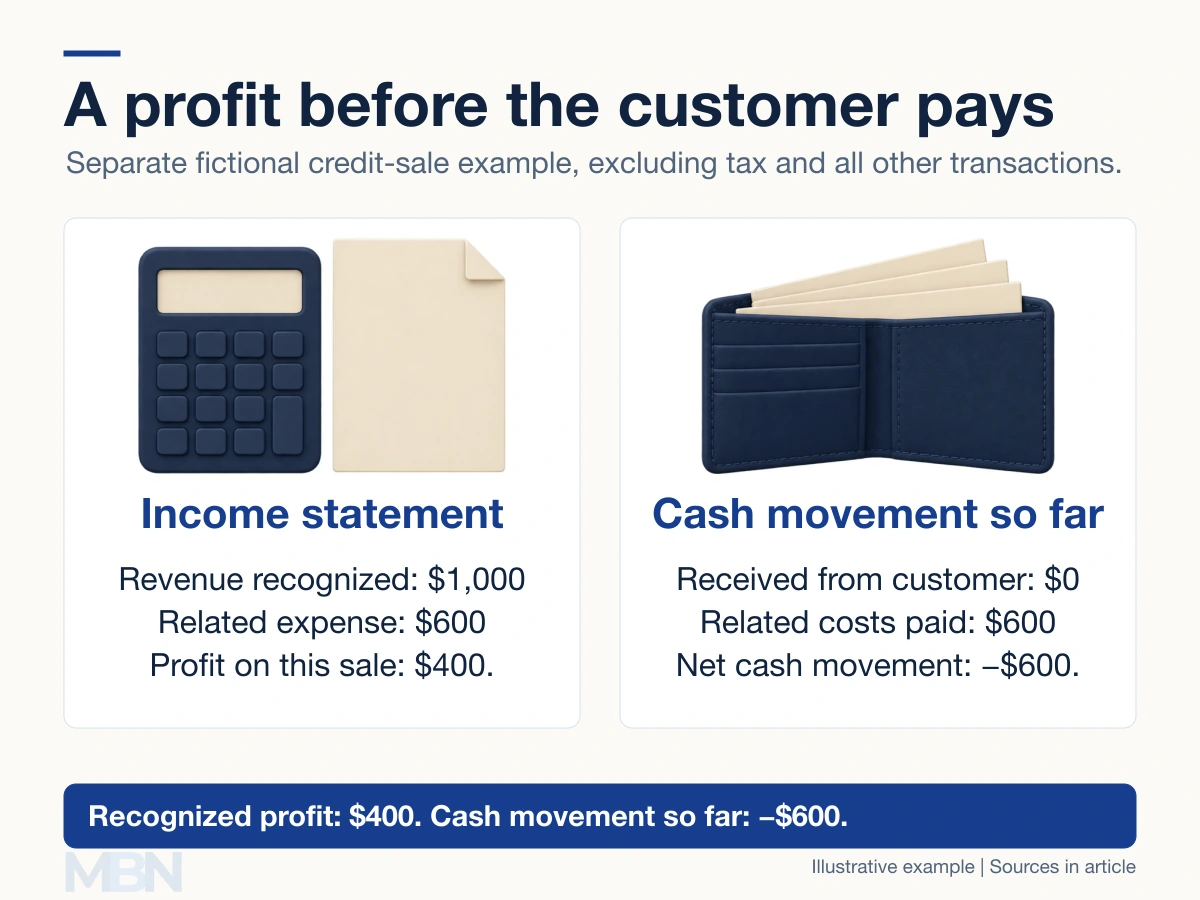
The unpaid amount is a receivable. The timing difference explains why a profitable company can still lack payment funds. Depreciation and other non-cash items also separate profit from cash flow.
What do EBIT and EBITDA leave out?
EBIT means earnings before interest and taxes. EBITDA also excludes depreciation and amortization, the allocation of certain asset costs over time.
The SEC treats EBIT and EBITDA as non-GAAP measures and explains their reconciliation. They are not automatically identical to operating profit or cash flow. Adjusted EBITDA may exclude additional items, so the company’s calculation matters.
EBITDA alone does not show cash used to buy equipment, changes in receivables and inventory, debt repayments or every other payment. Positive EBITDA therefore does not establish that a company can meet its debts.
Profitability does not establish a going concern
The IFRS Foundation’s going-concern guidance requires a broader assessment of continued operations. Profitability, financing availability and repayment timing can all matter. Being active and profitable is not sufficient on its own.
A break-even result means the relevant income and expenses are equal. A loss means expenses exceed income under that measure. Each description needs a period and a clearly identified profit measure.
Last checked and updated on November 3, 2026 by the MBN editorial team.