
Return on investment, or ROI, measures a net investment gain relative to a defined investment cost. It is usually expressed as a percentage. Basic ROI does not automatically measure cash-flow timing, annualize performance or account for risk.
Basic ROI (%) = net investment gain ÷ investment cost × 100.
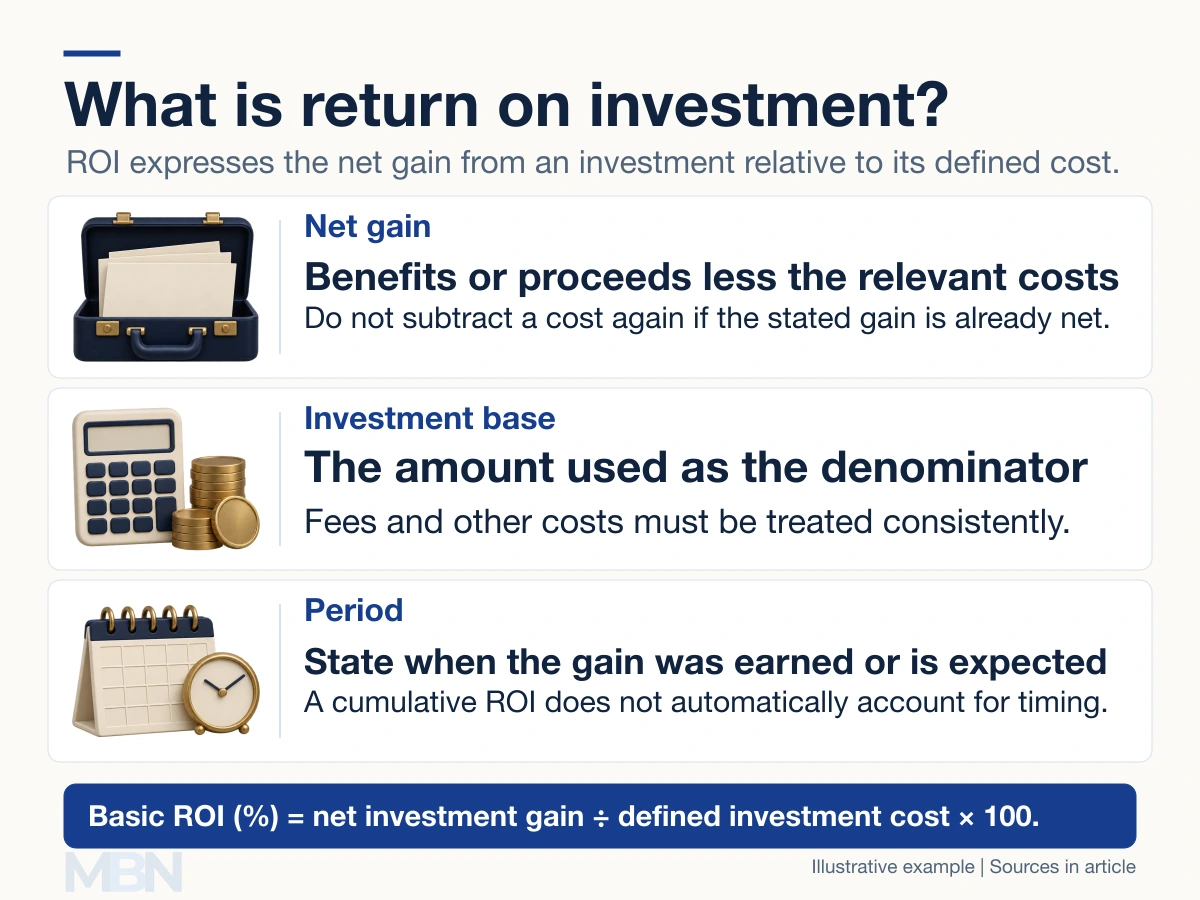
What goes into the calculation?
Net gain means the relevant benefits or proceeds minus the relevant costs. FINRA explains that investment returns can include income as well as changes in asset value, and that fees affect the result.
The definition must be consistent. BDC also describes a business-accounting ROI convention using earnings after tax divided by invested capital. That is not automatically identical to the return from buying and selling an asset. The numerator, denominator and period should always be stated.
A $500,000 investment example
Suppose a fictional investment costs $500,000 and later returns total proceeds of $1 million, with no other costs or cash flows. The net gain is $500,000, giving an ROI of $500,000 ÷ $500,000 × 100 = 100%.
If the $1 million figure instead means net investment gain after the original cost has already been deducted, the calculation is $1 million ÷ $500,000 = 200%. Calling proceeds “profit” and then subtracting the investment again confuses two different inputs.
Total ROI and annualized return
Earning 100% in one year differs from earning 100% over four years. FINRA distinguishes the amount of return from the rate earned over a particular period.
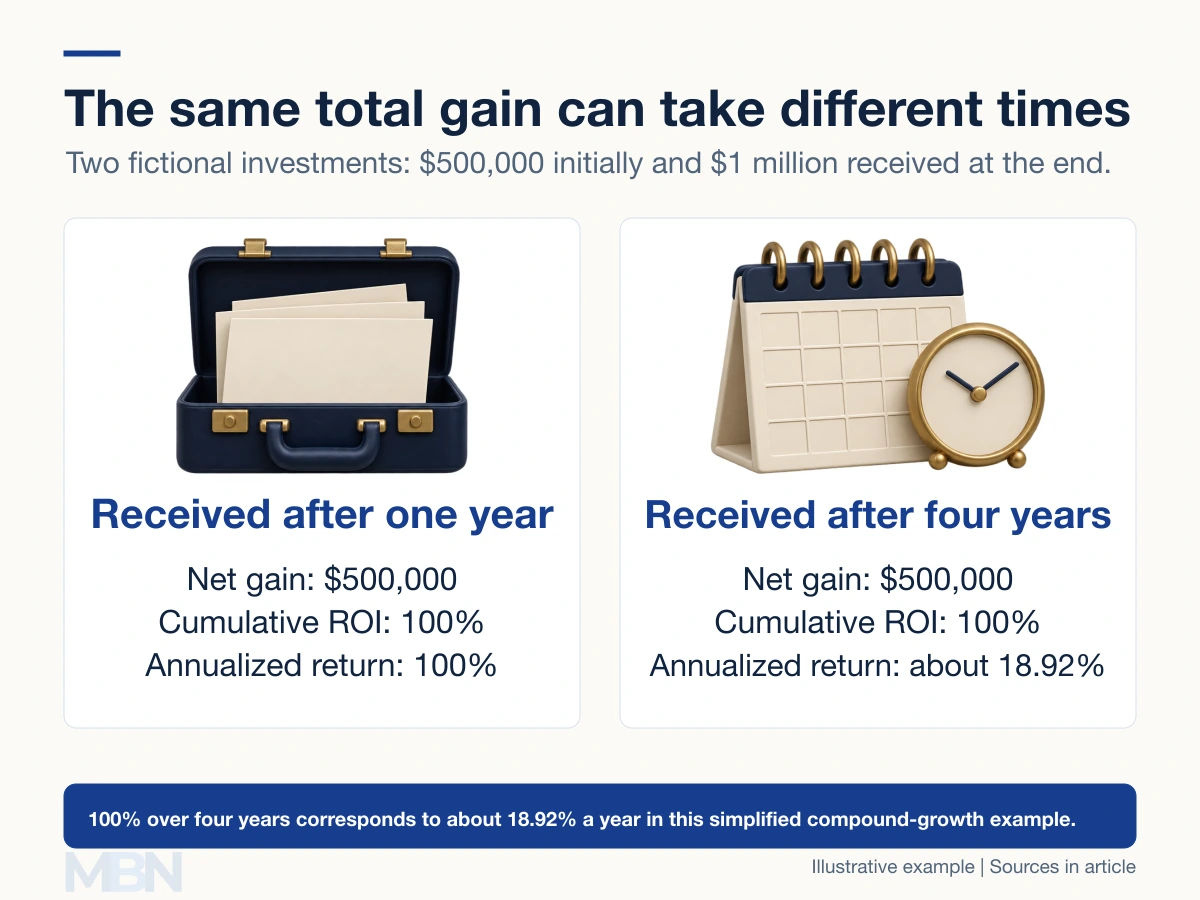
With $500,000 paid initially and $1 million received exactly four years later, and no interim flows, the equivalent compound annual return is (1,000,000 ÷ 500,000)1/4 − 1, or about 18.92%. Simply dividing 100% by four would not give that compound rate.
What do positive and negative results mean?
A positive ROI means a net gain under the stated definition. Zero means no net gain or loss, and a negative ROI means a loss. A positive nominal result can still fail to compensate for inflation, risk or the return available from another use of the funds.
Which questions need other measures?
Net present value, or NPV, discounts future cash flows to a present value. Internal rate of return, or IRR, is a discount rate that makes NPV zero. These calculations explicitly use cash-flow timing and answer different questions from a basic cumulative ROI.
Forecast ROI remains dependent on assumptions; measured historical ROI concerns outcomes already observed or valued. Nonfinancial benefits can be reported separately, but adding them to a financial ROI requires a clear, supportable method of assigning monetary values.
Last checked and updated on November 4, 2026 by the MBN editorial team.