
Senior debt ranks ahead of specified junior or subordinated debt in the borrower’s capital structure. Its priority can improve a creditor’s claim to recovery, but it does not guarantee that the debt will be repaid in full.
Companies can borrow through senior loans, revolving credit facilities or bonds. Banks, funds and bond investors can provide the money. Senior status does not require a particular lender, fixed interest rate or repayment schedule.
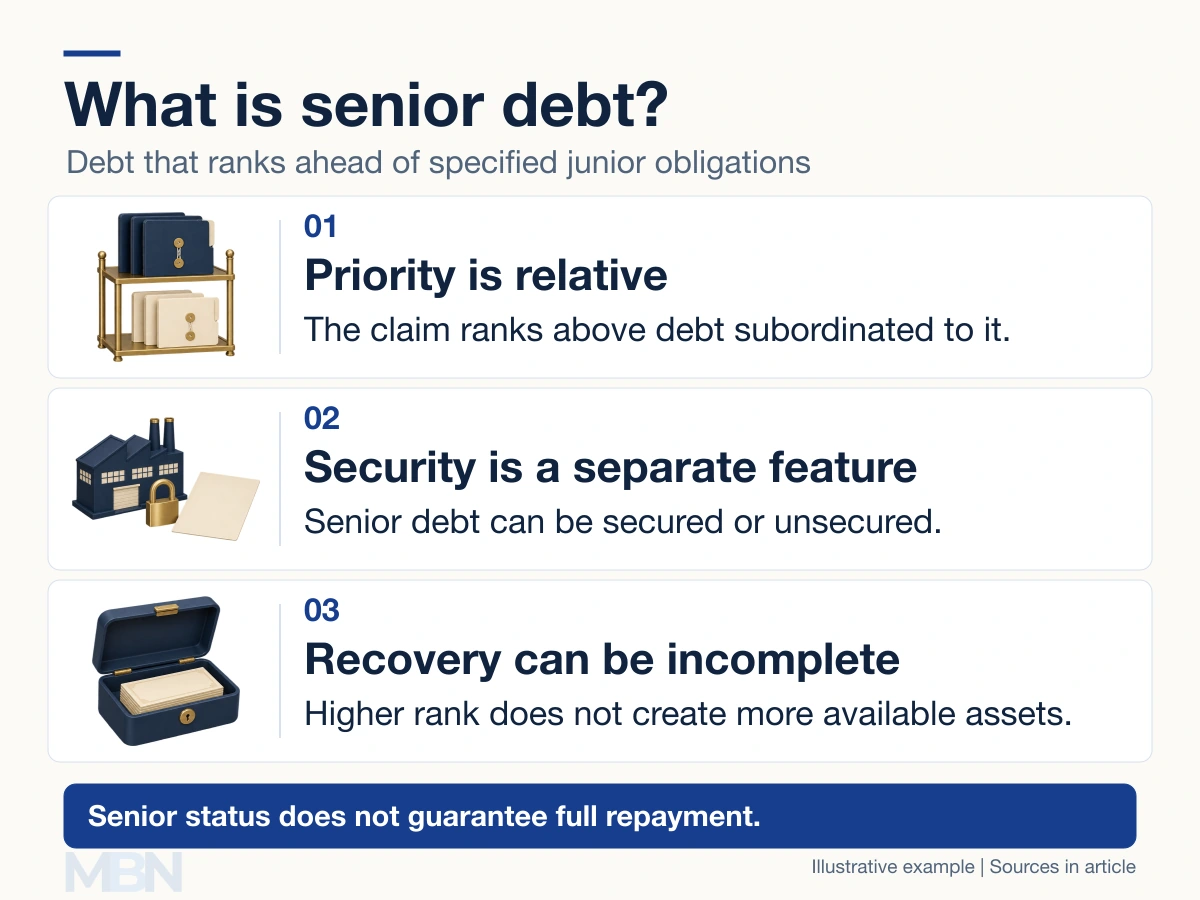
Senior and secured mean different things
Seniority describes ranking. Security describes rights over pledged collateral, such as property, equipment or receivables. Debt can therefore be senior secured or senior unsecured.
The SEC’s corporate-bond guide distinguishes secured bonds, senior unsecured bonds and subordinated bonds. A senior unsecured lender has no specifically pledged collateral merely because its debt is called senior.
A lien is a legal claim against specified property. Enforcement is subject to the documents, competing rights and applicable law. Collateral can be worth less than the debt, so a security interest does not eliminate credit losses.
What happens if there is too little money?
Assume a simplified case in which $80,000 is available for two claims after all other relevant claims and costs have been resolved. One creditor is owed $100,000 of senior debt; another is owed $50,000 fully subordinated to that debt.
Under the assumed ranking, the senior creditor receives the available $80,000, recovering 80% and losing $20,000. The junior creditor receives nothing. Priority has allocated a limited pool; it has not created enough money to pay everyone.
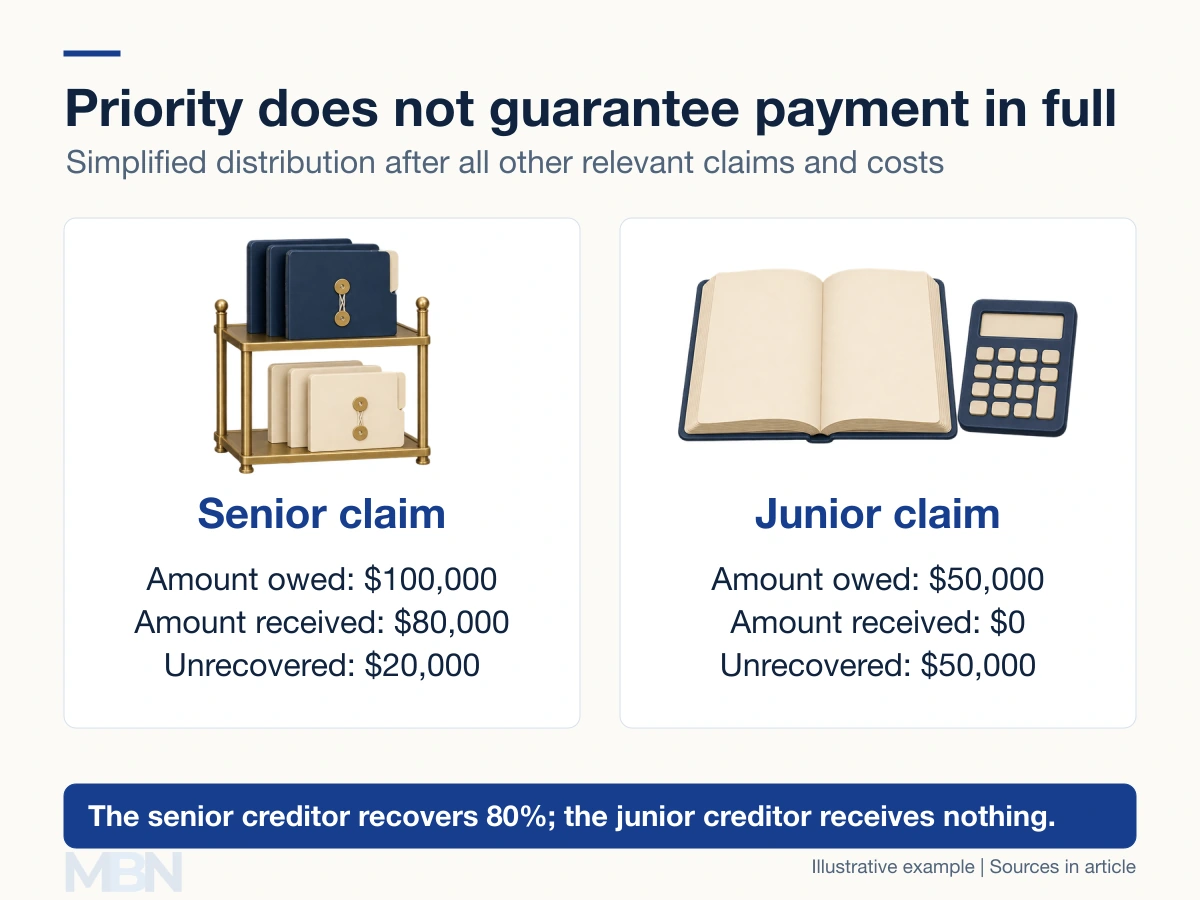
This illustration is not a complete bankruptcy waterfall. Real cases can involve multiple creditors sharing a rank, collateral-specific proceeds, guarantees, expenses and disputed claims.
Insolvency law also affects priority
In the United States, Bankruptcy Code section 506 generally separates an allowed claim into secured and unsecured portions according to the relevant collateral value, subject to the statutory rules. An undersecured lender can therefore have an unsecured shortfall.
Section 507 gives statutory priority to specified expenses and claims. The word “senior” in a loan title does not override the applicable legal framework or mean that its holder comes before every other claimant. Other countries have different insolvency rules.
Bankruptcy does not always close the business
The US Courts’ Chapter 11 explanation describes reorganization in which a debtor commonly continues operating and proposes a plan for creditors. Filing for bankruptcy does not necessarily mean immediate liquidation or the end of all operations.
Why senior borrowing terms differ
Subordination can make junior debt riskier than senior debt of the same borrower, all else equal. The actual return and risk also depend on repayment capacity, collateral quality, maturity and market pricing.
Loan covenants are contractual conditions that may restrict additional borrowing or require financial tests. These are rights held by creditors, the parties owed money. The debtor is the borrower. The documents determine the protection actually provided.
Last checked and updated on November 6, 2026 by the MBN editorial team.