
A SWIFT code is the common name for a Business Identifier Code, or BIC. It identifies a business party, often a bank, in financial transactions and messaging. It does not identify an individual customer’s account.
BICs are standardized under ISO 9362, with Swift acting as the registration authority. Although “bank identifier code” remains familiar wording, the current expansion is Business Identifier Code.
How the code is structured
Swift’s standard description defines an eight-character business-party identifier: a four-character alphanumeric prefix, a two-letter country code and a two-character alphanumeric suffix.
An optional three-character branch identifier extends it to eleven characters. This can distinguish a location, department, service or unit of the same business party. The formats are therefore eight or eleven characters, rather than any length from eight through eleven.
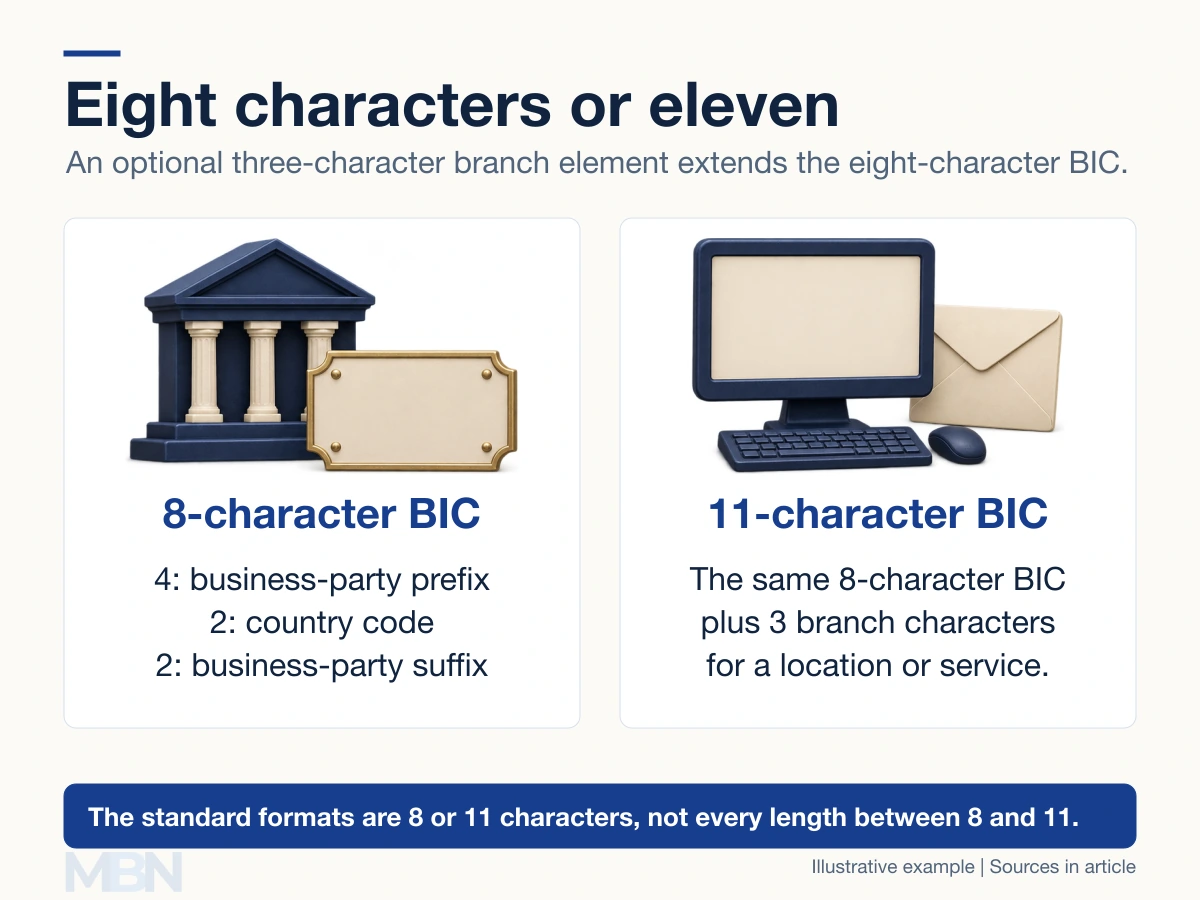
The suffix is often called a location code in banking explanations, but it should not be read as a universal town abbreviation. Likewise, a branch element can identify a service or unit rather than a customer-facing branch. Swift’s BIC FAQ explains its wider business-identification role.
BIC, IBAN and routing number
A BIC identifies the institution or business party. An International Bank Account Number, or IBAN, identifies a specific account in countries using that standard. A domestic clearing identifier, such as a US routing number, serves a different payment-system function.
For example, knowing which bank receives a transfer does not tell that bank which customer should receive it. The payment instruction also needs the relevant account and beneficiary information, according to the provider’s requirements.
Both IBAN and BIC are not universally required for every transfer involving Europe. The European Payments Council explains the IBAN-only rule for SEPA euro credit transfers and direct debits: customers are not required to supply a separate BIC where that rule applies. Other currencies and payment routes can require different details.
What Swift does in a payment
Swift describes itself as a secure messaging system. Institutions exchange instructions through it, while banks and other providers arrange the actual transfer and settlement of funds. A payment can involve intermediary banks, currency conversion and compliance checks.
A valid BIC alone does not establish that an account exists, that a beneficiary owns it or that a payment is safe. Nor does every entity with a BIC connect directly to Swift. Identification and network access are separate matters.
Swift’s cross-border ISO 20022 migration ended its coexistence period for covered financial-institution payment instructions on November 22, 2025. ISO 20022 governs message structure and data; it does not turn a BIC into an account number, and its migration timetable does not apply to every Swift message type.
Bank mergers, organizational changes and payment-specific routing can make historical code lists unsuitable for an actual transfer. Receiving-bank instructions and current provider validation determine which identifiers belong in a particular payment.
Last checked and updated on November 11, 2026 by the MBN editorial team.