
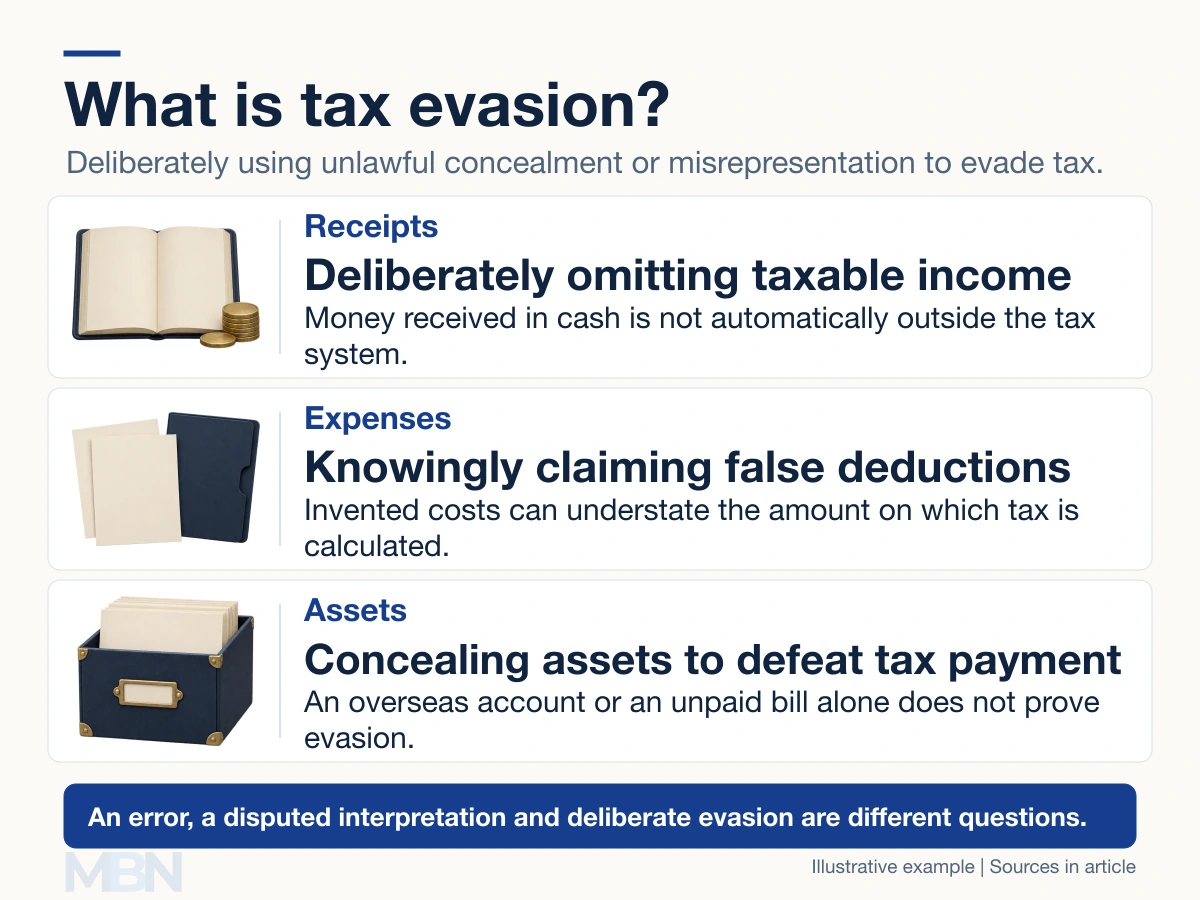
Tax evasion involves deliberately breaking the law to evade tax, for example by concealing taxable income, submitting false information or hiding assets to defeat payment. An unpaid bill or an incorrect return does not, by itself, establish criminal evasion.
The UK’s HM Revenue & Customs defines evasion as illegal activity involving deliberate concealment or misrepresentation. In the US, the relevant authority is the Internal Revenue Service, or IRS, rather than the “Inland Revenue Service”.
Intention and conduct matter
A genuine calculation mistake, careless record-keeping, inability to pay and deliberate deception can have different legal consequences. Tax authorities must consider the facts and the requirements of the applicable law.
For US federal tax evasion under section 7201, the IRS criminal investigation manual explains the need for an affirmative attempt and willfulness. It distinguishes this offence from merely failing to pay. Willful failure to file or pay can still be a separate offence.
Penalties may include additional tax, interest, financial sanctions and, following criminal conviction, imprisonment. There is no single worldwide penalty or automatic sentence for all cases.
A simple example
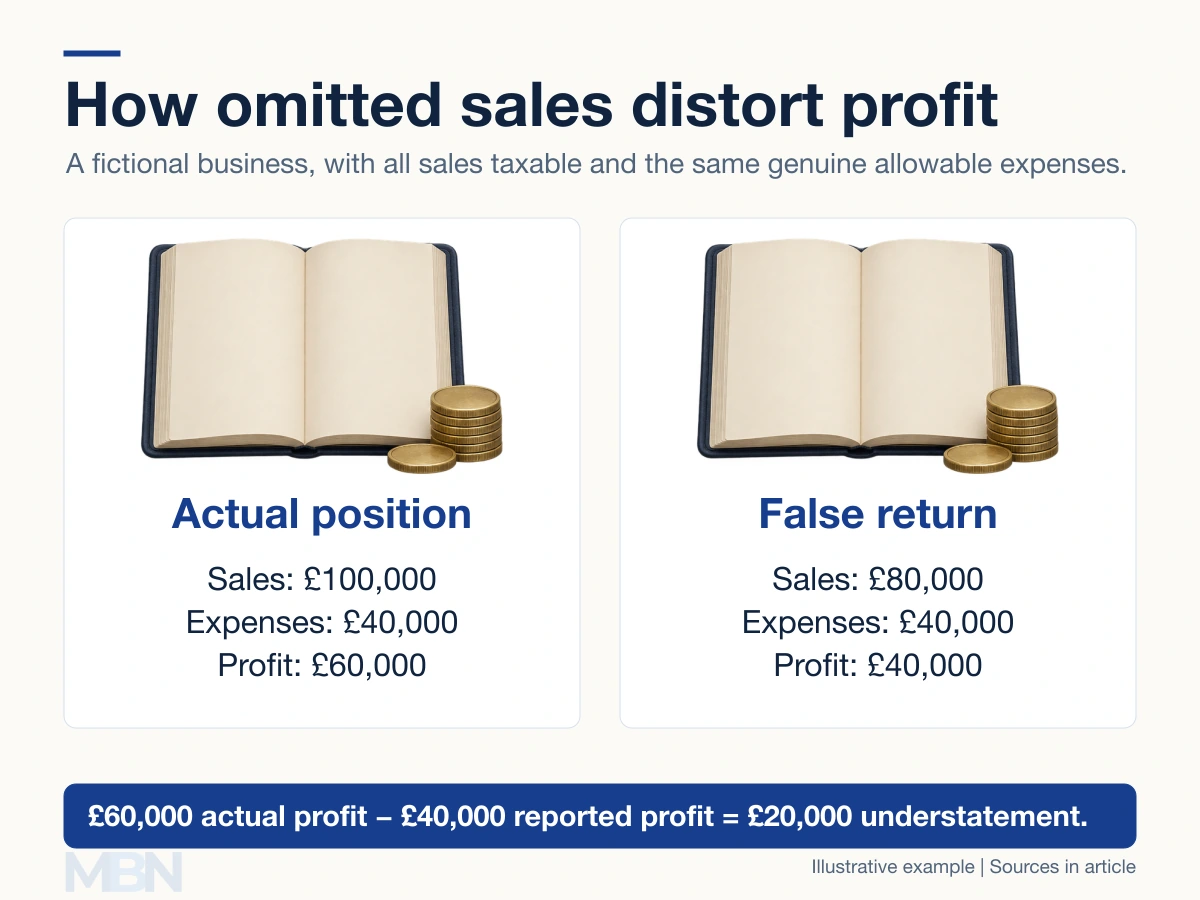
Suppose a fictional business has £100,000 of taxable sales and £40,000 of genuine allowable expenses. Its profit before any other tax adjustments is £60,000.
If its owner knowingly conceals £20,000 of those sales and reports £80,000 instead, the same expenses produce a reported profit of £40,000. The understatement is £20,000. The tax shortfall depends on the relevant rules and rates; it is not automatically the entire amount of omitted sales.
Receiving cash, operating internationally or holding an overseas account is not itself proof of tax evasion. The question is whether required information and tax have been unlawfully concealed or misrepresented.
Evasion, avoidance and ordinary tax relief
Claiming a relief that the law provides, while meeting its conditions, differs from knowingly submitting false information. The word avoidance needs care because authorities do not use it simply as a synonym for routine tax planning.
HMRC describes avoidance as arrangements seeking a tax advantage Parliament did not intend. It warns that many schemes fail, leaving users with tax, interest and potentially penalties. Calling every avoidance arrangement “perfectly legal” can therefore mislead readers about whether the claimed saving will stand.
The tax gap is broader than criminal evasion
The IRS projects a $696 billion gross tax gap for tax year 2022. This is the difference between true tax liability and tax paid voluntarily and on time, covering non-filing, under-reporting and underpayment. It is a projection for that year, not a measured current-year criminal-evasion total.
HMRC’s behavioural breakdown likewise separates evasion from error, failure to take reasonable care, non-payment and other categories. Estimates using different definitions, periods and methods should not be treated as a comparable ranking of countries.
Reporting concerns
Current official routes include the IRS reporting service, including Form 3949-A, HMRC’s tax-fraud reporting service, the Canada Revenue Agency’s Leads Program and the Australian Taxation Office’s reporting guidance. Their requirements differ.
HMRC says not to investigate further or tell others that a report is being made. Its current guidance directs people to the online service or hotline and says not to send reports by post.
Last checked and updated on November 4, 2026 by the MBN editorial team.