
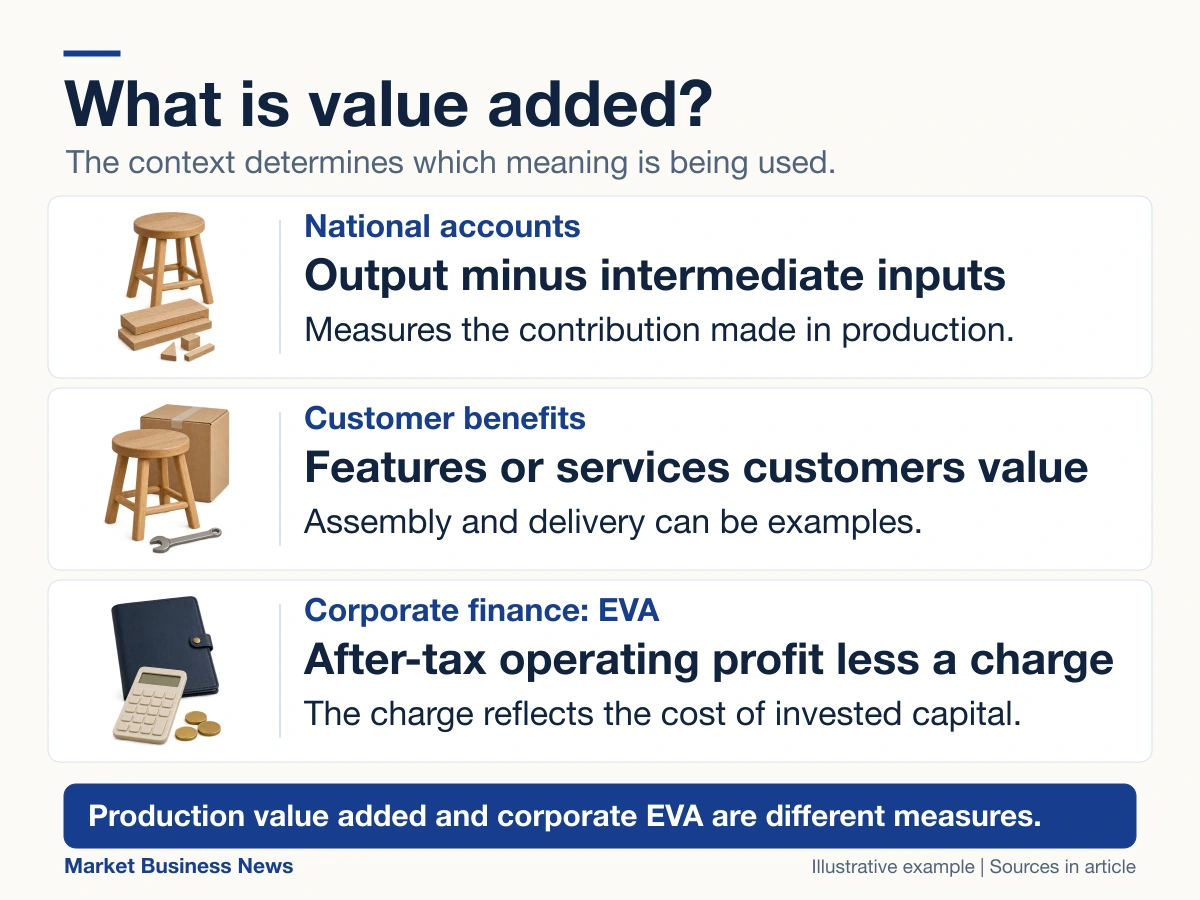
In national accounts, value added is gross output minus the goods and services used up in producing it. Businesses also use the term for benefits customers value. Economic value added, or EVA, is a separate corporate performance measure that deducts a capital charge from operating profit after tax.
These meanings answer different questions: how much production contributes to the economy, what a customer gains, and whether a business earns more than its required return on capital.
Value added in national accounts
The US Bureau of Economic Analysis distinguishes gross output from value added. Gross output measures production, including goods and services that other producers use as inputs. Intermediate inputs include materials, energy and purchased services consumed in production.
Subtracting those intermediate inputs leaves the producer’s value added. Adding value added across producers avoids counting the same intermediate production repeatedly, as would happen if all sales along a supply chain were added together.
Employees’ compensation is part of value added, rather than an intermediate input deducted from output. The BEA’s industry-accounts guide also identifies production taxes less subsidies and gross operating surplus among its components. Gross value added therefore includes more than a firm’s profit.
A hypothetical production example
Suppose a workshop produces a stool with an output value of US$120. The timber, energy and outside services used to make it cost US$50 in total. For this simplified example, all output is sold and there are no inventory changes or tax adjustments.
The workshop’s value added is US$70: US$120 minus US$50. If employees receive US$30 for their work, that pay is included within the US$70. It is not deducted again when calculating value added.
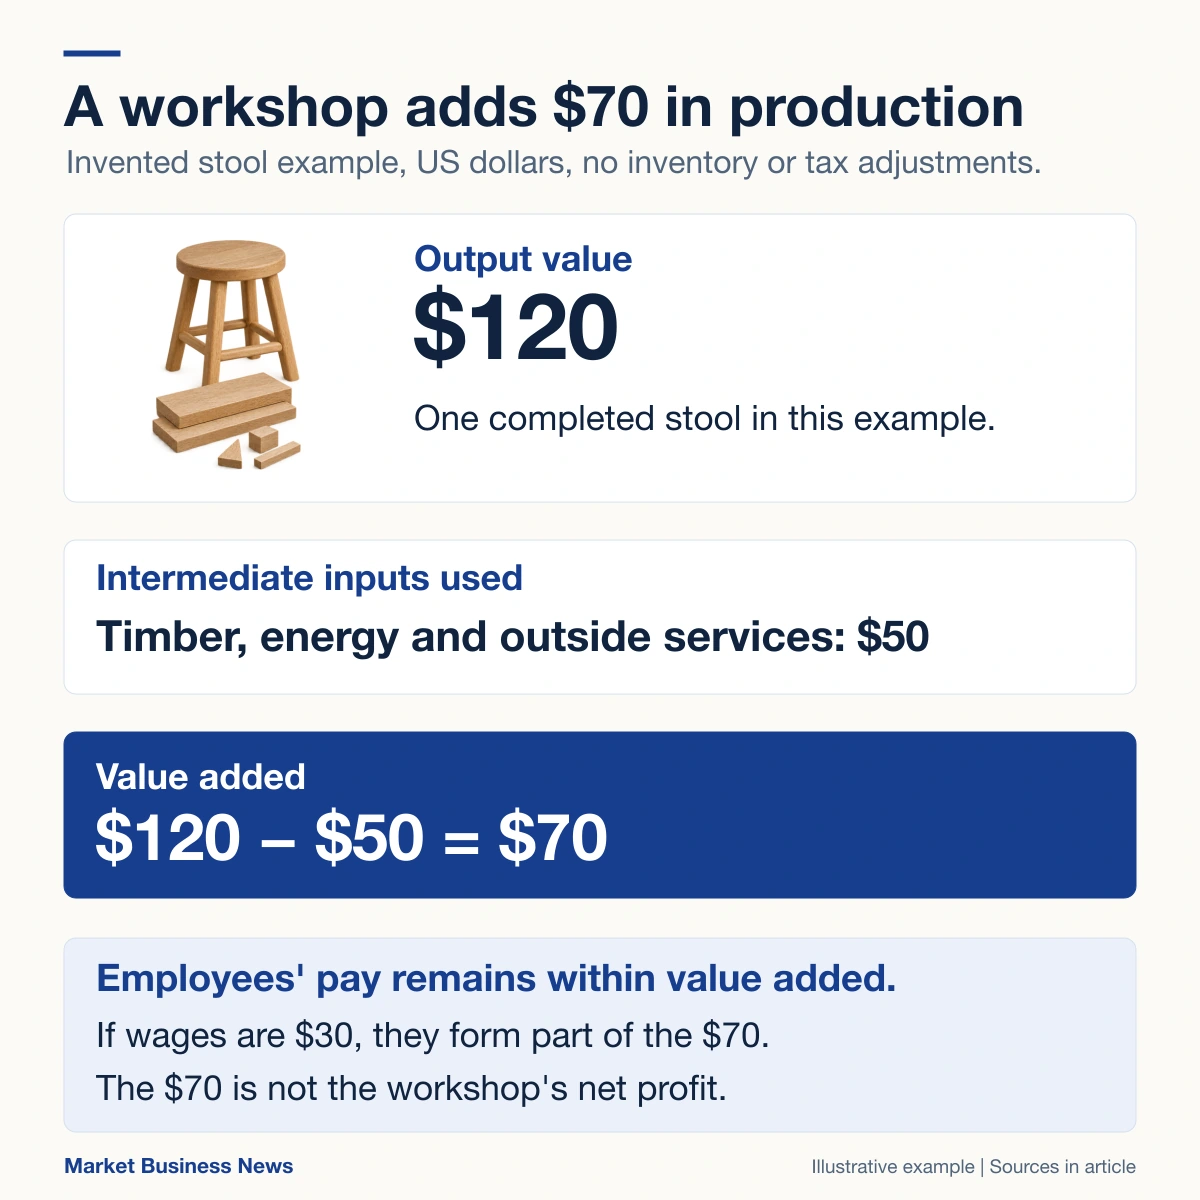
The US$70 is not the workshop’s net profit. Wages and other costs still affect profit. Gross income, gross profit, net profit and national-accounts value added are not interchangeable labels.
Economic value added in corporate finance
EVA measures operating profit after tax less a charge for the capital invested in the business. The capital charge represents the required return of the providers of debt and equity. It is not simply the interest the company paid.
In Aswath Damodaran’s explanation at NYU Stern, the calculation is after-tax operating income minus invested capital multiplied by the cost-of-capital rate. Reported accounting figures may need adjustments for this analysis.
In a separate hypothetical annual example, operating profit after tax is US$20,000, invested capital is US$150,000 and the assumed annual cost of capital is 8%. The capital charge is US$12,000, leaving EVA of US$8,000.
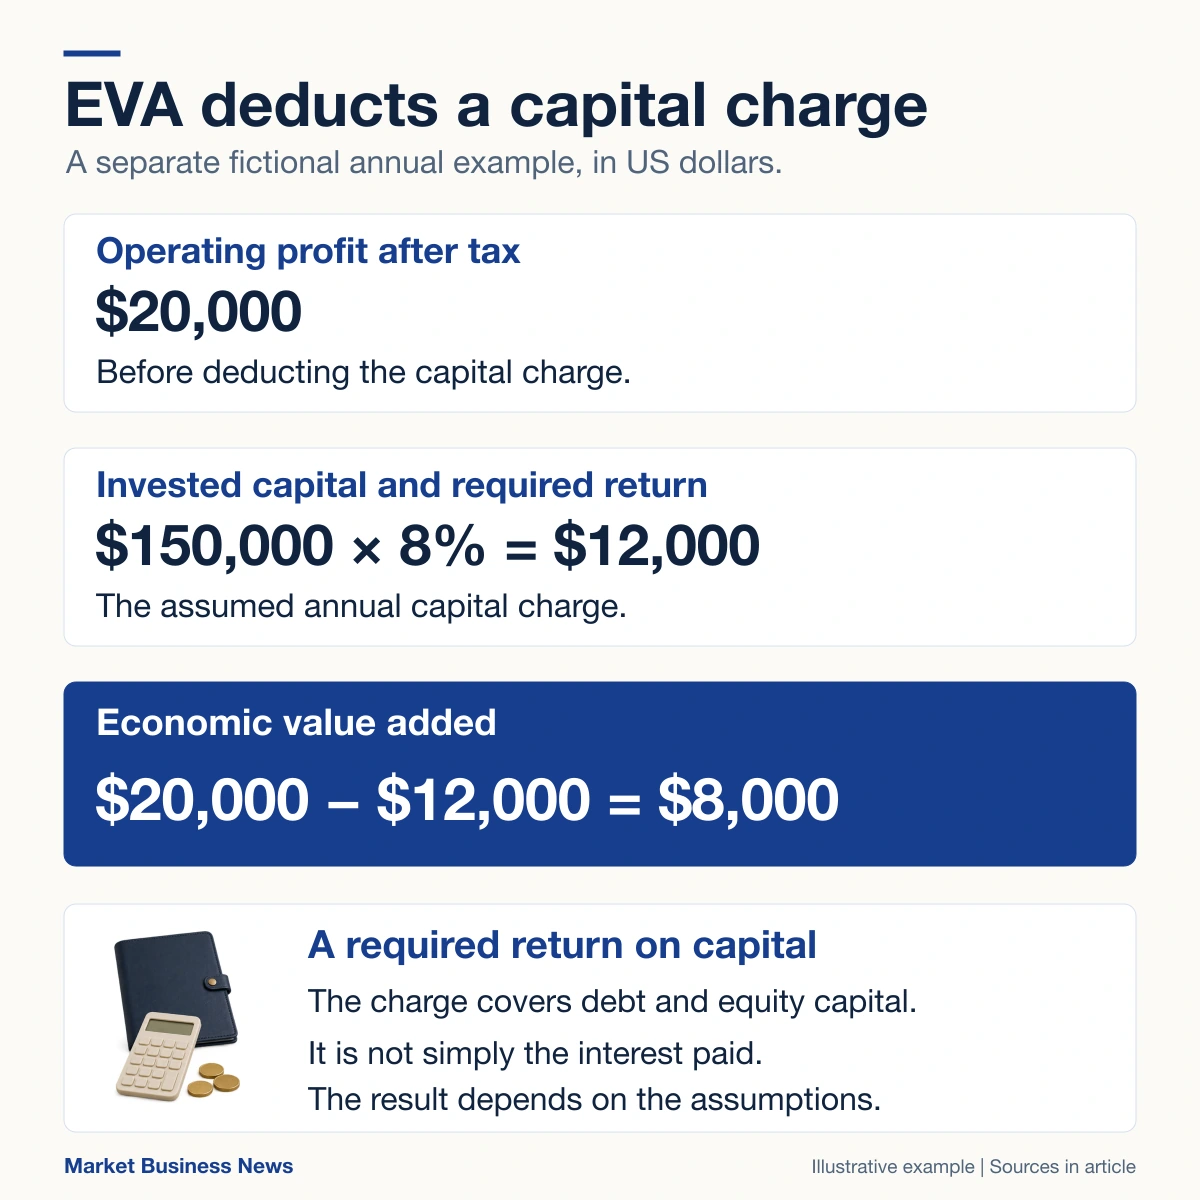
The positive result means earnings exceed the assumed capital charge in this calculation. It depends on the profit, capital and required-return estimates used. It is separate from the contribution-to-GDP measure above.
Customer benefits and process work
In marketing, added value describes benefits that make an offer more attractive to a customer. A hypothetical furniture seller might include assembly and delivery with a stool. Whether those services are valuable depends on the customer’s needs, while their cost affects the seller’s margin.
Process analysis uses a related customer-focused meaning. The Lean Enterprise Institute distinguishes work the customer values from work that adds cost without such a benefit. Fabrication can create value; correcting an avoidable defect is rework.
Some activities remain necessary even when they do not transform the product in a way the customer values. Safety inspections are one example. These process categories describe the activity being performed, rather than the national-accounts subtraction of intermediate inputs.
Last checked and updated on November 2, 2026 by the MBN editorial team.