
Venture capital, or VC, is investment in businesses with substantial growth potential, commonly through equity or instruments that can become equity. It is associated with young companies facing significant uncertainty and is generally considered a form of private equity.
Private equity generally refers to ownership investment in companies outside public stock markets. A loan to a private company is not automatically a private-equity investment. Venture capital differs from venture debt, which involves borrowing and repayment obligations, even when the two are used by the same business.
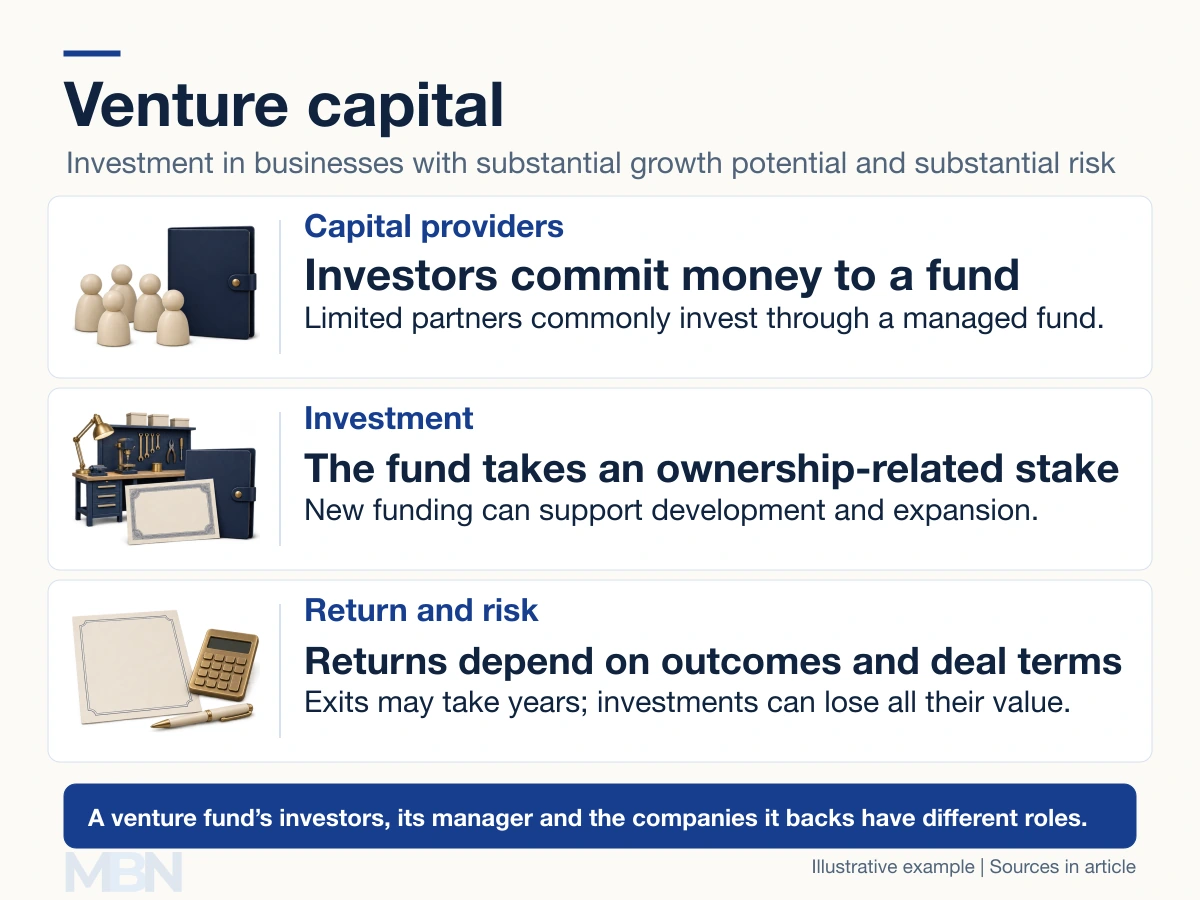
Who provides the money?
A venture-capital firm commonly manages a fund backed by investors such as institutions, family offices and individuals. These fund investors are often limited partners, while a manager or general partner selects and oversees investments.
The SEC distinguishes venture-capital funds from other private funds. The fund’s investors and the startup receiving investment are different parts of the structure. Investing in a company does not automatically make the venture investor a limited partner in that company.
Corporate venture investors can invest from a corporate balance sheet or a separate vehicle. An angel commonly invests personal capital, while a venture firm typically manages a wider pool. Structures and investment mandates vary.
How funding supports a company
Capital can finance research, product development, recruitment, market entry or expansion before operating cash flow covers the costs. The British Business Bank explains venture capital’s growth focus.
Investors assess the team, market, product, competition, finances and potential route to a return. They may provide expertise and introductions or negotiate a board role, but useful support and commercial success are not guaranteed.
Rounds are often described as pre-seed, seed, Series A and later series. Those labels do not impose one universal sequence, funding amount or profitability requirement. A company can raise another round, remain private, be sold, go public or fail.
Ownership and contractual terms
New shares can dilute existing owners. Voting rights, board composition, investor consent rights and preferred-share terms can matter as much as the headline percentage.
Unlike a standard loan, ordinary equity does not normally require scheduled principal and interest payments. However, preferred or convertible instruments can contain special rights, and some arrangements include redemption provisions. The actual agreement determines the obligations. The National Venture Capital Association publishes model financing documents illustrating how share rights and investor protections are specified.
A simplified liquidation-preference example
Suppose an investor pays $2 million for 20% of a company’s shares on an as-converted basis. Its preferred shares have a 1× nonparticipating liquidation preference. Under this simplified arrangement, it receives the greater of its $2 million preference or the proceeds from converting to common shares, rather than both.
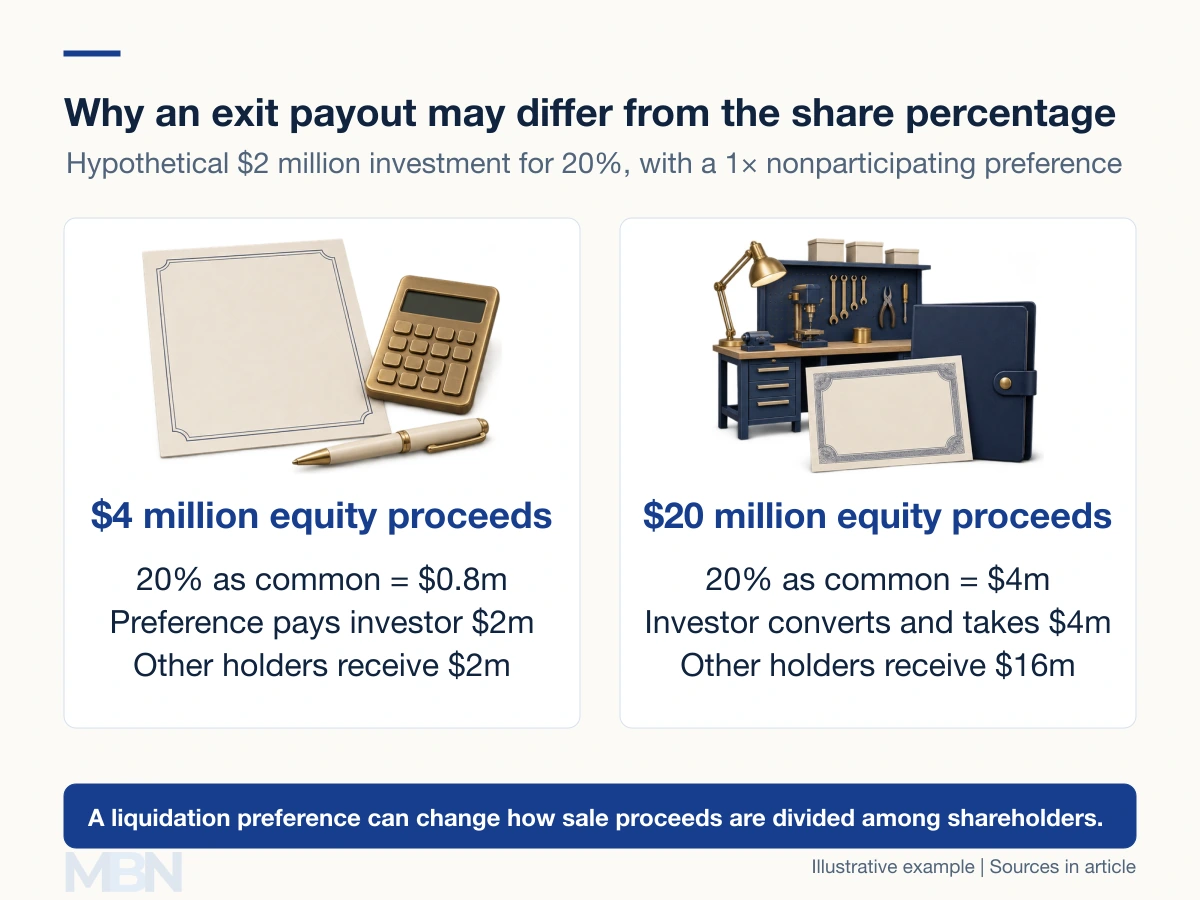
If equity proceeds from a sale are $4 million, 20% would be $800,000. The preference instead gives the investor $2 million, leaving $2 million for the others. With $20 million available, conversion produces $4 million for the investor and leaves $16 million.
The example assumes no other preferences, no adjustments and sufficient distributable proceeds after debt and costs. With less than $2 million available, the preference does not create missing money. Actual payout terms can be more complex.
Returns, exits and limits
Returns can come through acquisitions, share sales, public listings or other distributions. They depend on the price realized, dilution, rights, costs and timing, rather than accounting profit alone. Some companies fail, and private investments may remain illiquid for years.
The British Business Bank compares forms of equity finance, while the SEC’s funding roadmap explains capital-raising routes. Venture capital is one funding model; it is not the main source of money for every startup or suitable for every kind of business.
Last checked and updated on November 11, 2026 by the MBN editorial team.