
A zombie bank is a deeply impaired or economically insolvent bank that continues operating instead of being effectively restructured or resolved. Support, guarantees or supervisory forbearance may allow it to survive despite unresolved losses.
Forbearance means allowing a weak institution additional time or latitude rather than requiring immediate corrective action. “Zombie bank” is an analytical description, not a single legal status used identically in every country.
What makes the bank financially weak?
A bank can appear adequately capitalized if its assets are valued too generously or loan losses are not fully recognized. An IMF working paper on zombie banks explains that researchers use different measures of capital shortfalls and problem loans because the underlying condition can be difficult to observe.
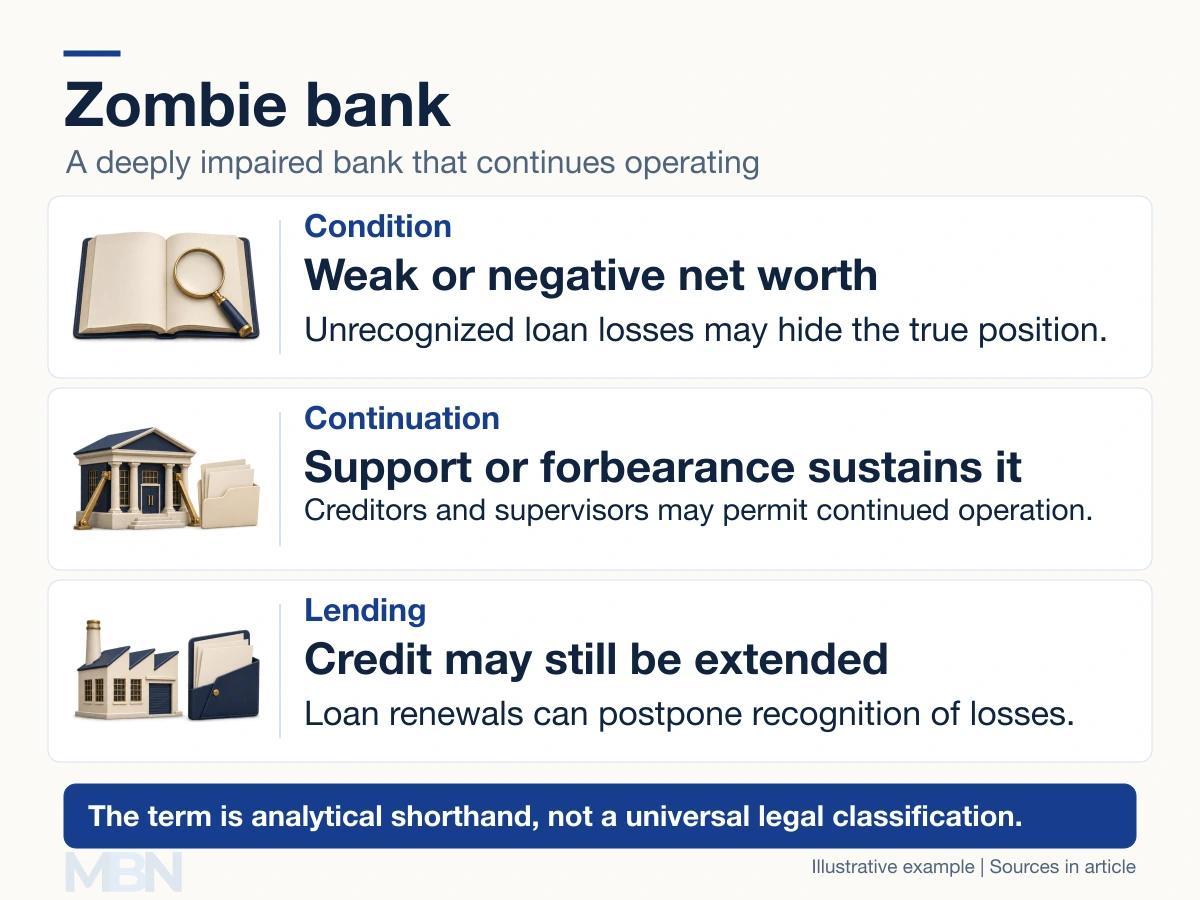
For example, a bank reports $110 million in assets against $100 million in liabilities. If realistic loan valuations reduce the assets to $90 million, its economic net worth is negative $10 million. That is different from simply having too little cash available today.
The Bank of England distinguishes capital from liquidity: capital absorbs losses, while liquidity enables timely payments. A solvent bank can face a temporary liquidity shortage. Receiving emergency liquidity or other public support does not, by itself, prove that a bank is a zombie.
Why it may continue lending
Zombie banks do not necessarily stop all lending. A weak bank may renew credit to a borrower that cannot repay, avoiding the immediate recognition of a loss that would damage the bank’s reported capital.
The Bank for International Settlements (BIS) discusses this incentive to evergreen loans. In a stylized example, a troubled factory’s loan falls due. Its bank extends the loan even though the factory’s underlying business remains unviable. The debt continues, but the repayment problem has not been solved.
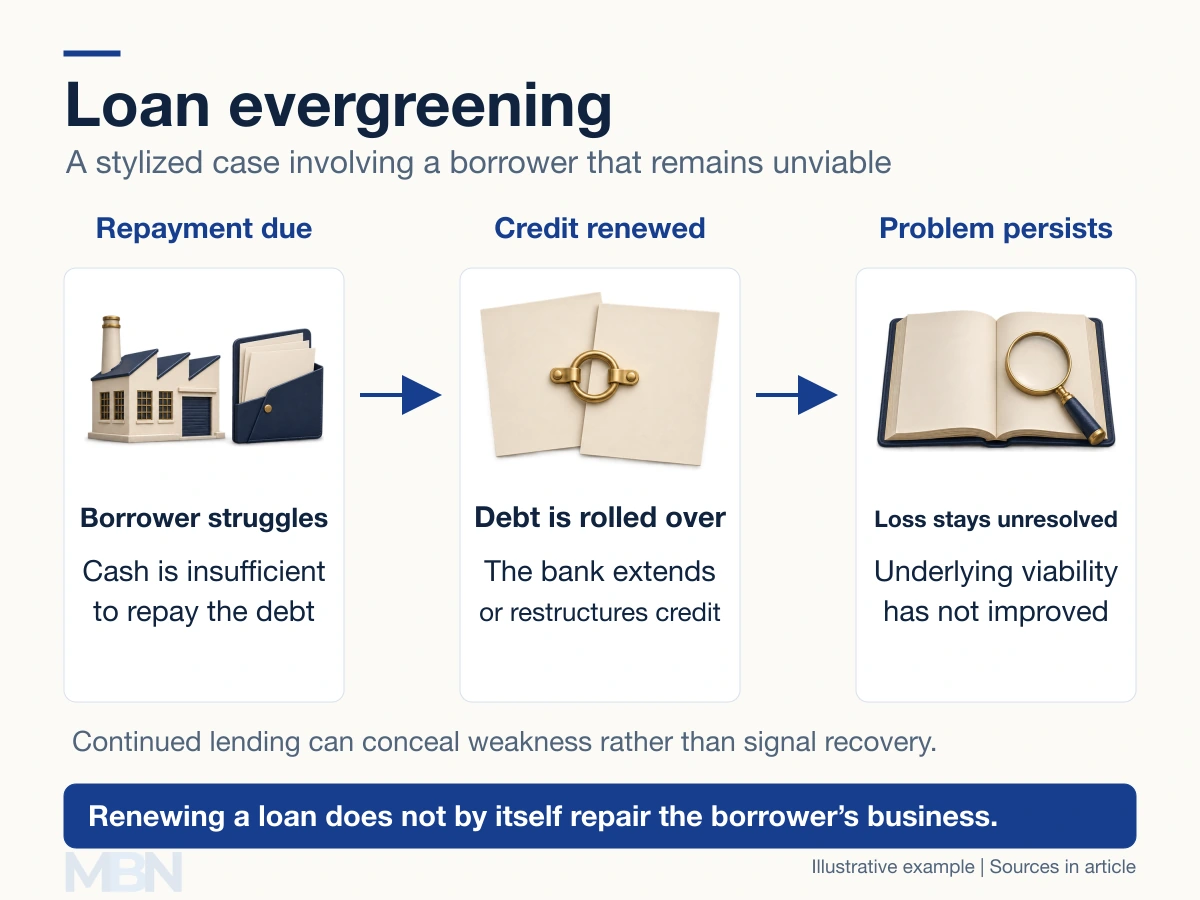
Not every extension is harmful. Restructuring can help a viable borrower recover. The concern is repeated support that masks an unresolved loss rather than restoring sustainable repayment.
Japan and the wider economic concern
Research by Ricardo Caballero, Takeo Hoshi and Anil Kashyap examines Japanese lending after the early-1990s asset-price collapse. The authors describe how loan restructuring kept credit flowing to otherwise insolvent borrowers and associate zombie-heavy industries with weaker restructuring and productivity.
This is more specific than saying banks simply absorbed deposits without lending, or that zombie banks alone caused Japan’s prolonged slowdown. Economic performance had multiple influences.
A bank and its borrowers are different
A zombie firm is a troubled nonfinancial business kept operating despite persistent financial weakness. A zombie bank is the impaired lender. The two can reinforce each other, but their definitions and identification tests differ.
Possible outcomes include loss recognition, recapitalization, restructuring or resolution. The costs and distribution of losses depend on the institution and legal framework; continued support is not proof of either a successful rescue or inevitable failure.
Last checked and updated on November 10, 2026 by the MBN editorial team.