
Digital currency is a broad term for monetary value recorded and transferred electronically. Depending on the context, it can include electronic bank money, central bank digital currency and payment-oriented cryptoassets. These forms do not have the same issuer, legal rights or risks.
“Digital money” is often used similarly. “Virtual currency” and “cryptoasset” can have narrower technical or legal meanings, so they should not be treated as exact synonyms in every setting.
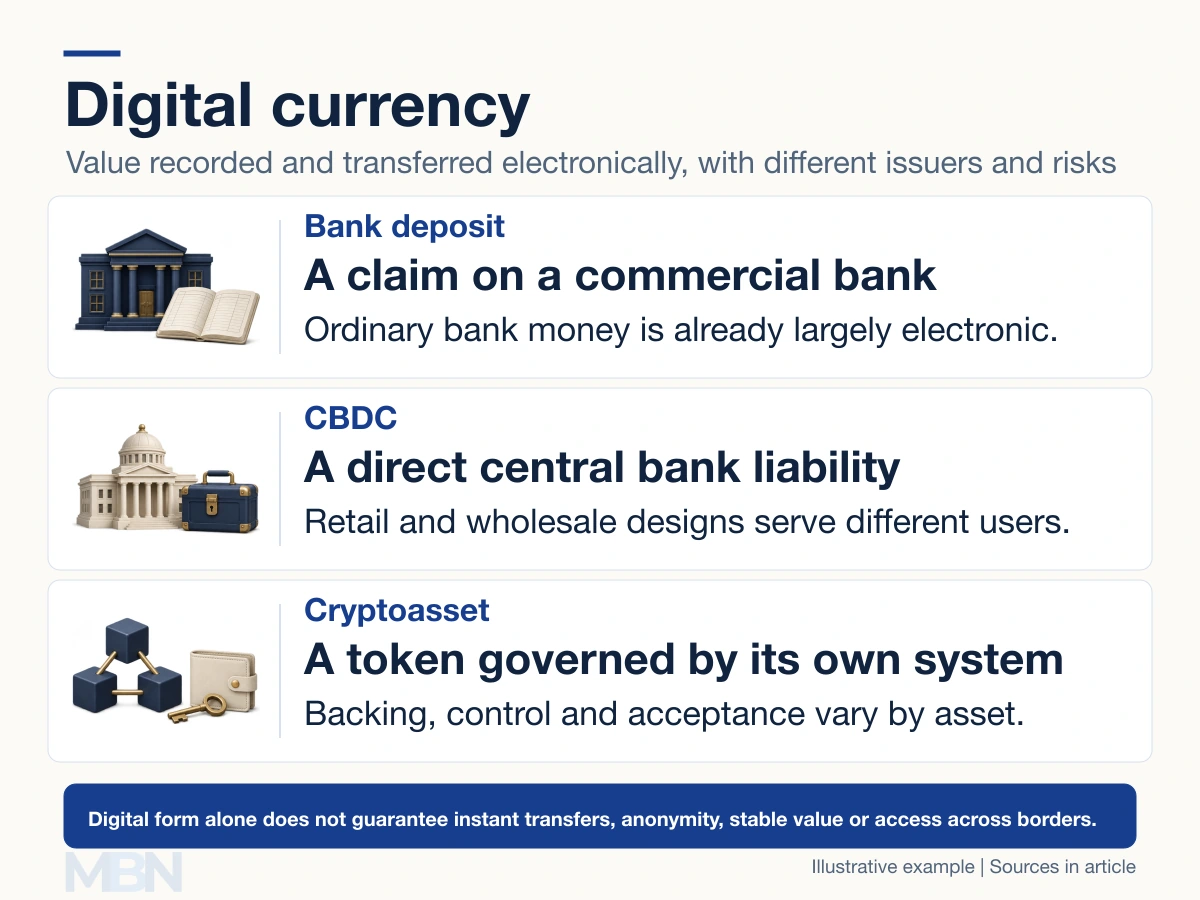
Who stands behind the balance?
An ordinary bank deposit is already digital when recorded electronically. It is a liability of a commercial bank, meaning the bank owes the depositor money. A bank app provides access to that claim rather than creating a separate currency.
A central bank digital currency, or CBDC, is a direct liability of a central bank. The Federal Reserve’s money and payments paper explains this distinction from privately issued money. Defining a CBDC does not mean every central bank has issued one.
The BIS distinguishes retail and wholesale CBDCs. Retail designs concern payments by the public; wholesale designs concern eligible financial institutions. Central bank reserves, which banks already use electronically, are different from a new retail currency for households.
Cryptoassets use cryptographic systems, often with distributed ledgers. Some, such as Bitcoin, have no central issuer promising redemption at a fixed national-currency value. Others have identifiable issuers and backing arrangements. Digital money does not have to use a blockchain: the BIS’s technology analysis examines different CBDC architectures.
Stablecoins and redemption
A stablecoin targets a reference value, commonly one unit of a national currency. Fiat-backed designs aim to support that value through reserve assets and redemption arrangements. The Bank of England explains their payment role and how they differ from ordinary cash and bank deposits.
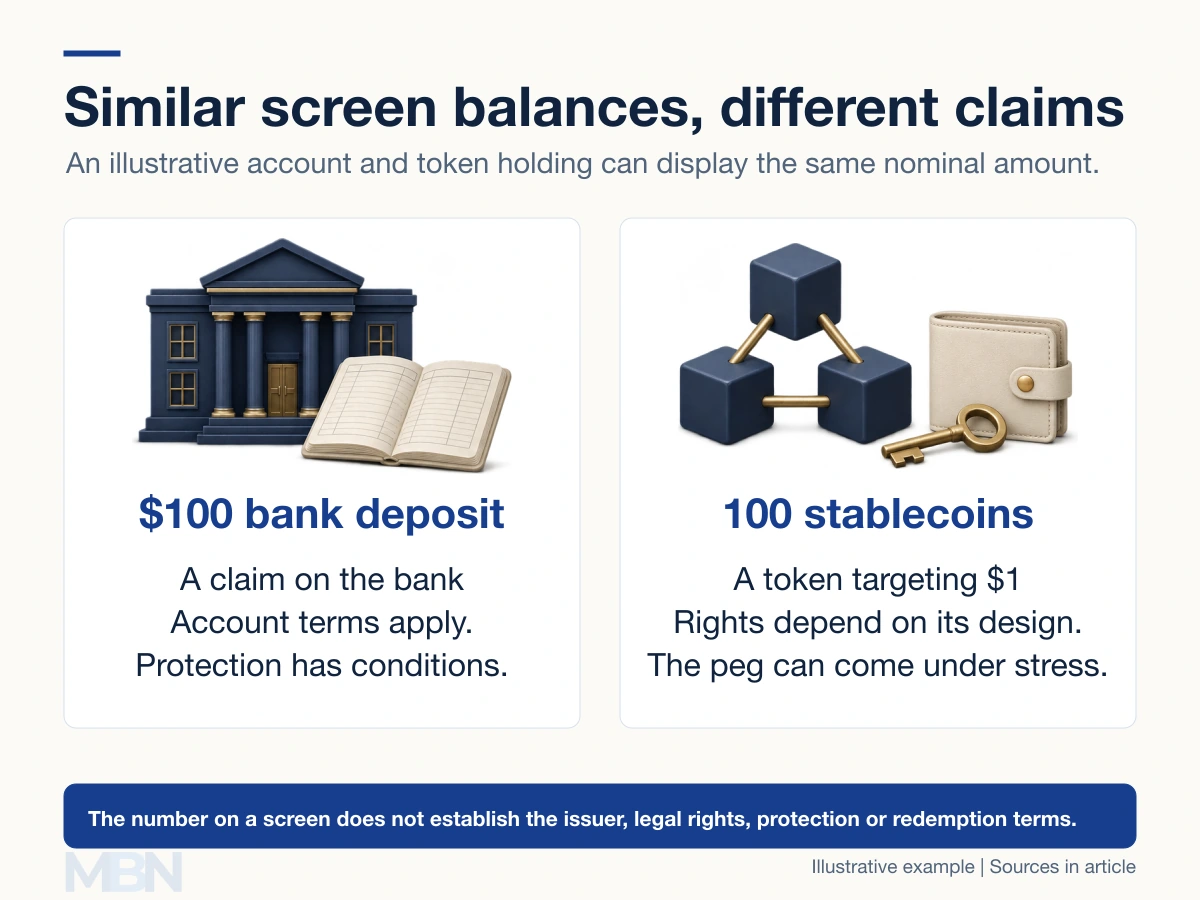
A token’s name or dollar reference does not by itself guarantee full backing, immediate redemption or deposit protection. The Bank of England’s regulatory definitions distinguish deposits, e-money, stablecoins and tokenized deposits.
For example, 100 tokens targeting $1 each have a $100 reference value. If they trade at $0.98, their market value is $98. Whether a holder can instead redeem them for $100 depends on enforceable rights, access, fees and the issuer’s ability to pay. This is an illustration, not a quote for a particular token.
Digital does not mean instant or borderless
A payment instruction can appear immediately while final settlement takes longer. Network capacity, confirmation rules, bank processing, compliance checks, currency conversion and local access restrictions can affect completion and cost.
Privacy also depends on design. A bank may identify its customers; a public blockchain can expose transaction histories even where addresses do not contain names. Cryptography can secure authorization without making users anonymous or eliminating scams.
Electronic systems introduce operational questions about lost credentials, outages, cyberattacks and recovery. A wallet may hold payment credentials or manage cryptographic keys. The useful comparison is therefore the underlying claim, transfer mechanism, acceptance and safeguards, rather than whether a balance appears on a phone.
Last checked and updated on November 11, 2026 by the MBN editorial team.