
An annuity is a series of payments at regular intervals. In personal finance, the term commonly means an insurance contract funded by a lump sum or contributions, with benefits and income determined by the contract’s terms. Payments need not always be fixed or continue for life.
The annuitant is the person whose life determines a life-contingent payment. The purchaser, annuitant and beneficiary can be different people.
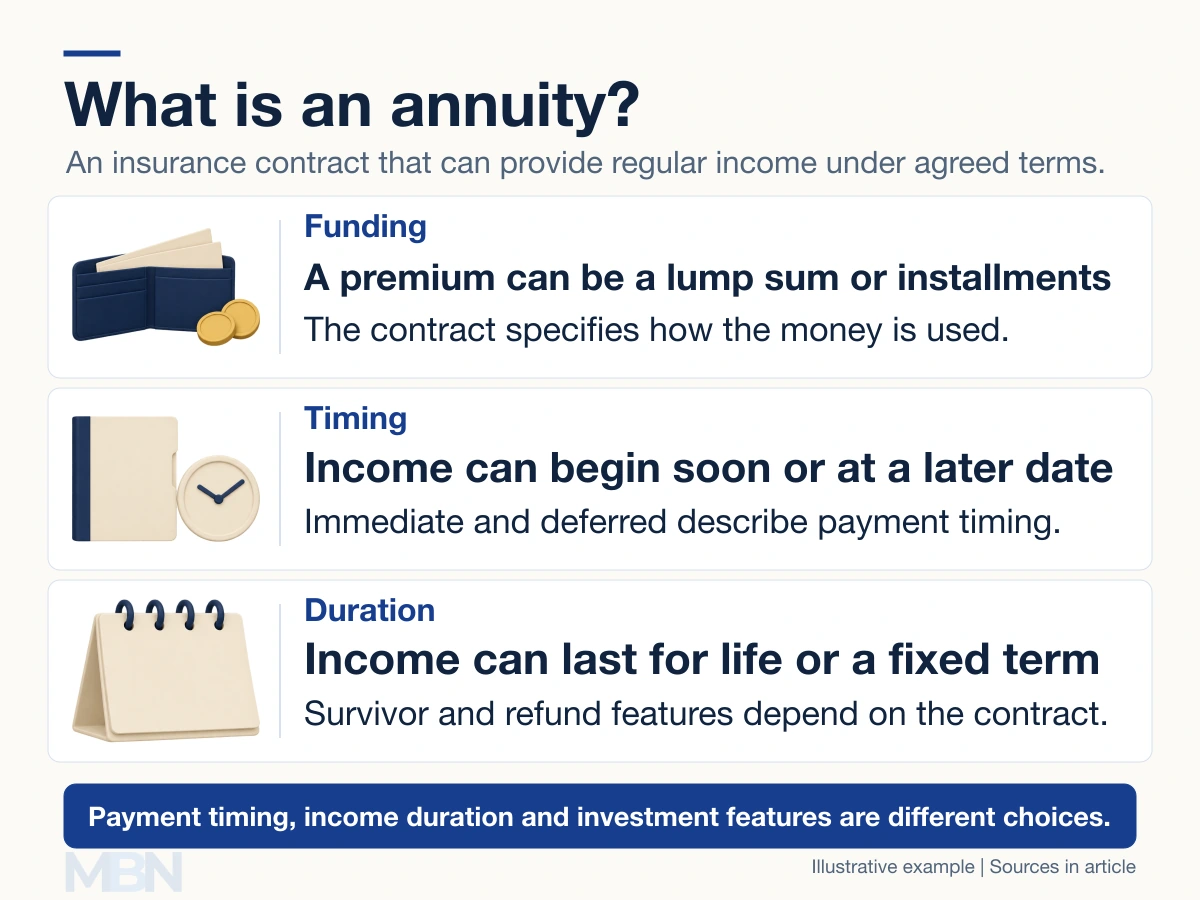
When does income start, and how long does it last?
The New York Department of Financial Services distinguishes immediate and deferred annuities. Immediate income generally starts within 12 months of purchase. A deferred contract schedules income for later and can have an accumulation phase before payments begin.
Duration is a separate feature. A lifetime annuity can continue while the covered person lives. A fixed-term annuity pays for an agreed period. Joint-and-survivor terms can continue income for a second covered person, sometimes at a reduced amount.
Refund and guaranteed-period benefits can provide payments after an early death. They are contractual features, not automatic rights for every heir.
What types of investment features exist?
Investor.gov distinguishes fixed, fixed indexed, registered index-linked and variable annuities in the US market. Fixed annuities credit interest under specified guarantees. Fixed indexed annuities link interest to an index through a formula, often limiting gains.
A registered index-linked annuity, or RILA, can lose value from adverse index performance, even when it has a buffer or loss limit. Variable annuities offer investment choices whose performance can increase or decrease account value.
Index-linked interest is not the same as owning the index. Fees, surrender charges and contract adjustments can affect the amount available. Optional income benefits may cost extra and impose conditions.
A lifetime-income example
Assume our fictional single-life level annuity exchanges a $100,000 premium for $500 each month. It has no survivor, refund or guaranteed-period feature. This is an illustration, not a current price quotation.
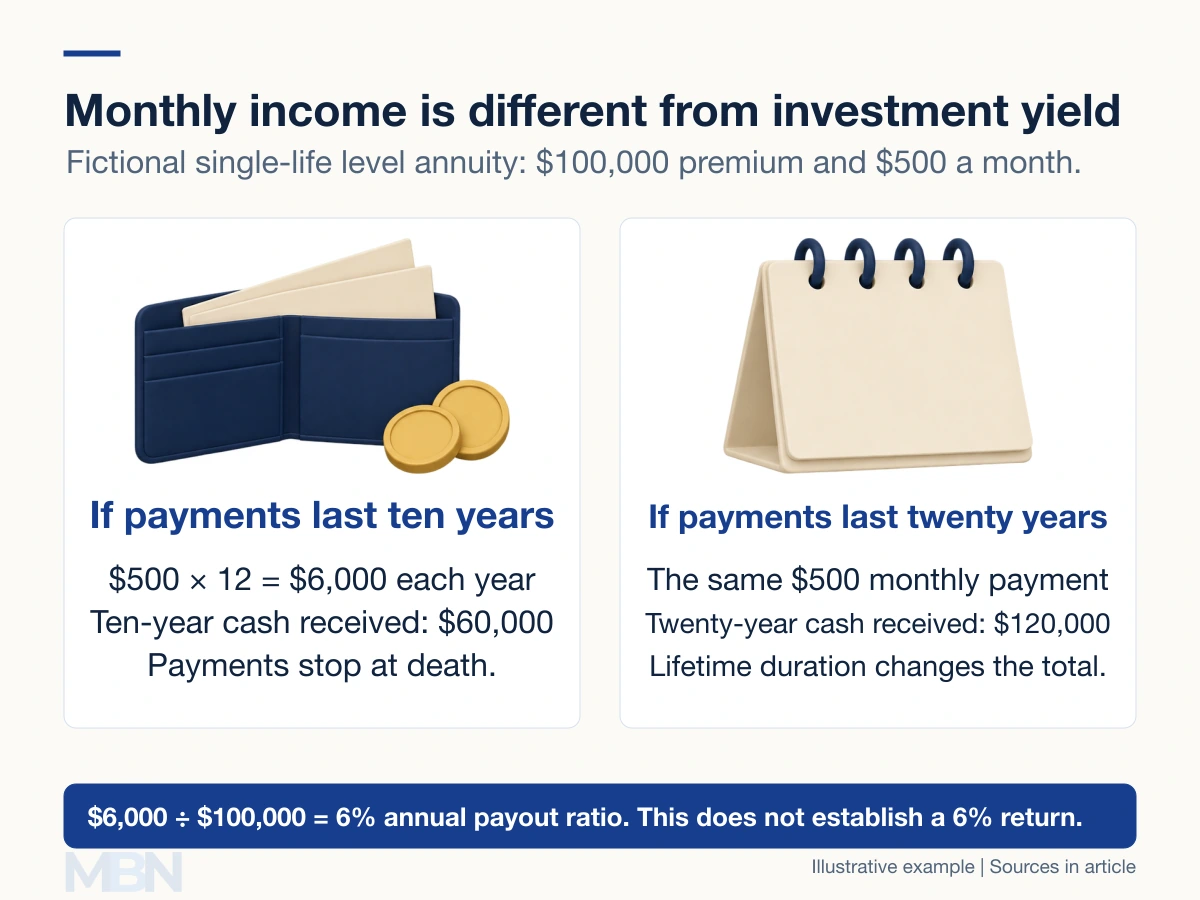
Ten years of payments total $60,000; twenty years total $120,000. The lifetime payment continues while the annuitant survives, subject to the insurer meeting its obligations. The eventual total is therefore unknown at purchase.
The $6,000 annual payment is 6% of the premium, but that payout ratio is not an investment yield. Payments include recovery of capital, and economic return depends on timing and duration.
What do guarantees and inflation mean?
Investor.gov cautions that an insurer’s promises depend on its financial strength and claims-paying ability. A guaranteed benefit also applies only under its stated conditions.
A level payment buys less when prices rise. MoneyHelper explains level and increasing annuity income. Increasing or inflation-linked benefits usually start with a lower payment than a comparable level-income option. Lifetime income can address longevity risk without automatically preserving purchasing power.
Are all annuity payments taxable?
Tax treatment depends on the country, funding and distribution. US tax deferral is not a worldwide rule, and not every dollar paid is necessarily taxable.
IRS Publication 939 explains that qualifying recovery of after-tax investment in a contract can be excluded from income. The remaining portion can be taxable. Retirement-plan funding, withdrawals before annuitization and other circumstances can involve different rules.
Last checked and updated on November 3, 2026 by the MBN editorial team.