
An asset class is a category of investments with similar economic characteristics. Common examples include equities, bonds, cash, property and commodities. The classification helps describe what an investment owns and which risks influence its returns.
Australia’s Moneysmart defines asset classes by shared characteristics and market behavior. Similar does not mean identical: investments in one class can have different legal rights, regulations, currencies, liquidity and risk.
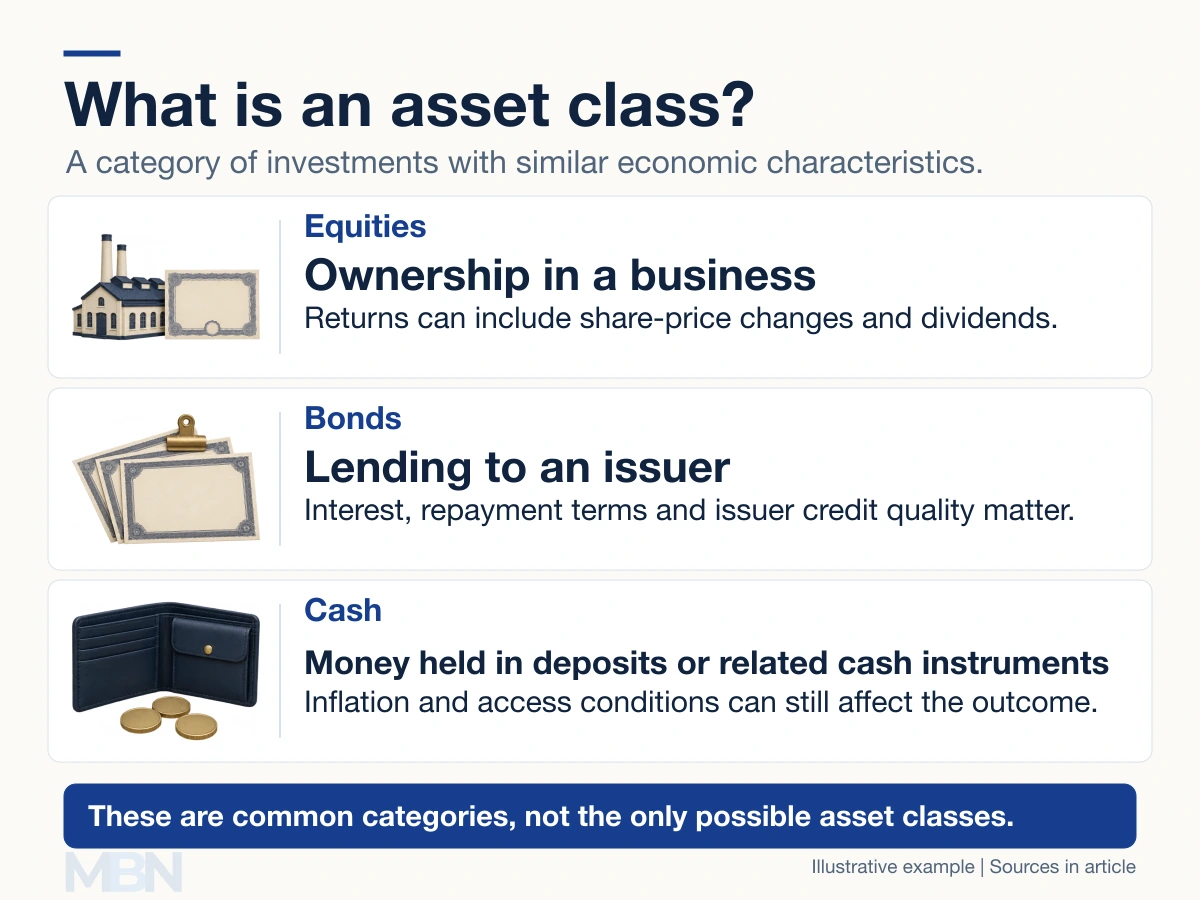
Common asset classes
Equities are ownership interests in companies. A shareholder may receive dividends and a gain when selling, but dividends can stop and the share price can fall.
Bonds represent lending to an issuer, such as a government or company. Their interest and repayment terms vary. Despite the name fixed income, some securities pay floating rather than fixed rates. Credit quality and sensitivity to market interest rates affect risk.
Cash commonly includes bank deposits and similar holdings. Access and protection depend on the product. Inflation can reduce purchasing power even when the nominal balance is unchanged.
Property and commodities are often treated as additional classes. Property can produce rental income and gains or losses on sale. Commodities include physical goods such as metals and agricultural products.
Moneysmart’s investment overview explains that property can lose value, incur substantial costs and take time to sell. Borrowing increases its financial risk. Property is therefore not automatically a conservative holding.
An asset class is different from an investment vehicle
A mutual fund or exchange-traded fund, called an ETF, pools money to invest. It is a vehicle through which investors obtain exposure. A fund can hold equities, bonds, several classes or a narrow market segment.
Investor.gov also defines derivatives through their relationship to an underlying asset, security or index. A contract linked to shares and a contract linked to oil do not have the same economic exposure merely because both are derivatives.
Asset allocation and diversification
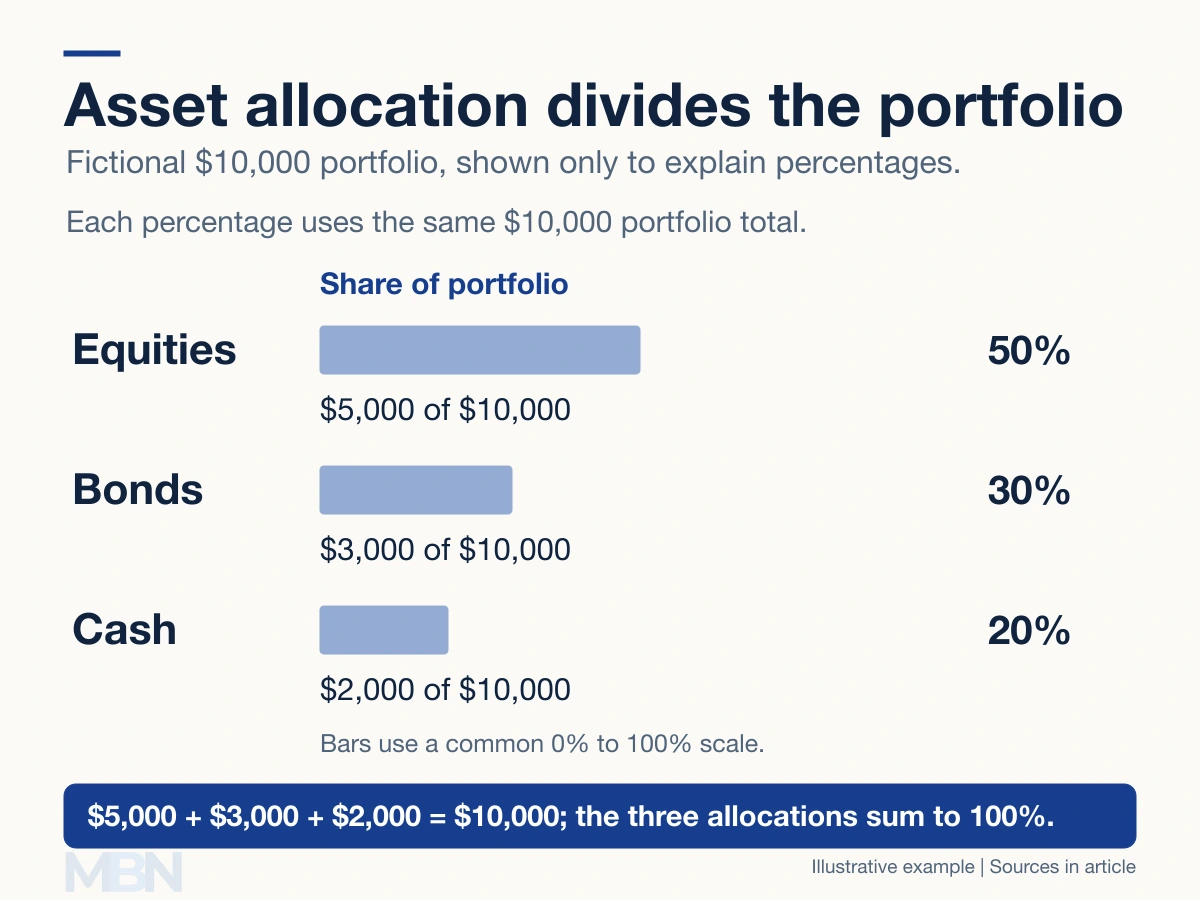
Asset allocation divides a portfolio among different investments or asset categories. For example, a fictional $10,000 portfolio containing $5,000 of equities, $3,000 of bonds and $2,000 of cash has allocations of 50%, 30% and 20%.
Diversification spreads exposure both across categories and within them. Holding shares in several companies differs from placing the entire equity allocation in one company. Owning several funds with overlapping holdings may still leave substantial concentration.
Michigan’s investor-education guidance states that diversification does not guarantee returns or eliminate significant losses. Asset prices can fall together. The category label cannot promise either a return or protection from loss.
Why there is no universal allocation formula
A portfolio’s purpose, investment horizon, liquidity needs and capacity for loss matter. Age alone does not determine an appropriate mix. A rule such as 100 minus age is a rough heuristic, not a financial requirement.
Nor does an asset class carry a guaranteed minimum holding period after which a loss must recover. The particular securities, purchase price, costs, market conditions and need to sell all affect the result.
Last checked and updated on November 4, 2026 by the MBN editorial team.