
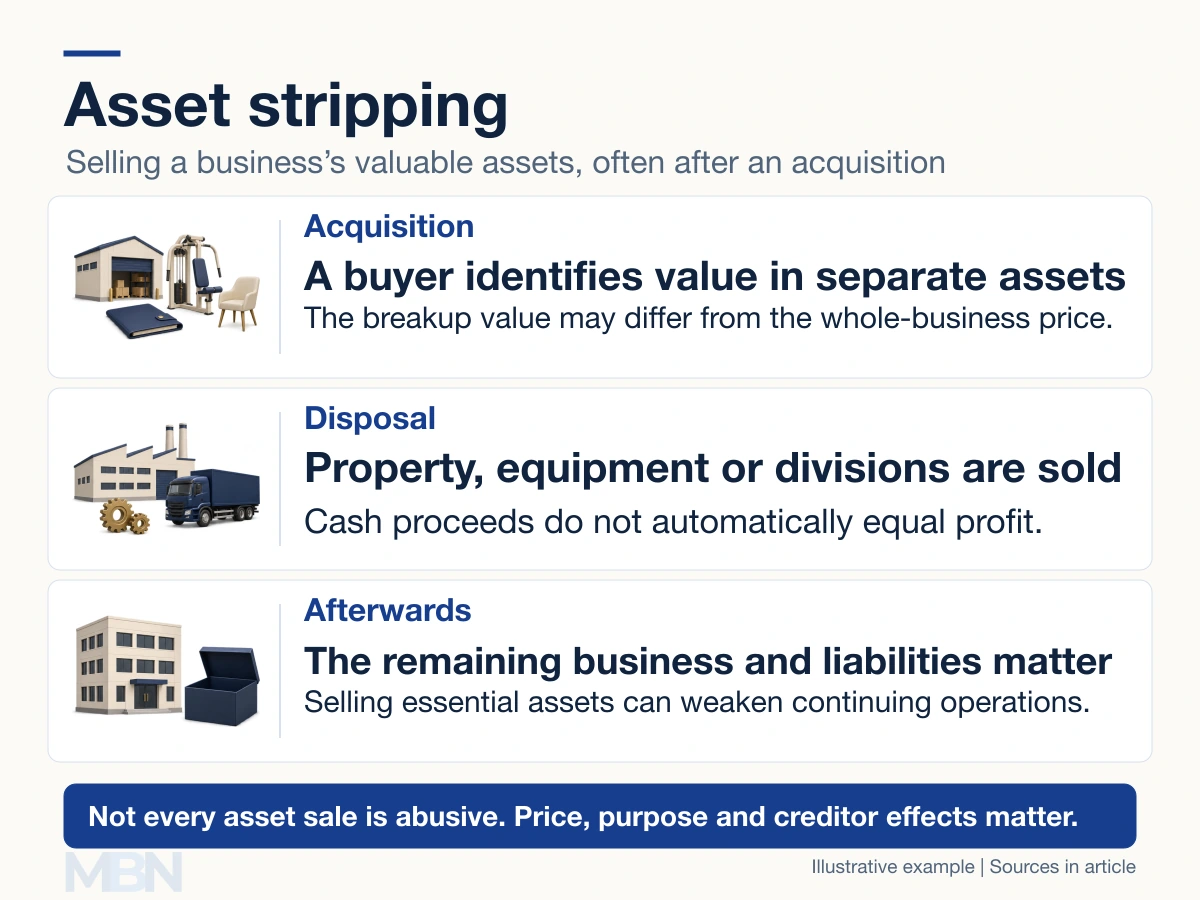
Asset stripping means selling a business’s valuable assets, often after acquiring it. The term is usually critical, particularly when owners extract value while leaving a weakened business, unpaid liabilities or losses for creditors.
It is also used more broadly for buying a company because its assets or divisions appear worth more separately than together. That commercial possibility is not a guarantee that the assets can be sold quickly or at their estimated prices.
What can be sold?
Assets may include land, buildings, machinery, brands, intellectual property or entire operating divisions. Sale proceeds can repay borrowing, fund the remaining business or be distributed to owners, subject to contractual and legal restrictions.
Selling an asset does not necessarily close the business using it. A sale-and-leaseback, for example, transfers property ownership while allowing continued use under a lease. It also creates ongoing rental obligations.
How does the financial example work?
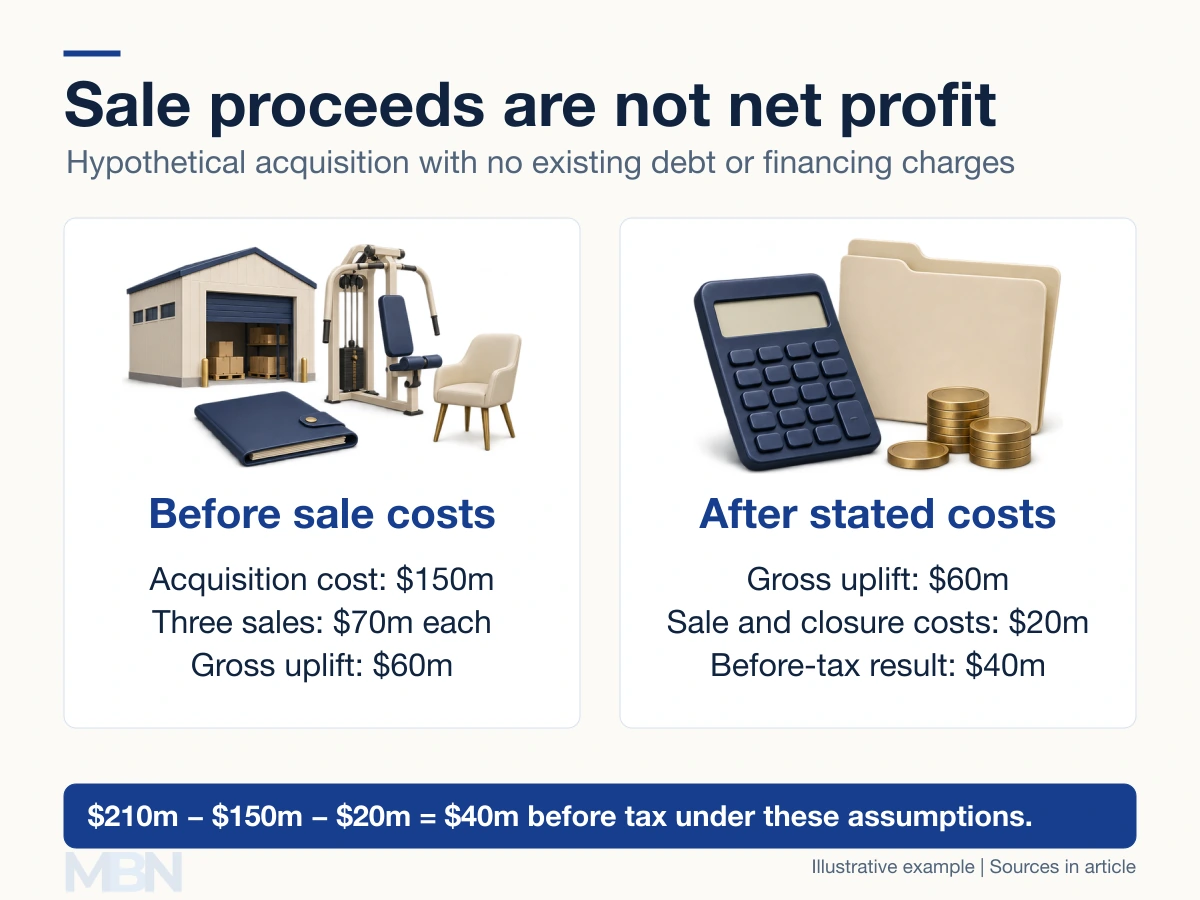
Suppose a buyer pays a total acquisition cost of $150 million for a company with three divisions. Each division is then sold for $70 million, producing $210 million of gross proceeds.
The difference is $60 million, not necessarily net profit. Assume the company has no existing debt, there are no financing charges and disposal and closure costs total $20 million. The result is $40 million before tax under those assumptions.
In a real transaction, debt, employee obligations, taxes, transaction fees and the costs of winding down shared services can change the amount left. Equity purchase price and enterprise value are different measures, so mixing them with gross asset-sale proceeds can produce a misleading comparison.
How does it differ from restructuring?
A business may sell an unused site or a division that no longer fits its operations to reduce debt or concentrate on its remaining activities. A liquidation can also involve selling assets to pay creditors under a formal process.
The label “asset stripping” alone does not establish whether a sale was sensible, harmful or unlawful. The consideration received, where the proceeds go and what resources and obligations remain are central to that assessment.
When can legal issues arise?
Removing assets for little or no payment can harm creditors. The UK Parliament’s insolvency guidance discusses concerns about asset extraction before insolvency. Insolvency means, broadly, an inability to pay debts or an excess of liabilities over assets under the relevant legal tests.
In England and Wales, section 238 of the Insolvency Act 1986 allows certain transactions at an undervalue to be challenged. Conditions and defenses apply. An asset sale is not automatically reversed or criminal simply because insolvency later occurs.
The Insolvency Service also distinguishes genuine efforts to continue trading from transactions open to recovery. Other jurisdictions have their own creditor-protection, corporate and insolvency rules. A transaction’s legal treatment depends on those rules and its facts.
Last checked and updated on November 10, 2026 by the MBN editorial team.