
The back-end ratio compares a mortgage applicant’s qualifying monthly debt payments, including the proposed housing payment, with qualifying gross monthly income. It is also called the total debt-to-income ratio, or DTI.
The Consumer Financial Protection Bureau explains DTI as monthly debt payments divided by gross monthly income. Gross income means income before taxes and other deductions. For a mortgage application, the lender establishes which income and payments qualify under the loan program.
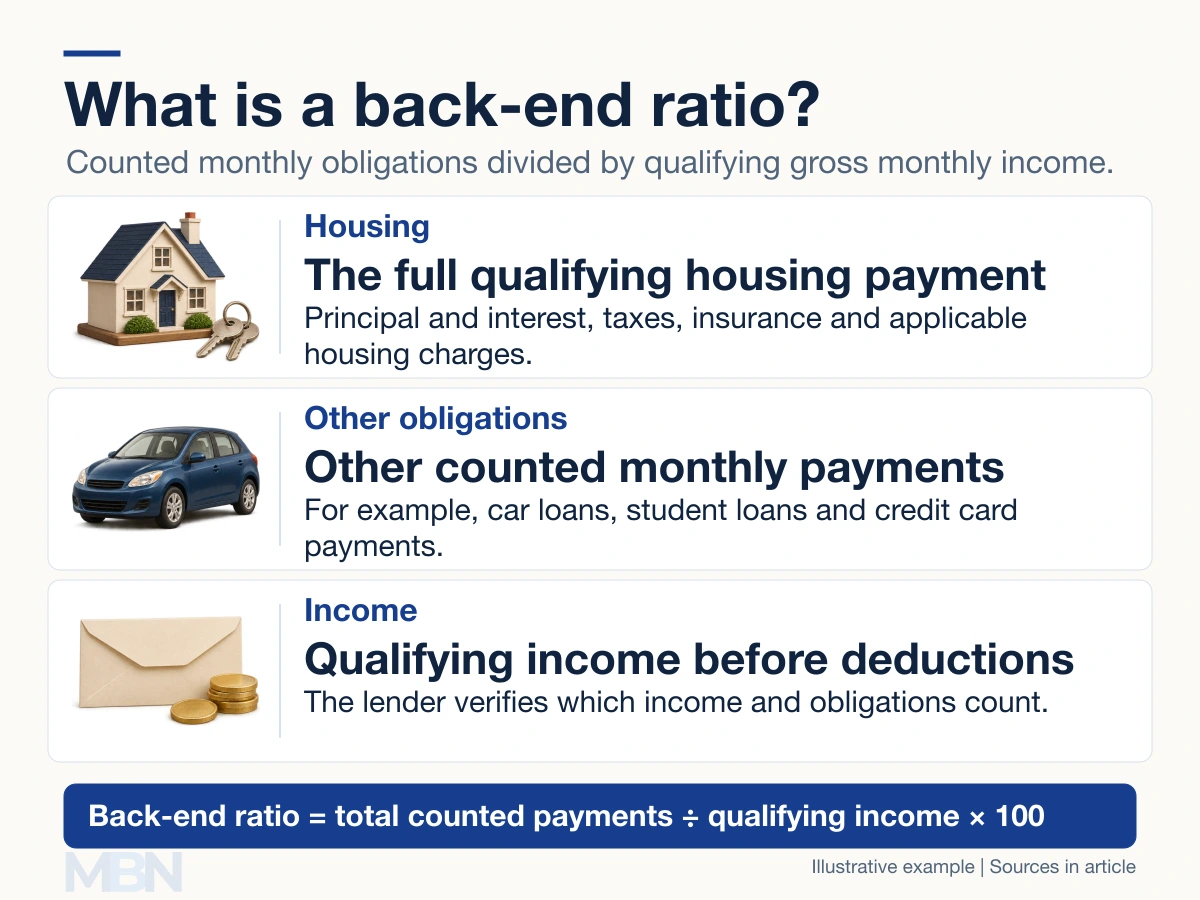
What goes into the calculation?
The numerator, the amount above the division line, includes the qualifying housing payment and other counted obligations. The denominator is qualifying gross monthly income. Multiply the result by 100 to express it as a percentage.
Back-end ratio = total counted monthly payments ÷ qualifying gross monthly income × 100.
The housing amount extends beyond a mortgage’s principal and interest. Fannie Mae’s housing-expense guidance includes property taxes, applicable insurance, association dues and other required housing charges. A monthly estimate may be needed even when a bill is paid annually.
Other obligations can include car loans, student loans, credit card payments and certain support payments. Their treatment depends on the applicable rules. Fannie Mae’s debt guidance, for example, sets specific requirements for different obligations and exclusions. The proposed mortgage must not be counted twice.
A monthly-payment example
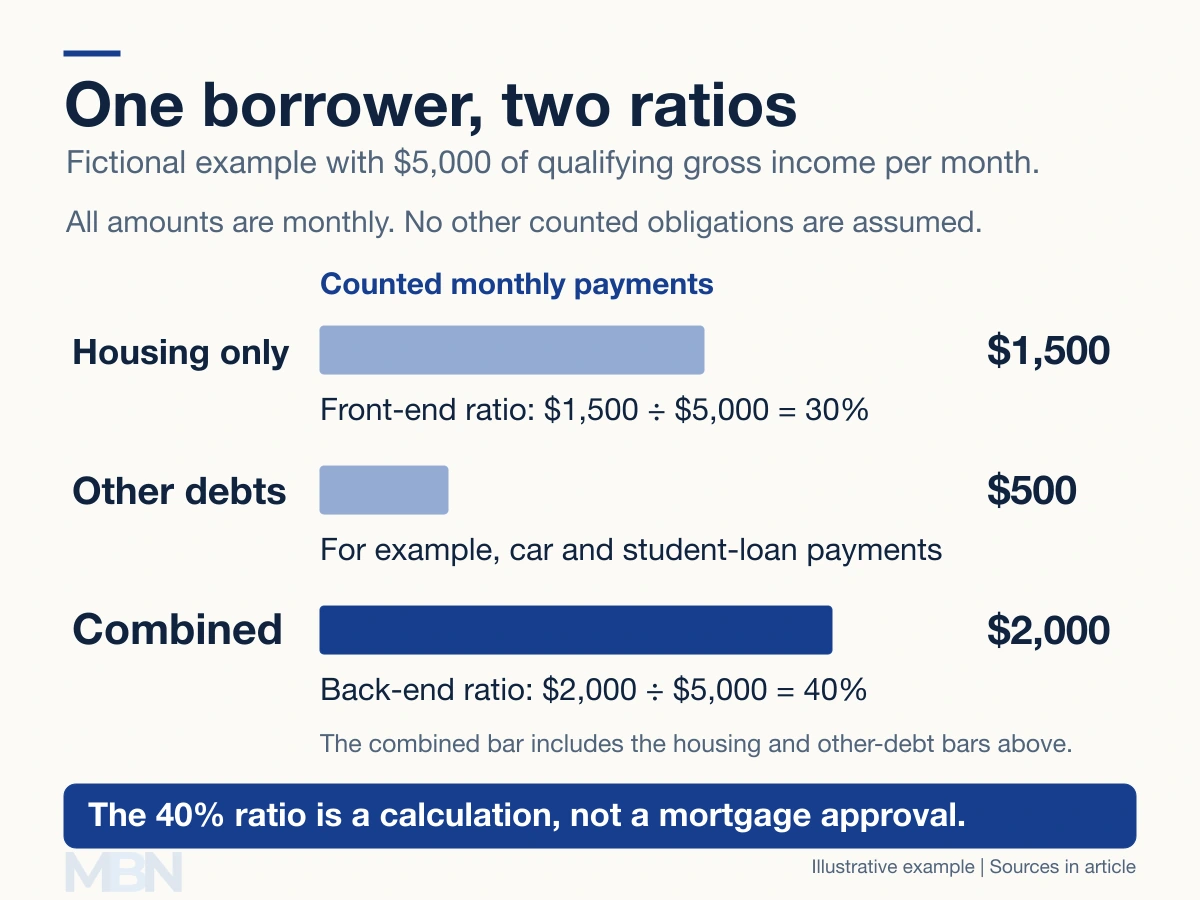
Suppose a fictional applicant has $5,000 in qualifying gross monthly income. The full qualifying housing payment is $1,500, including taxes and applicable insurance. Other counted monthly debt payments total $500. Assume there are no additional counted obligations.
The total is $1,500 + $500 = $2,000. The back-end ratio is $2,000 ÷ $5,000 × 100 = 40%. These assumed figures describe the calculation, not current mortgage pricing or a lender’s decision.
What is the front-end ratio?
The front-end ratio compares housing expenses alone with qualifying gross monthly income. In the same example, $1,500 ÷ $5,000 × 100 = 30%. The back-end ratio is higher because it also includes the other $500 in counted payments.
These measures answer different questions. The front-end ratio describes the housing commitment relative to income. The back-end ratio captures a broader set of financial obligations.
There is no universal approval ratio
DTI limits vary by lender, loan program and underwriting method. Under Fannie Mae’s current guidance, the usual maximum for manually underwritten loans is 36%, with eligibility up to 45% when specified credit-score and reserve requirements are met. Its automated Desktop Underwriter system has a 50% maximum, subject to the guide’s requirements and exceptions.
These are Fannie Mae program rules, not limits for every mortgage. A ratio within a limit does not guarantee approval. Credit, assets, the property and other loan requirements also matter.
The ratio is not a complete household budget either. Food, individual utility bills and many other living costs are not ordinary debt payments. Two households with the same DTI may have very different amounts left after their everyday spending.
Last checked and updated on November 2, 2026 by the MBN editorial team.