
A balance sheet reports an entity’s assets, liabilities and equity at a particular date. It is also called a statement of financial position.
For example, a balance sheet dated September 30, 2026 describes recorded balances at that date. An income statement instead reports performance over a period, such as the three months ending on that date.
What are assets, liabilities and equity?
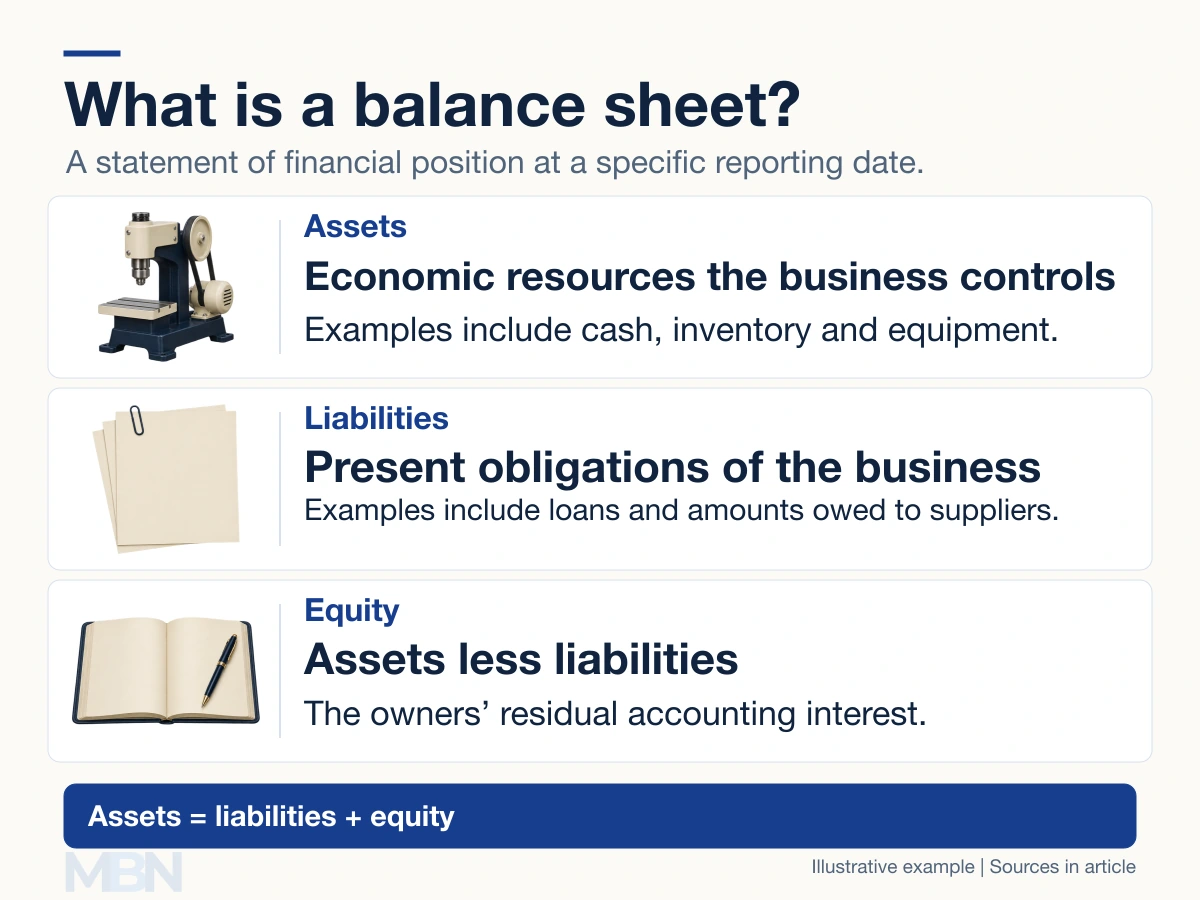
The IFRS Conceptual Framework distinguishes economic resources, obligations and the owners’ residual interest. Assets involve resources the business controls, not simply everything it physically possesses. Inventory and equipment are familiar examples; rights can also qualify.
Liabilities are present obligations, including amounts owed to suppliers and lenders. Equity is the amount remaining when recorded liabilities are deducted from recorded assets. Recognition and measurement rules determine what enters the statement and at what amount.
Why must a balance sheet balance?
The accounting equation is assets = liabilities + equity. The US Securities and Exchange Commission’s guide explains how the financial statements fit together.
Suppose a fictional business has $100,000 of assets and $60,000 of liabilities. Its equity is $40,000. These are accounting balances, not a promise that selling the business would produce the same amount for its owners.
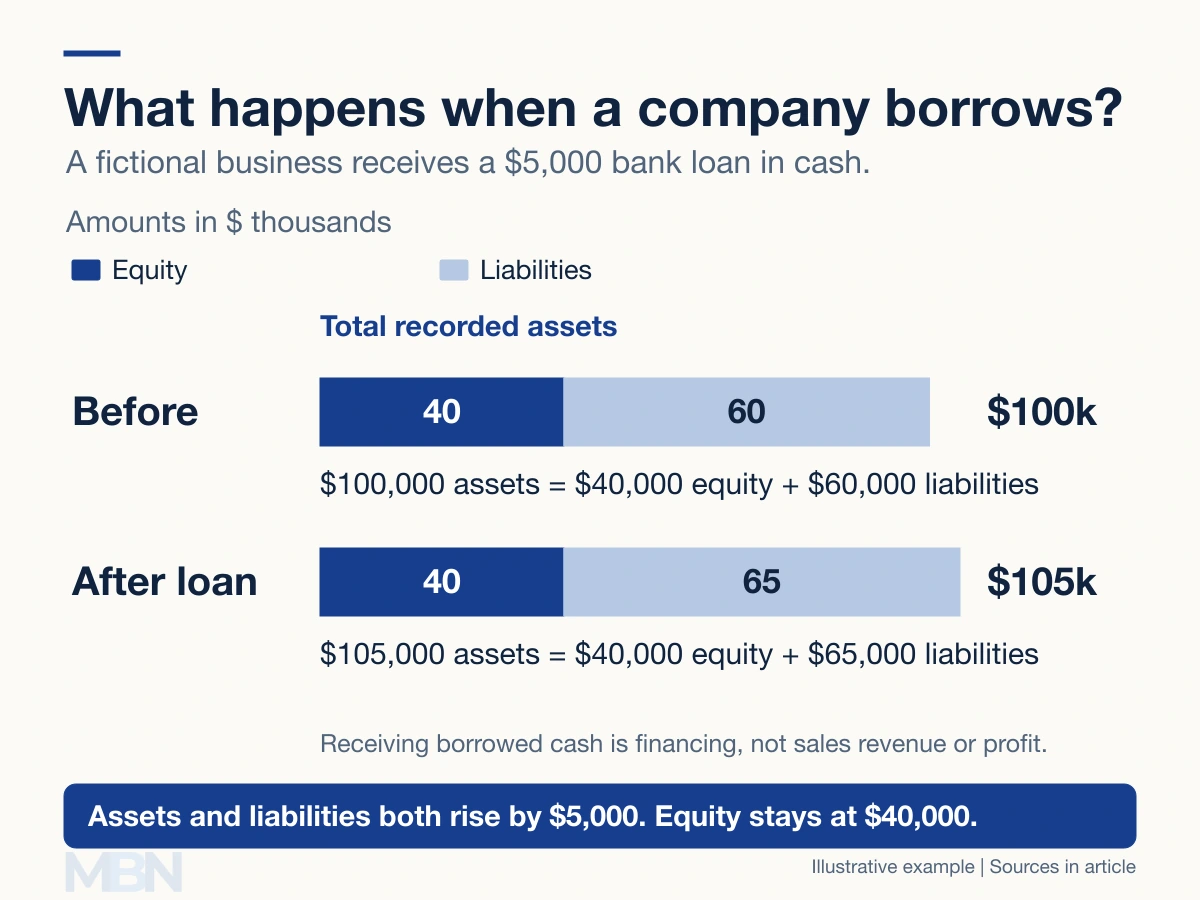
Receiving a $5,000 loan raises cash and loan liabilities by $5,000 each. Assets become $105,000, liabilities become $65,000 and equity remains $40,000.
Separately, a $5,000 cash contribution from an owner would increase assets and equity, rather than liabilities. Buying $5,000 of equipment for cash would exchange one asset for another, before any fees or other effects.
How do profits affect equity?
Profit can increase retained earnings, the accumulated earnings kept in the business. Losses and distributions can reduce equity. Other recognized changes may also affect it under the applicable accounting rules.
Revenue is not calculated by subtracting liabilities, and receiving cash is not always revenue. Borrowing is one example. A sale on credit can also produce revenue before the customer pays.
What can the statement tell readers?
It helps explain the resources available, obligations outstanding and financing structure at the reporting date. Comparisons across dates can reveal changes in borrowing, inventory, receivables and cash.
It does not by itself explain the period’s profit or cash generation. Those questions require the income statement, cash-flow statement and accompanying notes. A balanced equation alone does not establish profitability, liquidity or financial safety.
Last checked and updated on November 3, 2026 by the MBN editorial team.