
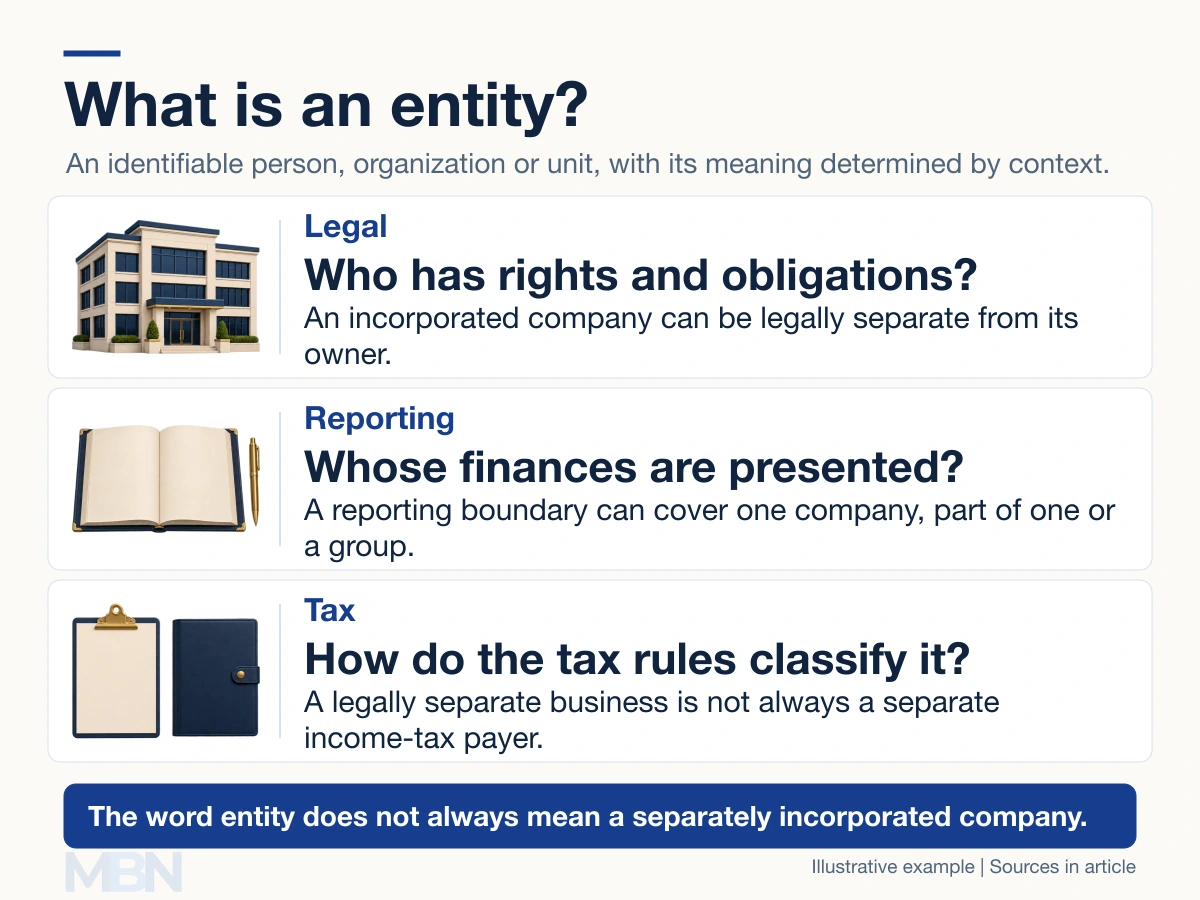
An entity is an identifiable person, organization or unit considered for a particular purpose. In business and finance, its meaning depends on the context: a legal entity has rights and obligations, while a reporting entity defines whose financial information is presented. Tax rules can draw a different boundary again.
The term is therefore broader than “company.” A reference to an entity does not, by itself, establish incorporation, limited liability, a separate tax return or a profit-making purpose.
A legal entity and its owners
An incorporated company can exist separately from the people who own it. For example, GOV.UK describes a UK limited company as legally separate from its owners. Owning all its shares does not turn the company’s assets into the shareholder’s personal property.
A UK sole trader has a different structure. The individual operates the business and is personally responsible for its debts. Keeping business records or using a trading name does not create a separate incorporated company.
Other structures have their own rules. A partnership, trust, association or public body should not automatically be assumed to have the same legal personality, powers or liability arrangements as a corporation. The relevant jurisdiction and structure matter.
A reporting entity need not be a legal entity
The IFRS Conceptual Framework for Financial Reporting explains that a reporting entity may be a single entity, a portion of one, or more than one entity. It need not be a legal entity in its own right.
Suppose fictional Company A controls Company B. They are two legal entities. Consolidated financial statements can present the parent and subsidiary together as one reporting entity, without merging the companies legally.
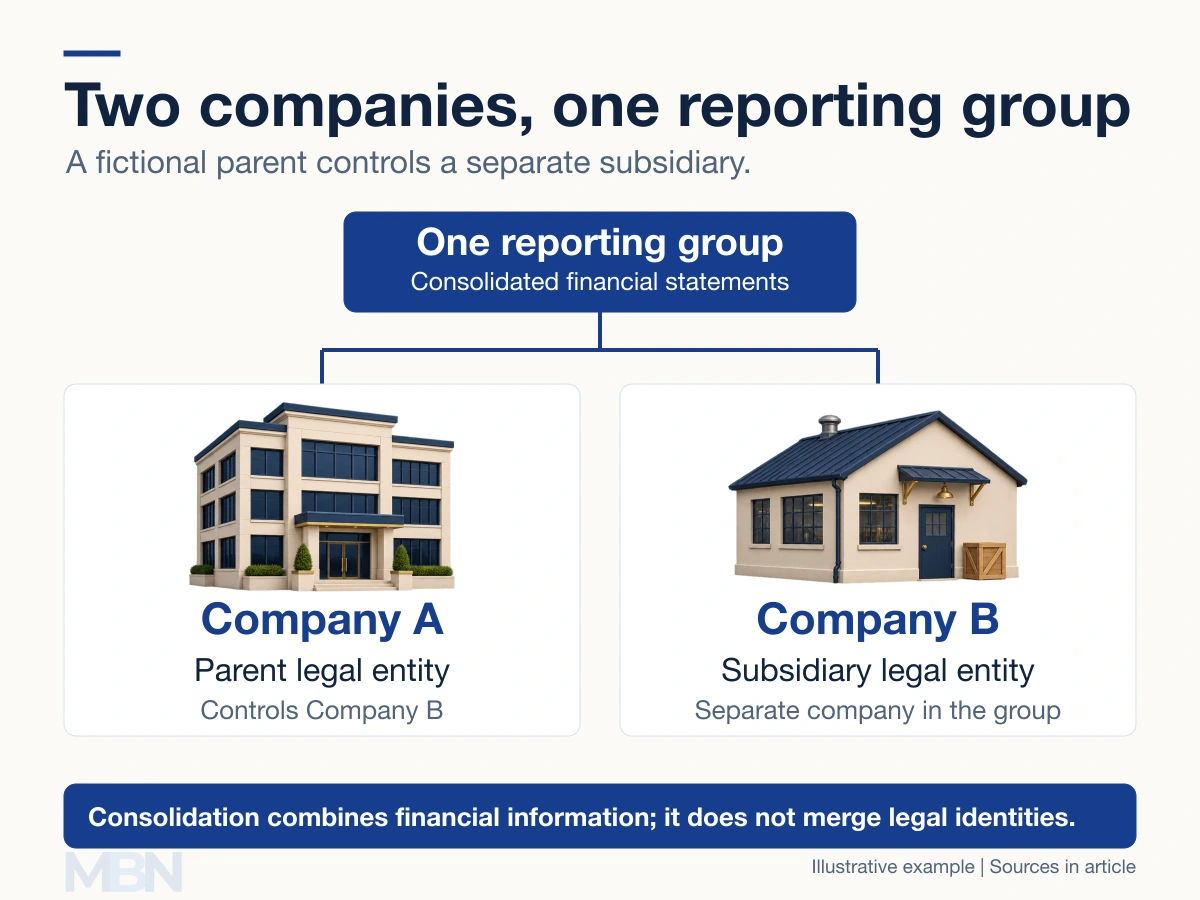
A division can also have its financial performance reported separately while remaining part of one legal company. Conversely, a subsidiary is a separate entity controlled within a group.
Tax classification is a separate issue
Separate legal existence does not always mean separate income-tax treatment. The IRS explains that a single-member limited liability company can be disregarded as separate from its owner for US federal income tax, unless it elects corporate classification.
In that case, its activities generally appear on the owner’s income-tax return. It can nevertheless be treated separately for employment tax and certain excise taxes. “Disregarded” describes that tax treatment; it does not mean the business has ceased to exist under state law.
Profit-making purpose is another distinction
Entities may pursue commercial, charitable, membership or public purposes. For-profit and nonprofit describe an important distinction in purpose and distribution rules, rather than an exhaustive list of legal structures.
A nonprofit organization can charge fees, employ staff and report a surplus. It is not necessarily funded only by donations or volunteers, and nonprofit formation does not automatically confer tax exemption.
What is a financing entity?
In ordinary financing language, this can mean a party supplying funds. Some laws give the term a narrower definition.
For example, New York Insurance Law section 7802(e) defines it for life settlements as an accredited investor whose main transaction activity is supplying funds to effect a settlement or purchase policies, and who has a written financing agreement with a life settlement provider. An accredited investor meets specified investor-eligibility rules.
A life settlement involves transferring an existing life-insurance policy or rights under it for compensation. This financing-entity definition belongs to that statutory setting; it is not a universal definition for every loan or insurance transaction.
Entity outside business law
The word can also identify a thing or unit in a model. In software and databases, an entity might represent a customer, product or other object with attributes and relationships. Oracle’s entity documentation, for example, illustrates customers linked to address information. An entity does not have to be unnamed or mysterious.
Last checked and updated on November 4, 2026 by the MBN editorial team.