
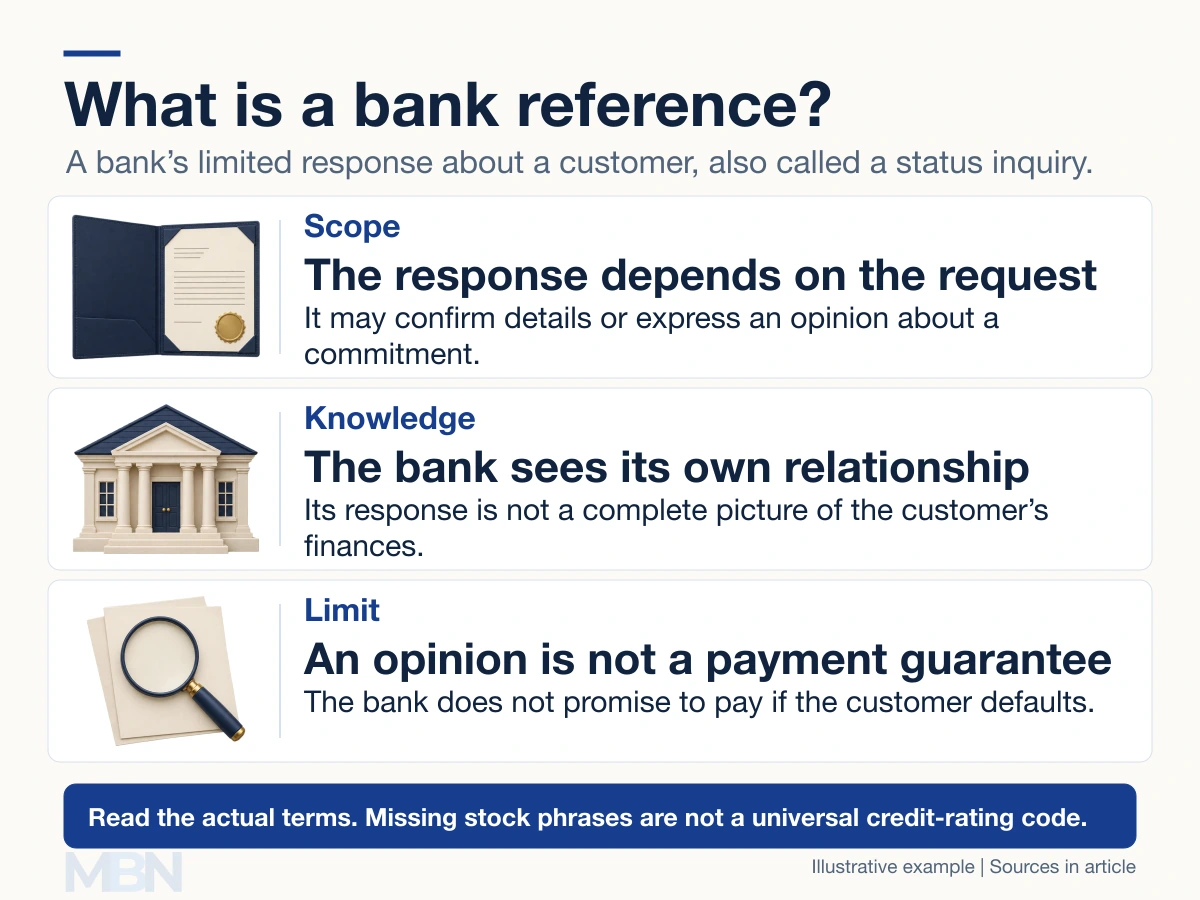
A bank reference is a bank’s response to a request for information or an opinion about one of its customers. Also called a banker’s reference or status inquiry, it has a defined scope and does not guarantee that the customer will pay a debt.
The reference must be read in context: who requested it, what commitment it concerns, when it was issued and what qualifications the bank included.
What can the response contain?
Barclays distinguishes general verification requests from financial-commitment opinions. The former can confirm customer details; the latter concern the ability to meet a specified commitment. Its process requires the account holder’s signed consent.
There is no universal code in which the absence of a word such as “respectable” proves that a customer is unreliable. Nor is it correct to say that bank references never contain specific information.
The Bank of Ireland UK’s 2019 guide illustrates a more limited format: a general opinion without specific account information, expressly described as no guarantee. This historical example explains why references differ; its old product charges and other terms should not be treated as current.
A supplier-credit example
Suppose a fictional wholesaler is considering a £12,000 order payable in 30 days. A bank opinion about that commitment is one input to the decision. It does not establish the buyer’s entire debt position or make the bank liable for the invoice.
A credit bureau report and a bank statement are different documents. A reference is not a substitute for either. A payment reference, meanwhile, is identifying text attached to a transfer, and a reference interest rate is a benchmark used in pricing.
Charges and permitted use vary
Barclays’ published process includes an administration charge, confidentiality restrictions and limits on further disclosure or reliance by other parties. These are that bank’s conditions, rather than rules shared by every bank worldwide.
A landlord cannot ignore deposit limits
A disappointing reference does not permit an unrestricted larger deposit. Current government guidance for England explains the Tenant Fees Act caps: five weeks’ rent where annual rent is below £50,000, or six weeks for higher annual rent within the Act’s scope. Properties above £100,000 annual rent are outside that scope.
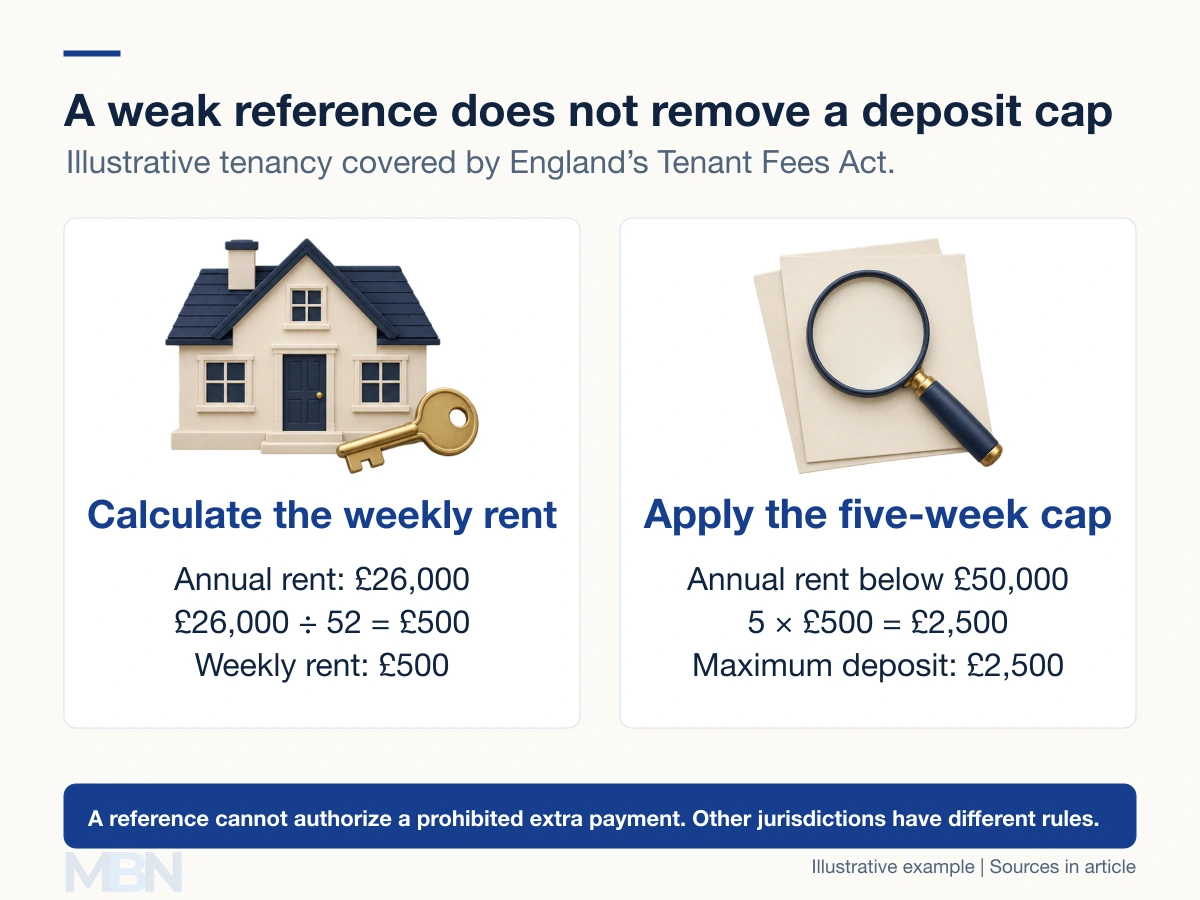
Schedule 1 defines a week’s rent as annual rent divided by 52. In the example, £26,000 ÷ 52 × 5 gives £2,500. A holding deposit is separate and capped at one week’s rent. These England rules should not be generalized to the whole UK or other countries.
Last checked and updated on November 4, 2026 by the MBN editorial team.