
A bookkeeper records, classifies and checks the financial transactions of a business or other organisation. The work creates the records used to track sales, expenses, amounts owed and other financial activity. It is called bookkeeping.
The role extends beyond recording money received and paid. Under accrual accounting, it can also include invoices awaiting payment, unpaid supplier bills and other entries that do not immediately change the bank balance.
What does a bookkeeper do?
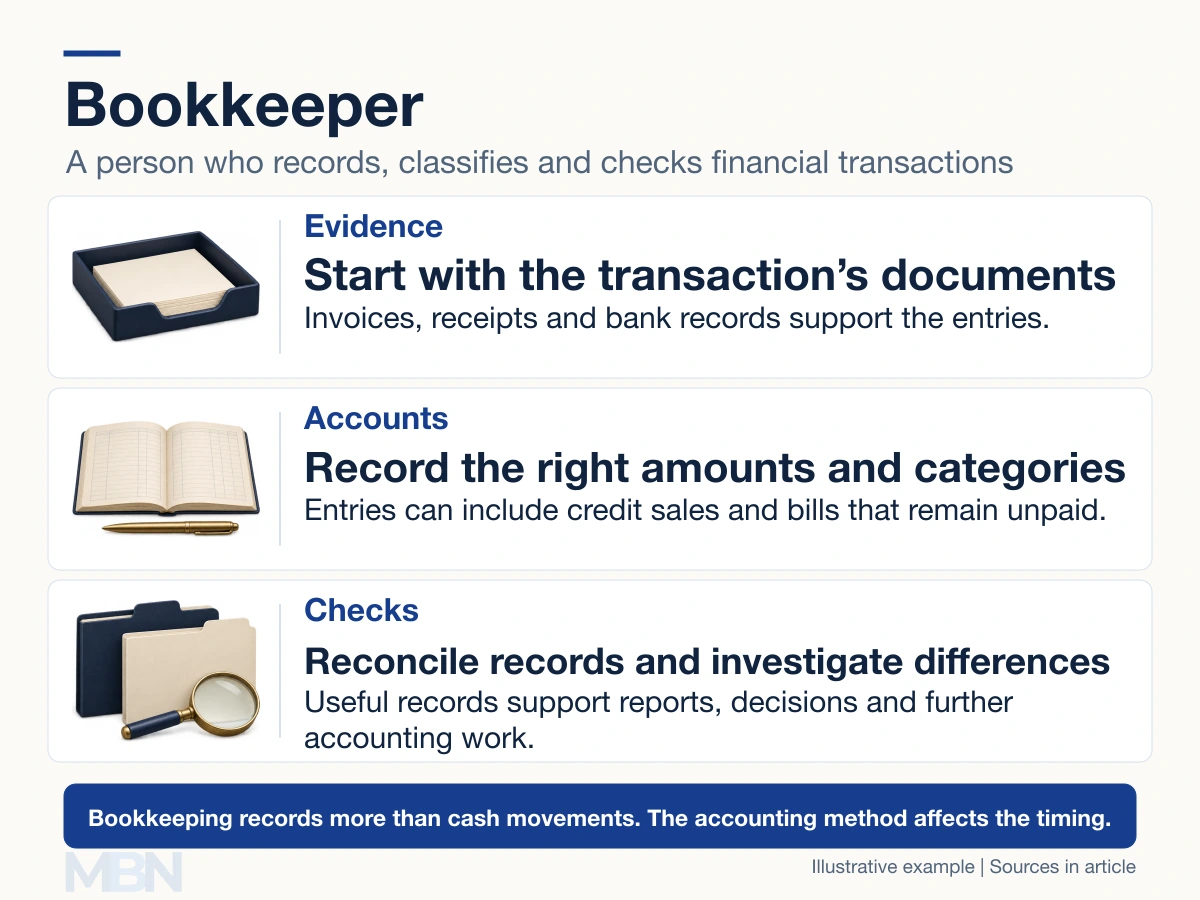
Typical tasks include entering sales and purchases, allocating transactions to accounts, tracking customer and supplier balances, reconciling bank records and checking discrepancies. Some bookkeepers handle payroll, prepare reports or maintain the organisation’s entire ledger, its central set of accounting records.
The US Bureau of Labor Statistics describes a range of bookkeeping duties, rather than a single fixed job boundary. Responsibilities depend on the employer’s size, the worker’s skills and the services agreed.
How a transaction becomes a record
A transaction should have supporting evidence. An invoice records a charge; a receipt or bank record can help establish payment. The bookkeeper uses those documents to enter the date, amount, counterparty and appropriate accounts.
Double-entry bookkeeping records corresponding debits and credits. These terms describe sides of an account, not simply money coming in and going out. For example, increasing a cash asset is normally a debit; increasing sales revenue is normally a credit.
Suppose a business completes a £1,000 service on credit. In a simplified accrual example, it records £1,000 of revenue and a £1,000 customer receivable, an amount owed to it. Cash has not yet arrived.
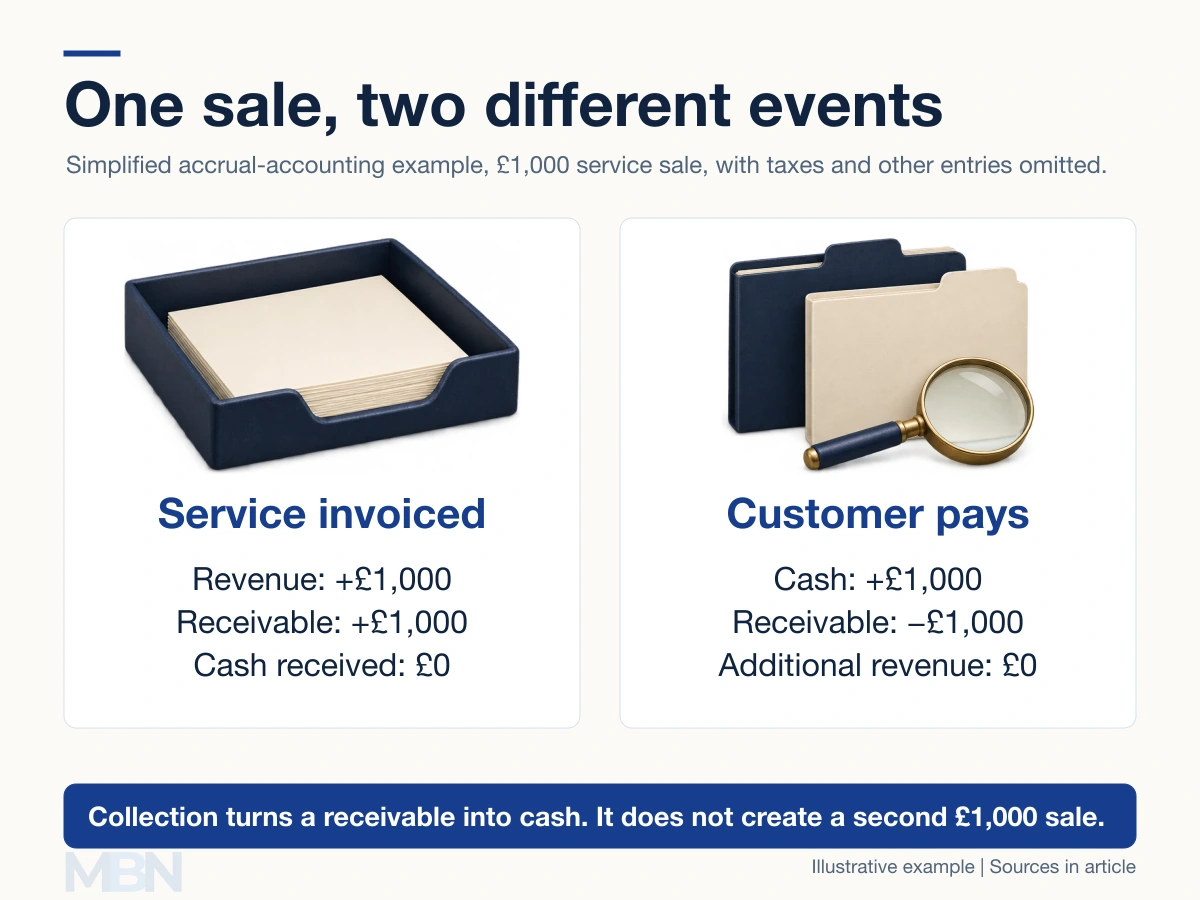
When the customer pays, cash rises by £1,000 and the receivable falls by £1,000. Revenue is not recorded again. A cash-basis system uses different recognition timing, so the accounting method must be clear.
Why reconciliation matters
Reconciliation compares related records and explains differences. A bank reconciliation might identify a payment still clearing, an omitted fee or a duplicate entry. A discrepancy is a reason to investigate, rather than automatically proof of fraud.
The IRS recordkeeping guidance explains how supporting documents feed into business books. Its Publication 583 describes journals, ledgers and electronic records. Reliable records help monitor a business and support accounts and tax reporting, although legal requirements vary by jurisdiction.
Bookkeeper and accountant
Bookkeeping concentrates on maintaining the underlying records. Accounting also covers interpreting results, applying reporting standards and advising on financial questions. The Association of Accounting Technicians explains that the work overlaps: a bookkeeper may prepare reports, and an accountant may perform bookkeeping.
Managers can use reliable bookkeeping reports for decisions about unpaid invoices or available cash. Complex tax, reporting or financing questions may require additional expertise. The job title alone does not establish a person’s qualifications or authority to provide regulated services.
How software changes the work
Software can import transactions, suggest categories and match payments. These tools reduce some manual entry but still require checks for errors, duplicates and missing information. Automation changes tasks and staffing needs; it does not establish that every bookkeeping role will disappear or that every automated entry is correct.
Last checked and updated on November 11, 2026 by the MBN editorial team.