
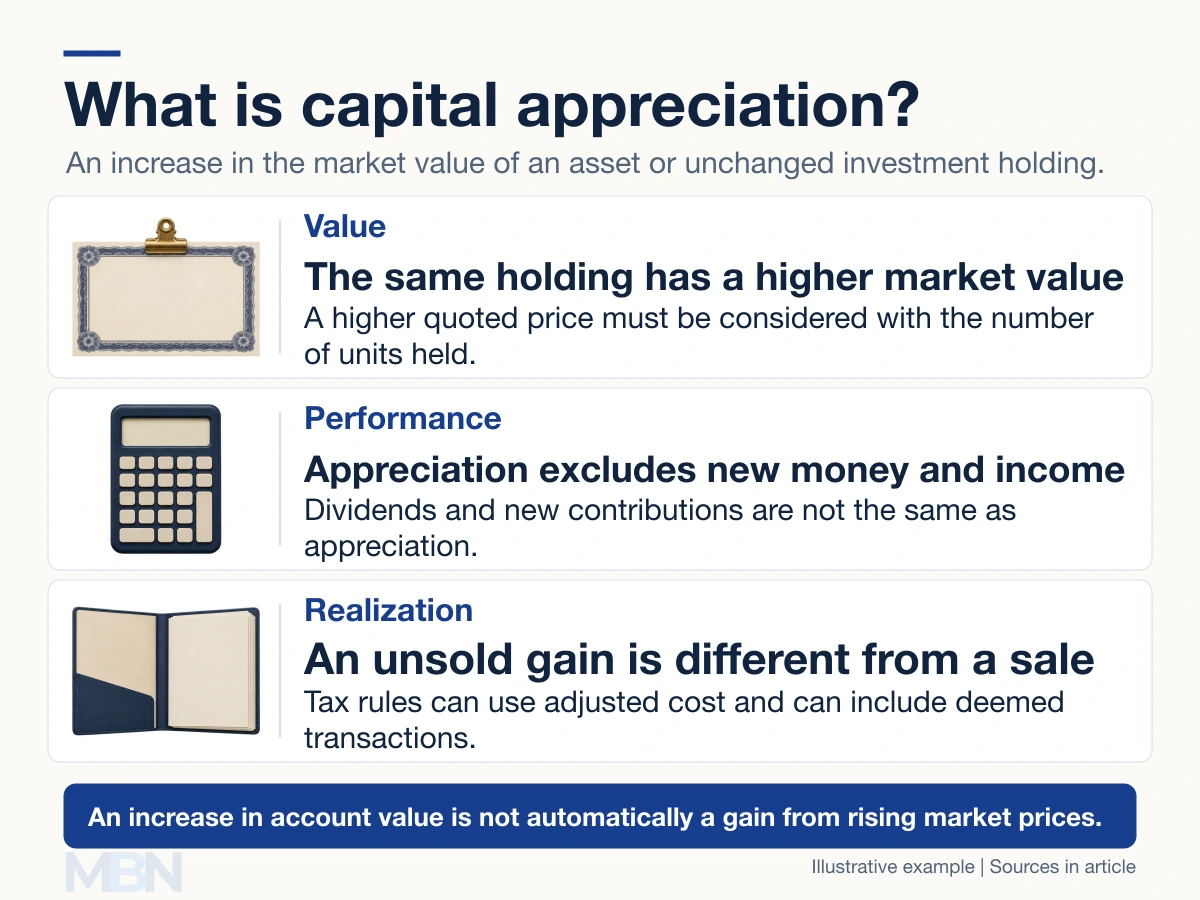
Capital appreciation is an increase in an asset’s market value. For an unchanged holding, it is the difference between its later value and the comparison value, often the original purchase cost. It is distinct from cash income and additional money invested.
It is also called capital growth. Moneysmart defines that term as an increase in asset value over time. A valuation gain can exist before the asset is sold.
Calculate the gain for the same holding
Suppose an investor buys 10 fictional shares for $100 each. The investment costs $1,000. If the same shares later trade at $120 each, the holding is worth $1,200 and has appreciated by $200, or 20%, before costs.
A cash dividend would be a separate component of return. Buying additional shares with new money would increase the account balance, but would not itself be capital appreciation.
Share-count changes need adjustment
A quoted share price cannot always be compared directly across dates. The Securities and Exchange Commission’s stock-split explanation shows why the number of shares matters.
In a two-for-one split, 10 shares priced at $100 become 20 shares with a mechanically adjusted price of $50. Ignoring other market movements, the holding remains worth $1,000. The split itself has not doubled the investor’s wealth.
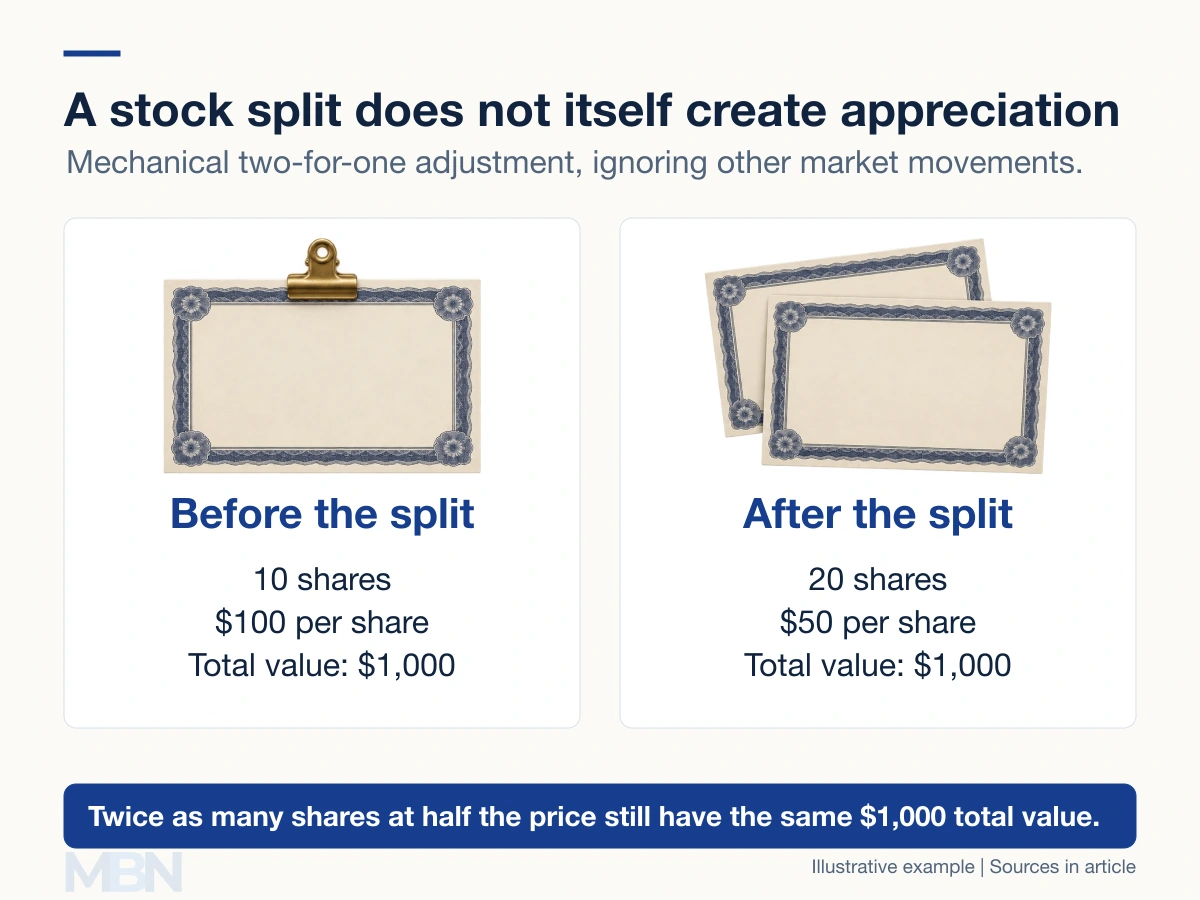
If those 20 shares subsequently trade at $60, they are worth $1,200. That is $200 of appreciation relative to the original $1,000 investment, before other adjustments or costs.
The US Internal Revenue Service explains that an ordinary stock split changes per-share basis while leaving overall basis unchanged. Basis is the amount used to measure the investment for tax purposes, which is a separate question from today’s market value.
Unrealized appreciation and realized gains
An unrealized gain is an increase in a holding’s value before disposal. Selling converts the asset into sale proceeds, subject to transaction costs. The earlier valuation does not guarantee the eventual selling price.
For US capital assets, IRS Topic 409 compares the amount realized on sale with adjusted basis. IRS Topic 703 explains that basis can change through specified adjustments. A taxable capital gain is therefore not always simply the current price minus the original sticker price.
Tax does not always wait for an actual sale
The tax timing depends on the jurisdiction, investment and ownership circumstances. A blanket statement that appreciation can be taxed only after an actual sale is incorrect.
For example, IRS guidance generally treats qualifying section 1256 contracts held at year-end as sold at fair market value. This US tax category covers certain futures and options, among other specified contracts, and has exceptions. The mark-to-market rule can recognize a gain or loss without an actual market sale.
Why appreciation is uncertain
Company results, expectations, interest rates and changes in demand can affect market prices. A new development or strong earnings report does not guarantee a particular price gain.
Investor.gov explains that stock prices can fall even when a company does not fail. Appreciation is an observed or estimated value change, not a promise attached to an asset or a reward guaranteed by holding it longer.
Last checked and updated on November 4, 2026 by the MBN editorial team.