
Capital equipment is durable equipment used to produce goods, provide services or support operations and treated as a capital asset under the relevant rules. Examples can include machinery, laboratory instruments, computers and business vehicles.
There is no universal $5,000 definition, and equipment does not always have to be freestanding. Classification depends on the reporting framework, an organization’s capitalization policy and any tax or funding rules that apply.
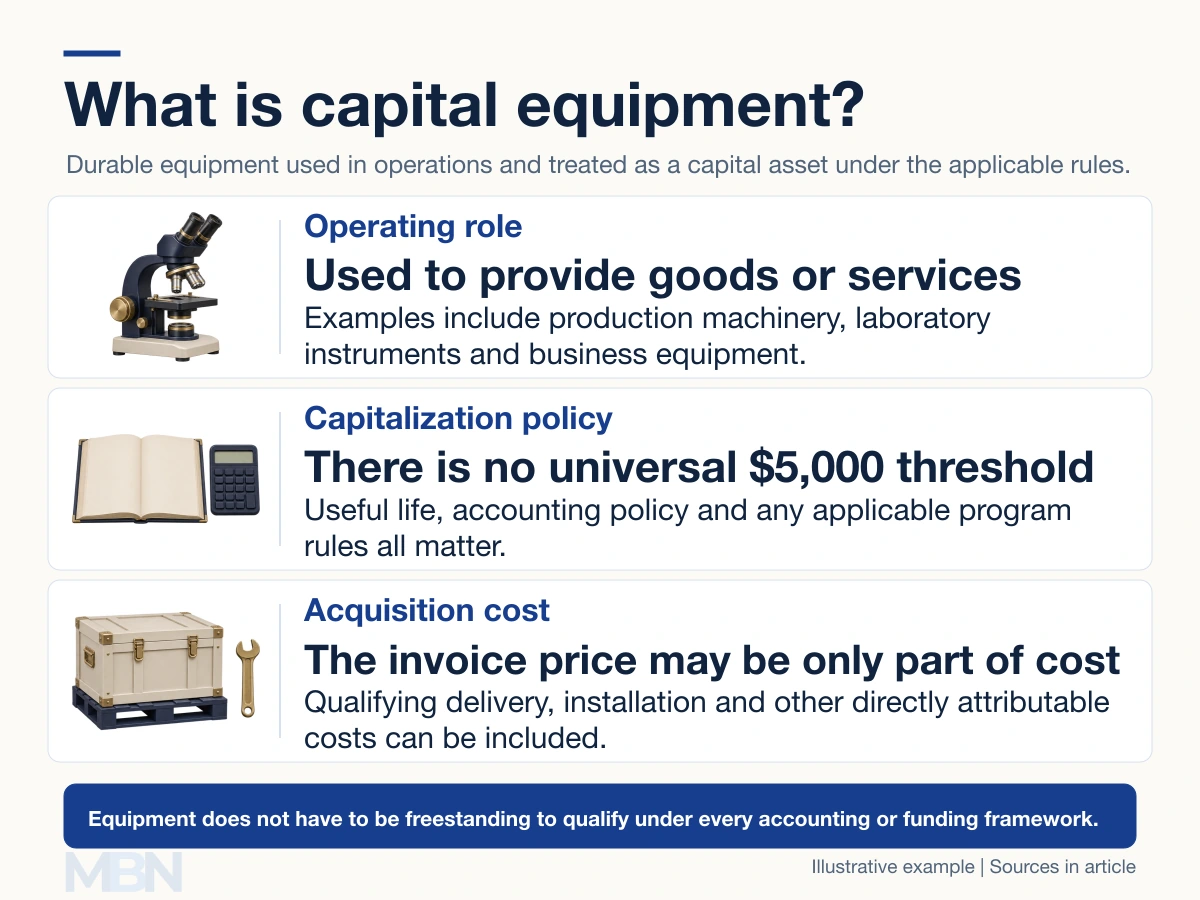
Useful life and operating purpose matter
A laboratory can use a microscope over several years, while a manufacturer can use a machine throughout many production cycles. These differ from supplies consumed quickly or products held for sale.
IAS 16 describes property, plant and equipment as tangible items held for operational, rental or administrative use over more than one period. Recognition also requires the relevant economic-benefit and cost-measurement conditions. Being expensive alone does not settle the accounting.
A machine secured to a factory floor may still be equipment. Buildings, fixtures, land and software can fall into different categories, depending on the policy and framework. A purchasing department’s equipment label is not automatically its tax classification.
A threshold must have a stated context
Organizations can set capitalization thresholds for their financial records. A lower-priced durable item may be expensed under an applicable policy while still needing an inventory, security or maintenance record.
For a specific US example, 2 CFR 200.1 defines equipment for covered federal-award purposes. It uses tangible personal property with a useful life of more than one year and a per-unit acquisition cost at least equal to the lower of the recipient’s financial-statement capitalization level or $10,000.
This is a federal-award definition, not a general rule that every business must capitalize only equipment costing $10,000 or more. An organization’s lower threshold can matter under that definition.
What belongs in equipment cost?
IAS 16 includes qualifying costs directly attributable to bringing equipment to the location and condition needed for its intended operation. Examples include initial delivery, installation and assembly. Nonrefundable purchase taxes can also form part of cost.
Suppose equipment costs $8,000, initial delivery is $600 and necessary installation is $1,400. Assume all three amounts meet the recognition rules, with no other costs, taxes or discounts. Initial equipment cost is $10,000.
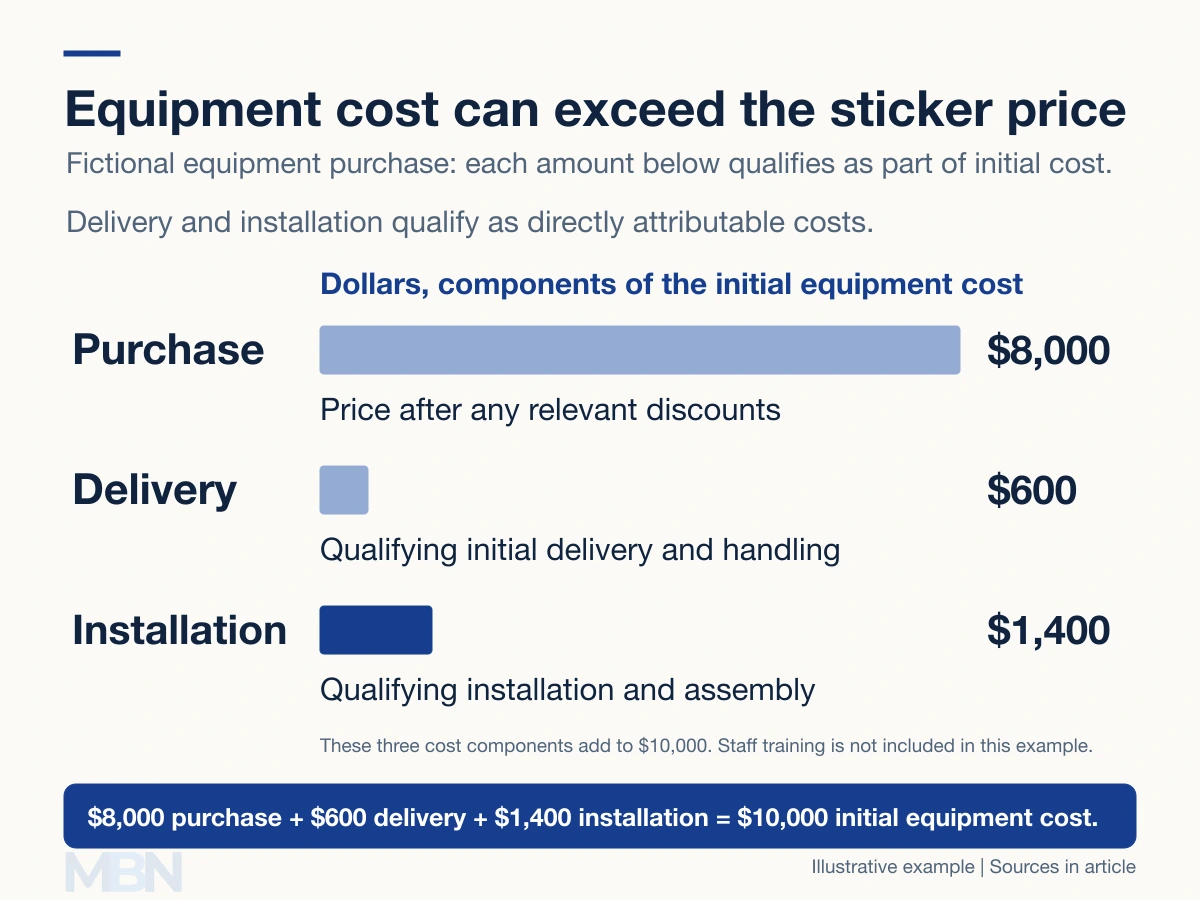
It is incorrect to exclude freight and installation automatically. But not every related payment belongs in the asset: staff training and general administration are examples of costs IAS 16 excludes.
Buying and leasing are different arrangements
Under IFRS 16, a lessee generally recognizes a right-of-use asset and a lease liability, subject to exemptions. That right to use equipment is different from owning the underlying machine. Short-term and low-value lease exemptions have their own conditions.
Approval and budgeting procedures vary between organizations. A committee is not part of the definition of capital equipment. Nor does capitalization mean the purchase creates immediate profit: depreciation generally allocates depreciable cost over the equipment’s useful life, as our capital assets example explains.
Last checked and updated on November 4, 2026 by the MBN editorial team.