
Capital markets are markets for equity and longer-term debt securities, including company shares and bonds issued by companies or governments. They allow issuers to raise funds and investors to buy, hold or sell financial claims.
Capital markets form part of the wider financial markets. They include new issues and trading in existing securities, on exchanges and through over-the-counter arrangements.
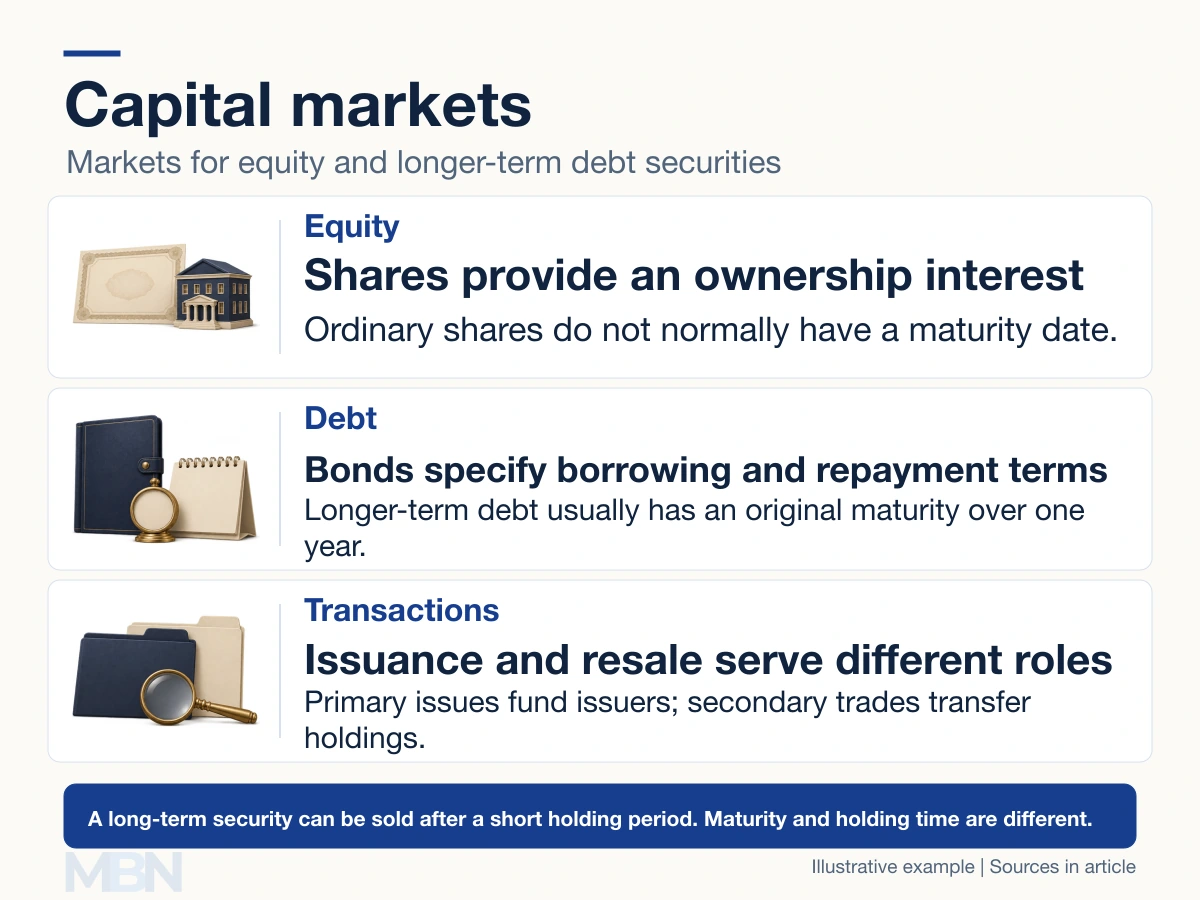
Equity and debt provide different claims
Shares represent an ownership interest. Ordinary shareholders may receive dividends, but payments are not generally fixed contractual obligations. They also bear the risk that the business loses value.
A bond generally makes its holder a creditor. Its terms specify interest, repayment and other conditions. The IMF’s bond primer explains how bonds and yields work. A promised payment does not eliminate default risk, meaning the issuer may fail to pay as agreed.
Issuers may use financing for investment, acquisitions, refinancing or other disclosed purposes. New financing does not automatically become spending on a new factory or other physical asset.
How capital markets differ from money markets
The World Bank’s explanation distinguishes capital markets from money markets, which generally concern short-term borrowing and instruments with maturities of one year or less. Longer-term debt usually has an original maturity beyond one year. Equity normally has no maturity date.
Maturity is different from the investor’s holding period. A five-year bond can be sold after a week without becoming a one-week debt instrument. Some uses of “capital markets” are broader, so the scope of a particular report should be stated.
Primary issuance and secondary trading
In the primary market, newly issued securities raise money for the issuer. In the secondary market, existing holders sell their securities to new buyers.
Secondary trading normally does not give the original issuer fresh cash. It can nevertheless support primary fundraising by providing resale opportunities and market prices, though liquidity is not guaranteed.
Distribution methods vary. Investment banks can underwrite issues, while governments can use auctions. US TreasuryDirect describes its auction process.
A bond-financing example
Suppose a company issues a five-year bond with $5 million face value at par, meaning investors pay that face value. Its fixed annual coupon is 4%, so annual interest is $200,000.

Assuming payment as agreed, investors receive five coupons totaling $1 million and the separate $5 million principal repayment at the end. A secondary buyer’s purchase price can differ from par, so coupon rate and investment yield need not be the same.
Participants, risk and oversight
Participants include issuers, households, funds, pension schemes, insurers, banks and intermediaries. Their objectives and constraints differ. Prices can transmit changes in interest rates, credit conditions and risk appetite across markets, without every disturbance affecting every market equally.
Oversight also differs by instrument and jurisdiction. In the UK, the FCA regulates financial-services conduct, while the Bank of England supervises specified market infrastructures and has other prudential and financial-stability responsibilities. Regulation supports market functioning; it does not guarantee investment returns.
Last checked and updated on November 11, 2026 by the MBN editorial team.