
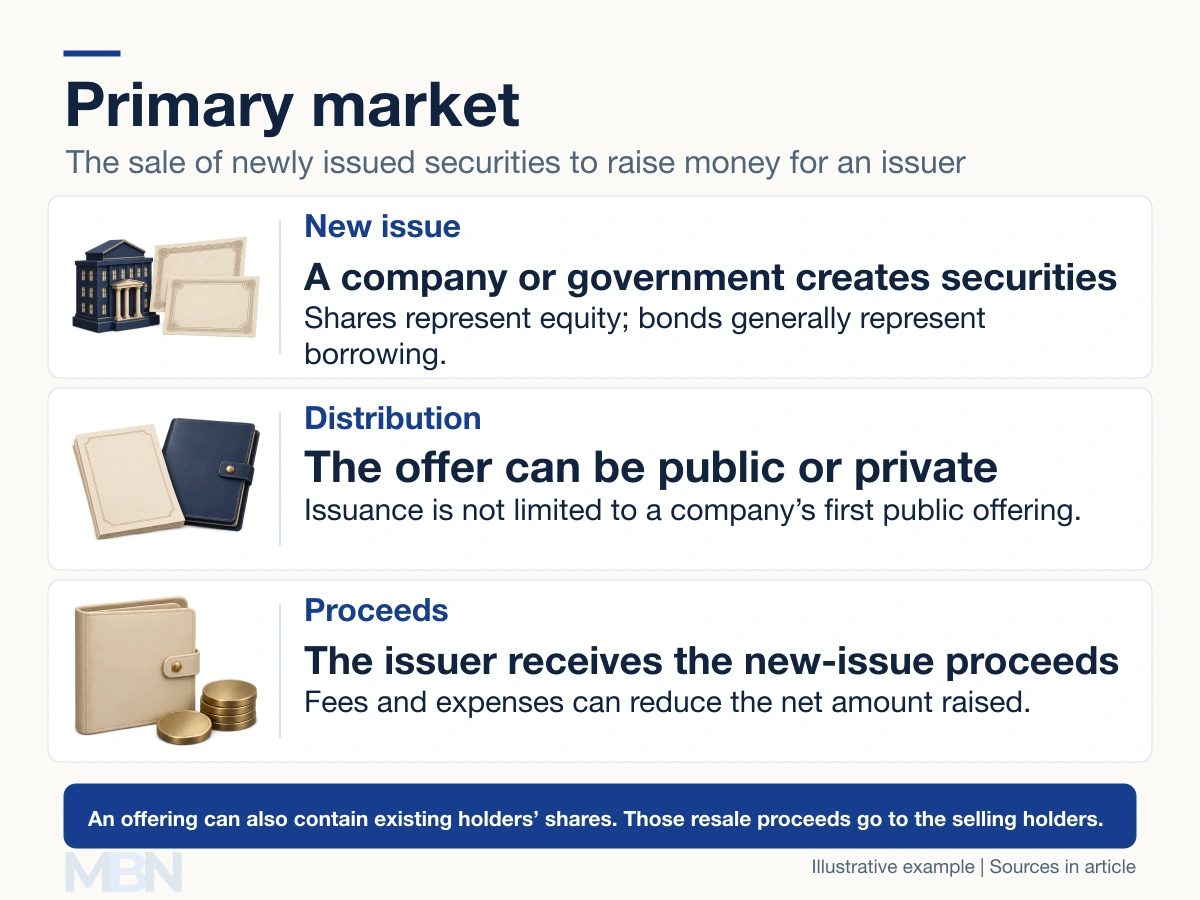
The primary market is where newly issued securities are sold to investors and the issuer receives the proceeds. Companies can raise equity by issuing shares or borrow by issuing bonds. Governments also raise money through new debt securities.
A security is a financial instrument such as a share or bond. Shares represent an ownership interest; bonds generally represent a debt claim with stated terms. The primary market concerns issuance, while the secondary market concerns resale of securities already issued.
Primary issuance can be public or private
The SEC’s primary-market definition focuses on newly issued securities and the issuer receiving proceeds. It is not limited to sales to the general public.
Examples include a company’s initial public offering, or IPO, a later issue of new shares, a rights issue to existing shareholders, a corporate bond sale and a private placement. A private placement offers securities through a route exempt from public registration, subject to applicable conditions.
In the United States, securities offerings generally must be registered or qualify for an exemption. The SEC explains the main capital-raising pathways. Requirements differ by jurisdiction and offering type.
How an issue reaches investors
An issuer determines the security’s terms and chooses a distribution route. Investment banks or other intermediaries can help with structuring, pricing, underwriting and allocation. An underwriter may buy securities for resale or arrange sales, depending on the agreement.
Not every issue uses the same mechanism. US Treasury securities are sold through auctions; TreasuryDirect describes announcement, bidding and issuance. Other securities may use negotiated pricing or a bookbuilding process that collects investor demand.
The issue price can therefore reflect market conditions. Calling a transaction primary-market issuance does not mean its price is set without reference to supply, demand or competing investments.
Who receives the money?
New-issue proceeds go to the issuer, with underwriting discounts and other costs reducing the net amount available. The offering documents explain the intended use of that money.
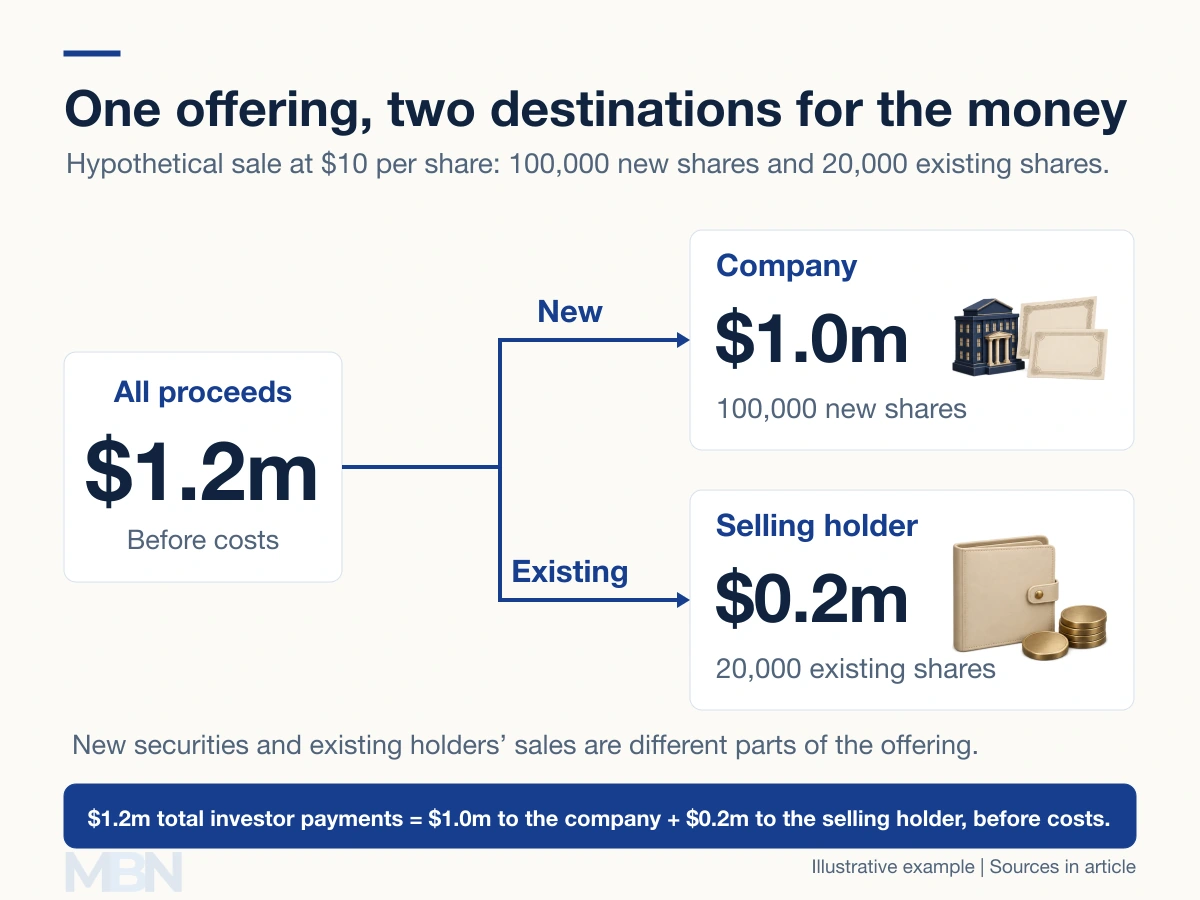
An IPO or later public offering can also include existing shareholders selling their own shares. The SEC’s IPO bulletin explains that their proceeds go to those selling shareholders, rather than the company.
Suppose investors buy 100,000 newly issued shares and 20,000 existing shares at $10 each. Their total payment is $1.2 million. Before costs, the company receives $1 million and the selling holder receives $200,000.
What happens after issuance?
If an investor later sells the shares to another investor, that payment normally goes to the seller. It does not raise fresh capital for the original issuer. A later issue of additional new shares is a separate primary-market transaction.
Resale conditions vary. Some newly issued securities have transfer restrictions or limited trading. An issue does not guarantee a liquid secondary market, a rising share price or repayment of a bond.
In ordinary commercial language, “primary market” can also mean a business’s main customer market. That usage differs from the financial meaning of new-security issuance.
Last checked and updated on November 11, 2026 by the MBN editorial team.