
The cash ratio compares a company’s most liquid resources with its current liabilities. It provides a narrow snapshot of short-term financial coverage, rather than a guarantee that every bill will be paid on time.
This article uses cash and cash equivalents in the numerator. Definitions vary: CFA Institute’s financial-ratio list includes cash and short-term marketable investments. Comparisons need a consistent definition, accounting date and treatment of restricted balances.
How is the ratio calculated?
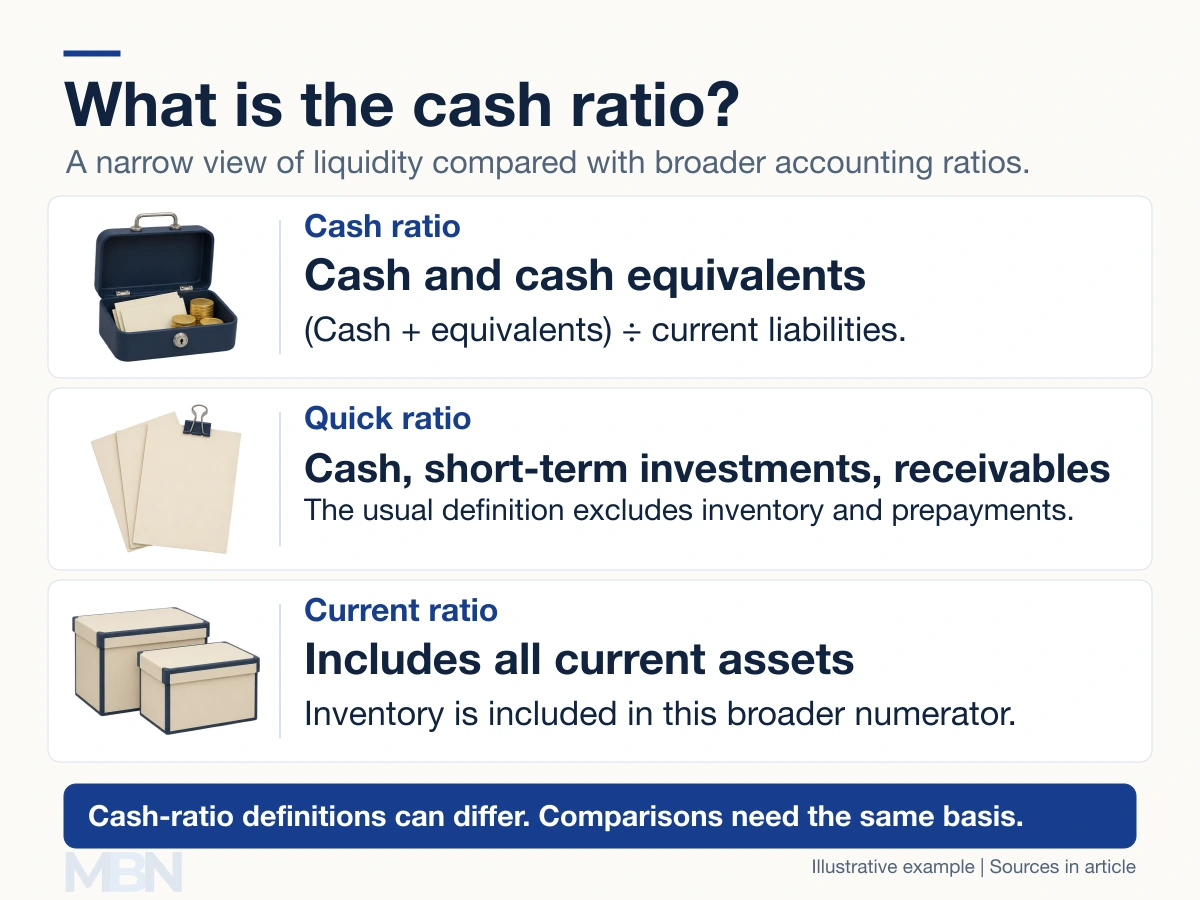
Cash ratio = (cash + cash equivalents) ÷ current liabilities.
The parentheses matter: the two asset amounts are added before division. The result is normally expressed as a ratio, such as 0.50, rather than as a monetary amount.
Current liabilities are short-term obligations, including items such as supplier balances and amounts due on borrowings. The SEC’s financial-statement guide distinguishes balance-sheet amounts from cash flows over a period. The ratio compares amounts at a particular reporting date.
What qualifies as a cash equivalent?
IAS 7 defines cash equivalents as short-term, highly liquid investments convertible to known cash amounts with insignificant risk of value changes. They are held to meet short-term cash commitments.
The standard says an investment normally qualifies with a maturity of about three months or less from acquisition. That is different from being able to sell an asset within 90 days. A long-term bond does not automatically become a cash equivalent merely because it is readily traded or approaches maturity.
Restrictions can also affect availability. An amount reported within cash may still be reserved for a specific purpose, so financial-statement notes matter when interpreting liquidity.
Two worked examples
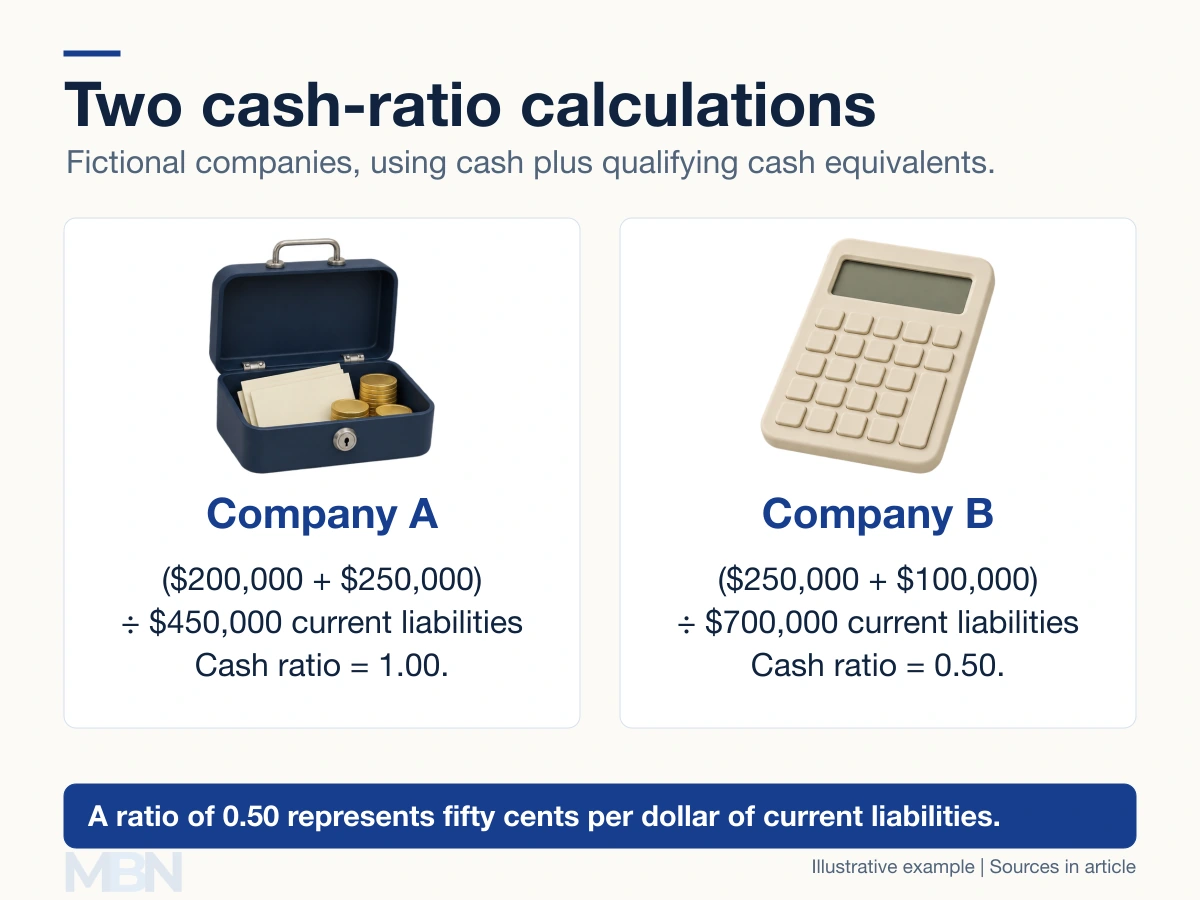
Company A has $200,000 cash, $250,000 qualifying cash equivalents and $450,000 current liabilities. Its ratio is ($200,000 + $250,000) ÷ $450,000 = 1.00.
Company B has $250,000 cash, $100,000 cash equivalents and $700,000 current liabilities. Its ratio is $350,000 ÷ $700,000 = 0.50, or fifty cents of these resources per dollar of current liabilities.
What does a high or low result mean?
A ratio below one means the selected resources are smaller than current liabilities at that date. It does not by itself prove insolvency: incoming operating cash, debt maturities and available financing also affect payment capacity.
A high ratio can reflect reserves, recent borrowing or cash held for future spending. It does not automatically prove inefficiency or establish that cash should be distributed as dividends.
The usual quick ratio adds short-term investments and receivables while excluding inventory. The current ratio includes all current assets. Each therefore answers a broader liquidity question than this cash-and-equivalents measure.
Last checked and updated on November 3, 2026 by the MBN editorial team.