
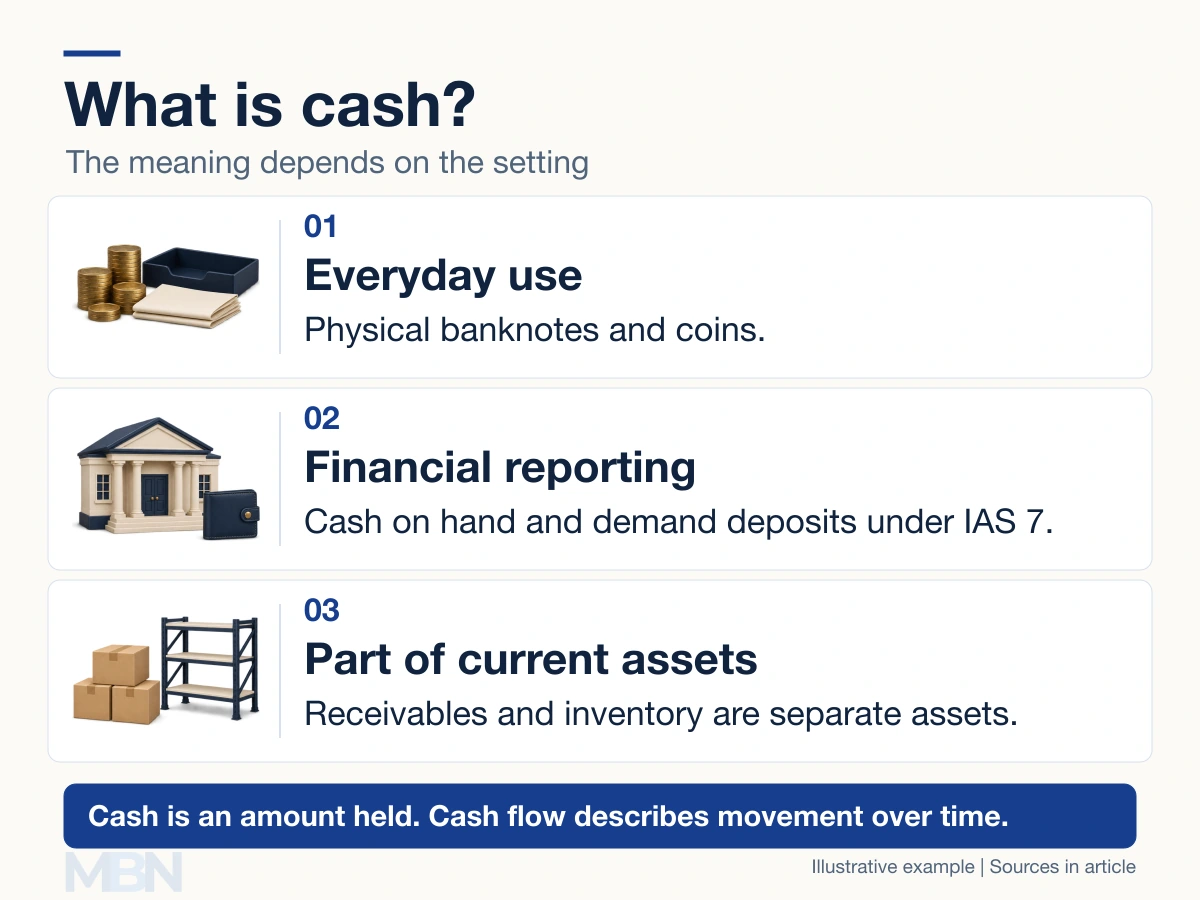
Cash usually means physical money, such as banknotes and coins. In financial reporting, it also includes demand deposits, which are bank balances accessible on demand.
Context determines the meaning. Paying “in cash” at a shop normally describes handing over notes or coins. A company reporting its cash balance may hold most of that amount in a bank account.
Cash in financial statements
The IFRS Foundation’s IAS 7 explanation defines cash as cash on hand and demand deposits. Cash equivalents are a related but separate category of short-term, highly liquid investments that meet specific convertibility and value-risk conditions.
Financial statements often combine the two under “cash and cash equivalents.” A cash equivalent is not every asset that could be sold quickly. Ordinary shares, for example, can be actively traded while carrying substantial price risk.
Cash is also not a synonym for all current assets. Current assets can include inventory, customer receivables and prepayments. A customer’s unpaid invoice is an amount owed to the business; it is not money already received.
A balance-sheet example
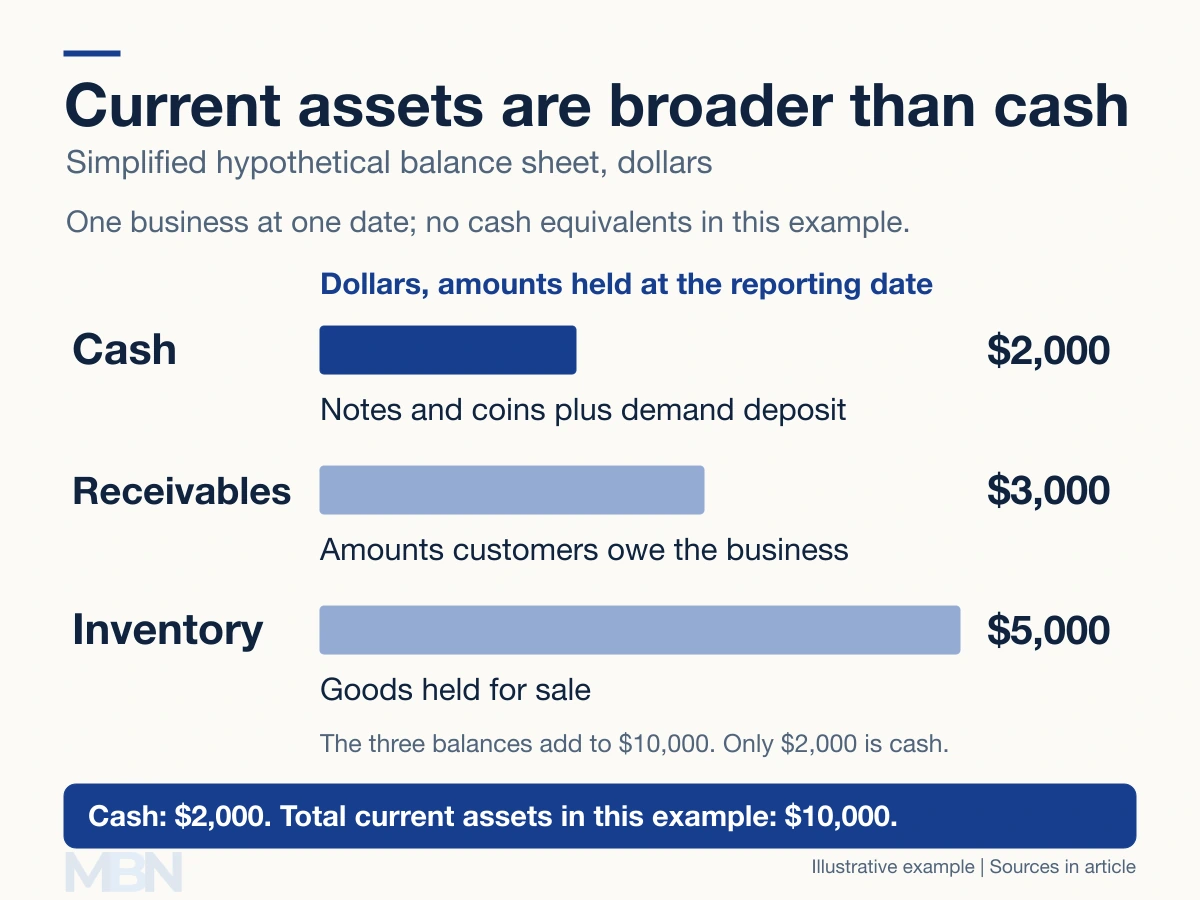
Suppose a hypothetical business holds $500 in notes and coins and $1,500 in a demand-deposit account. Its cash is $2,000. It also has $3,000 of customer receivables and $5,000 of inventory.
Those three categories total $10,000 of current assets in this simplified example. Calling the full $10,000 “cash” would overstate the amount immediately held as money by $8,000.
The SEC’s financial-statement guide explains how a balance sheet records assets and obligations at a particular date. Presentation rules depend on the reporting framework; every balance sheet is not required to start with cash.
Cash, profit and cash flow
Cash is a balance at a point in time. Cash flow records receipts and payments over a period. In a simple example, opening cash of $2,000 plus $1,500 received minus $1,000 paid leaves $2,500, assuming no other movements.
Profit measures income less expenses under the applicable accounting rules. It can differ from the change in cash because, for example, a sale may be recognized before a customer pays. A new loan brings in cash but does not turn the borrowed principal into sales revenue or profit.
Petty cash is a small controlled fund used for minor payments. “Cashing a check” means obtaining payment for a check, but funds becoming withdrawable should not automatically be treated as proof of final settlement.
Physical cash and electronic payments
The Bank of England explains that money includes electronic bank deposits as well as physical cash. Using a debit card normally transfers bank-deposit money; it does not require the customer to handle banknotes.
Payment habits differ by country and transaction. In the ECB’s 2024 euro-area consumer payment study, cash accounted for 52% of the number of point-of-sale transactions, down from 59% in 2022. That measures transaction counts in the surveyed setting, not the share of all wealth held in cash.
Cash used for payments and banknotes held as savings or reserves are different measures. The Bank of England’s research on banknote demand explains why fewer cash transactions need not mean an equivalent fall in the stock of notes held.
Last checked and updated on November 5, 2026 by the MBN editorial team.