
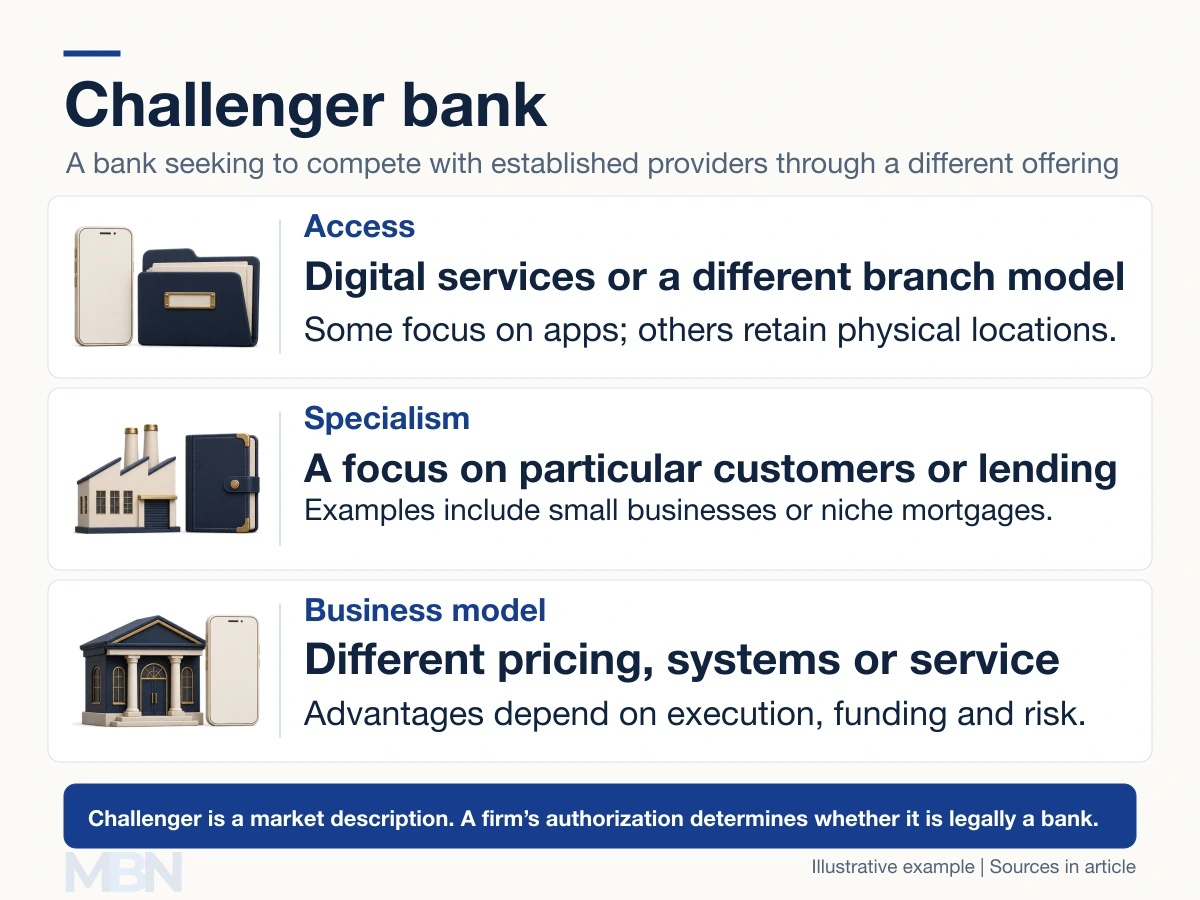
A challenger bank is a bank that seeks to compete with established providers through a different service, technology, product focus or business model. The term is widely used in UK banking, but it is a market description rather than a separate type of banking license.
Challengers may be newer or smaller than the largest banks, but neither age nor size alone defines them. Some operate mainly through apps, while others have branches or specialize in particular forms of lending.
How they compete
A digital-first bank may offer fast account opening, spending notifications or tools for managing money. A specialist lender may focus on small businesses or customers with borrowing needs that larger banks handle less directly.
For example, a business-focused challenger could combine a transaction account with invoicing tools, while a specialist mortgage bank could concentrate on a narrower lending market. These are different competitive approaches, not promises that either model will always be cheaper or more profitable.
Newer systems and fewer branches can reduce some costs. Against that, a smaller bank may face higher funding costs, customer-acquisition expenses, concentration risk and the cost of building effective controls. Established banks also invest in digital services.
Challenger, digital bank and neobank
A digital bank primarily describes a delivery model. “Neobank” is used inconsistently: it can refer to a licensed digital bank or to a nonbank financial app working with a partner institution. The underlying authorization matters more than the marketing label.
The Bank of England’s authorization process assesses a new bank’s business plan, financial resources, governance and risk management. New entry does not remove the need for prudential safeguards.
The FCA’s review of challenger-bank financial-crime controls excluded e-money issuers and payment-service providers from its bank sample. It also identified weaknesses at some reviewed firms, demonstrating why a modern interface does not establish the quality of controls.
Deposits and customer protection
For eligible deposits at a UK-authorized bank, the standard Financial Services Compensation Scheme limit is £120,000 per eligible person, per authorized firm, effective December 1, 2025. It applies to covered deposits rather than every financial product an app may offer.
Different brands can share a banking authorization. Suppose one eligible person holds £70,000 with each of two such brands, with no other deposits or special temporary-high-balance protection. The combined £140,000 is measured against one £120,000 standard limit, leaving £20,000 above it.
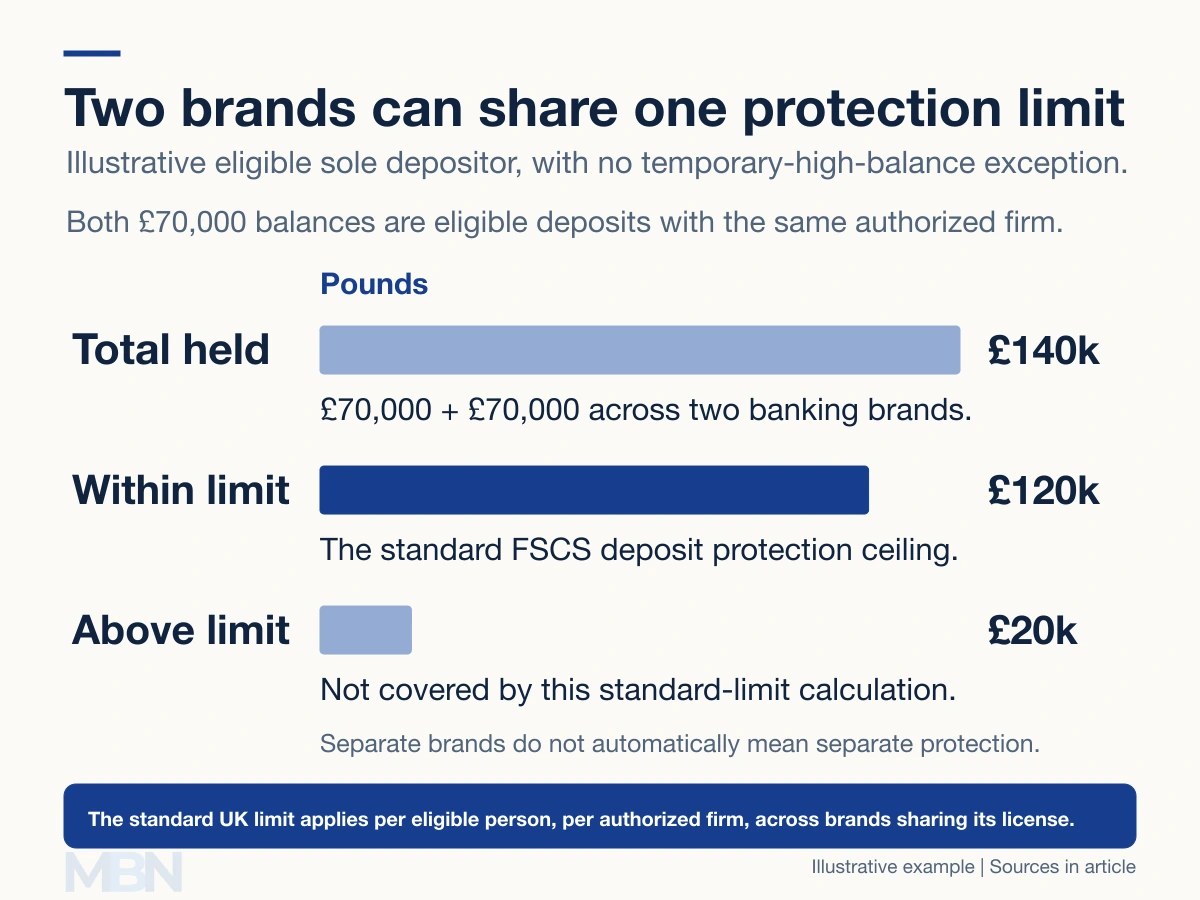
The FSCS explains shared licenses and their effect on coverage. A banking group and an authorized firm are not necessarily identical; the relevant authorization is the basis for this calculation.
An e-money account has a different legal structure. The FCA distinguishes safeguarding from bank deposit protection. An app’s name, appearance or use of the word “banking” does not itself determine which protection applies.
Competition without guaranteed outcomes
Challengers can broaden choice and encourage changes in pricing or service. Their performance still depends on deposit retention, lending quality, operational reliability, regulation and profitability. Market entry can be followed by expansion, merger, acquisition or failure, rather than a predetermined victory over larger banks.
Last checked and updated on November 11, 2026 by the MBN editorial team.