
Creative accounting is an informal term for using accounting choices, estimates, transactions or presentation to shape the impression given by financial statements. It is often used critically when reported results appear stronger or smoother than the underlying business justifies.
The term does not establish whether a practice is lawful. Some choices are permitted and properly supported. Others breach accounting requirements, omit material information or involve fraud. Describing conduct as creative does not make it legal.
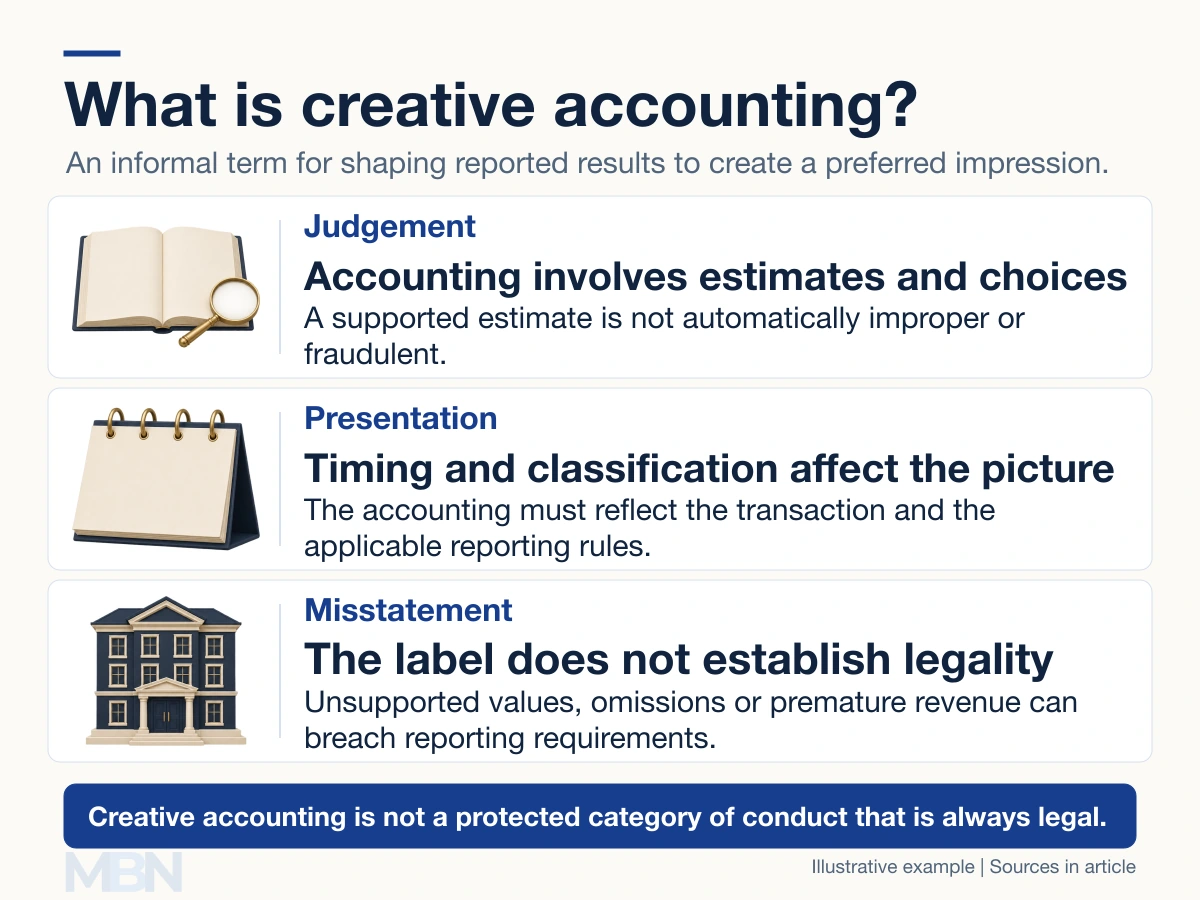
Judgement is necessary, but it needs support
Accounts contain estimates, such as an asset’s useful life or amounts unlikely to be collected from customers. An estimate can change when the evidence changes. The existence of judgement does not give management an unrestricted choice of the number it prefers.
In the UK, Companies Act 2006 section 393 requires directors to be satisfied that accounts give a true and fair view before approving them. The Financial Reporting Council explains that material information can be misstated or obscured through presentation as well as omitted.
A technically complicated transaction is not necessarily improper. Equally, a simple omission can be seriously misleading. The relevant questions concern its substance, the evidence and the reporting requirements.
An invoice does not automatically create revenue
Issuing an invoice before a reporting date does not, by itself, justify recognising a sale. Under IFRS 15, revenue is recognised when the relevant performance obligation is satisfied. That means transferring the promised goods or services to the customer, either at a point in time or over time.
Consider a fictional business paid £1,200 on January 1 for one annual support service delivered evenly over 12 months. Assume the service is recognised over time and there are no other obligations or adjustments.
By March 31, three months have been delivered. Revenue is £1,200 × 3 ÷ 12 = £300. The other £900 represents services still owed, recorded as a contract liability. The revenue standard distinguishes such obligations from amounts already earned.
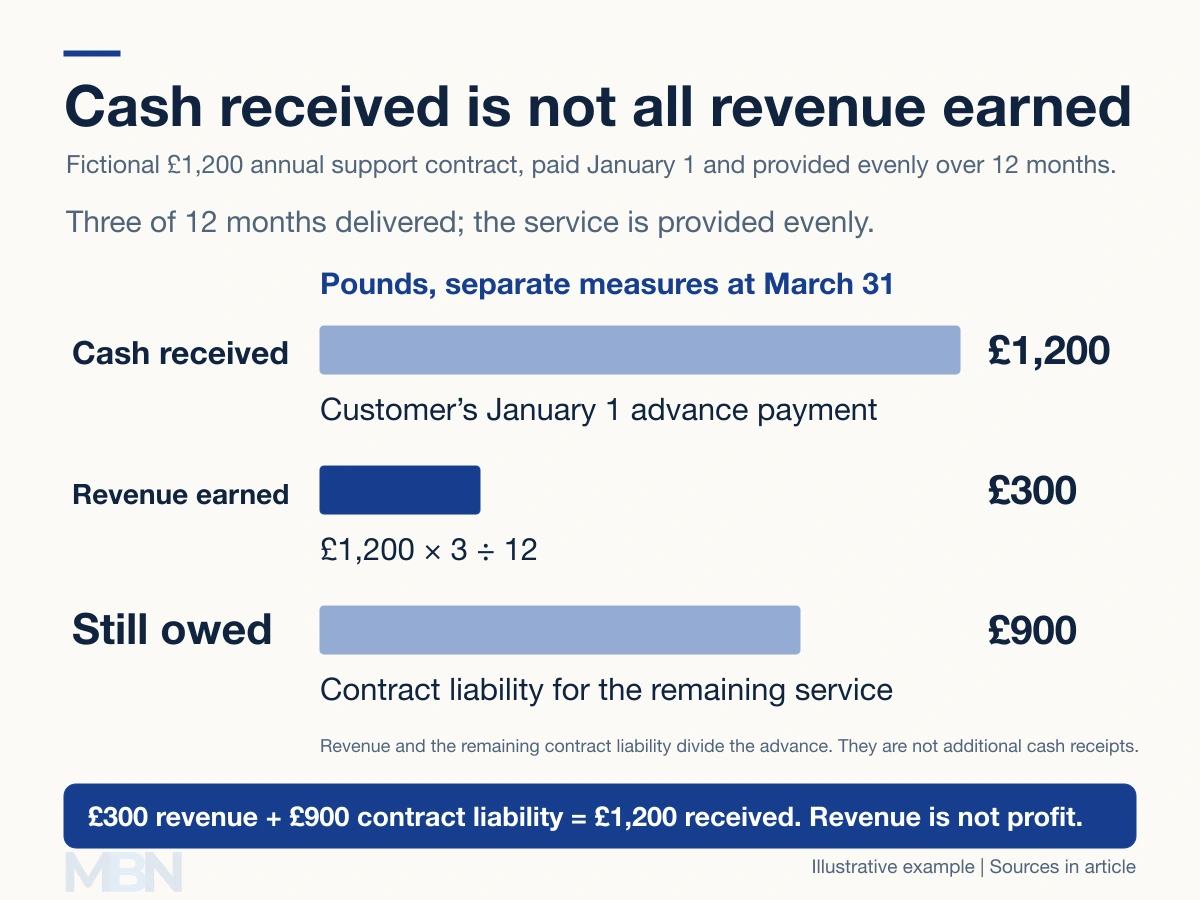
Recording all £1,200 as first-quarter revenue would overstate revenue by £900 under these assumptions. It would not establish first-quarter profit: costs must also be accounted for.
Property values depend on the reporting framework
It is incorrect to say every property must always remain at its purchase price or that any upward revaluation is acceptable.
IAS 16 permits a cost model or a revaluation model for property, plant and equipment. The chosen policy applies to an entire asset class. Revaluations require sufficient regularity, and the cost model includes accumulated depreciation and impairment where applicable. Different rules can govern investment property.
An unsupported optimistic valuation is different from a properly applied revaluation policy. A higher book value also does not, by itself, mean the company received cash.
Related terms need care
Earnings management describes efforts to influence reported earnings; income smoothing aims to reduce reported fluctuations. Window dressing usually concerns making a reporting-date position appear more favourable. None of these labels guarantees compliance.
Financial engineering is broader. It can describe legitimate design of financial products or financing arrangements, so it should not be treated as a synonym for falsifying accounts.
Last checked and updated on November 4, 2026 by the MBN editorial team.