
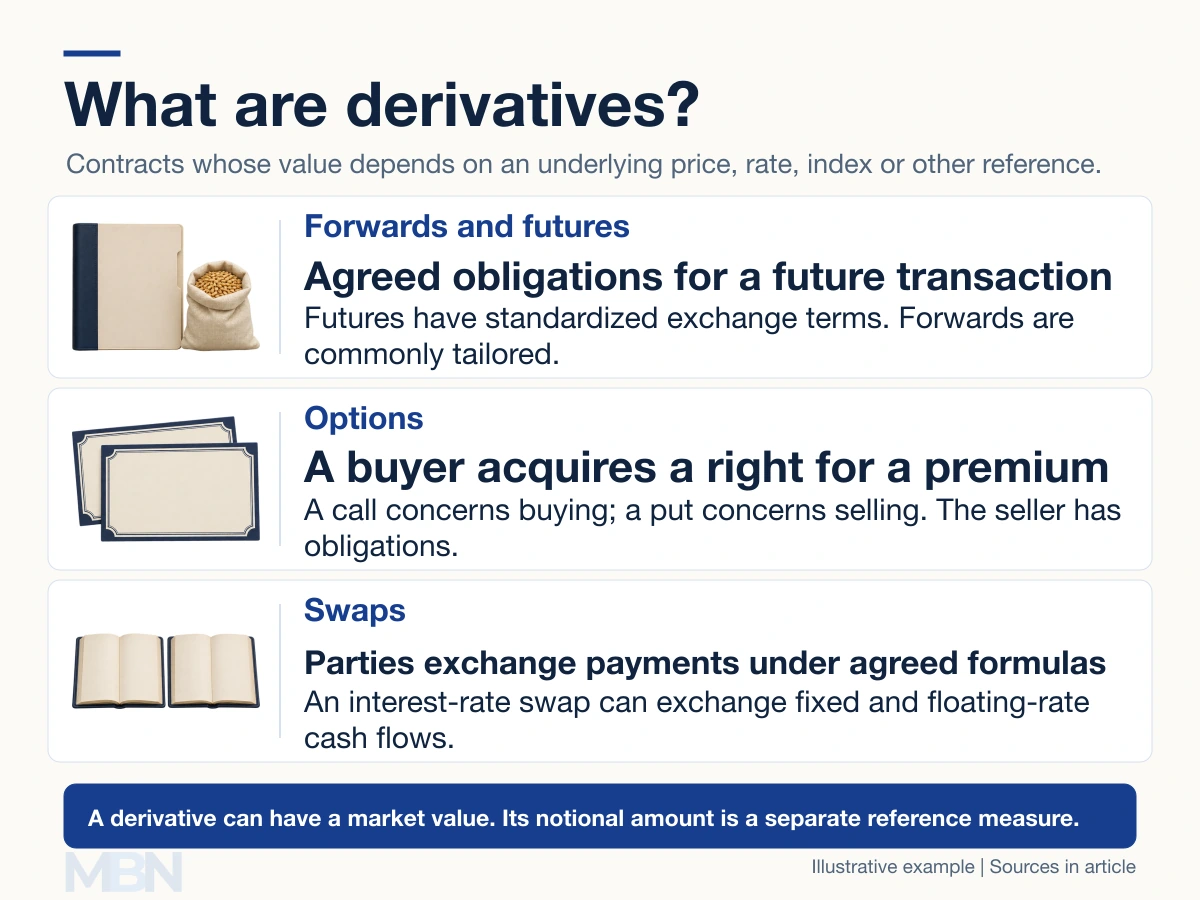
Derivatives are financial contracts whose values depend on an underlying asset, price, rate, index or other reference. Examples include forwards, futures, options and swaps. They can transfer particular risks without transferring ownership of the underlying asset.
References can include commodity prices, exchange rates, interest rates, shares and credit events. A derivative can have a positive or negative market value. Saying it is worthless simply because its value is derived from something else is incorrect.
Forwards and futures create obligations
A forward commonly sets a price and future date for a transaction between parties. A futures contract has standardized exchange terms and clearing arrangements. The CFTC’s futures explanation distinguishes these obligations from option rights.
Contracts may call for physical delivery or cash settlement. A position may also be offset before expiry. Futures gains and losses are typically settled through margin accounts as prices change; the initial margin is not the full purchase price of the underlying exposure.
Options give the buyer a right
A call gives its buyer the right to buy, and a put the right to sell, at an agreed strike price under the contract. Cash-settled options instead pay the specified settlement amount. The buyer pays a premium; the seller takes the corresponding obligation.
The SEC’s options bulletin explains exercise, assignment and premiums. Expiry and exercise style matter. A purchased option can expire worthless, while some uncovered option-selling strategies can generate very large or unlimited losses.
A futures and call-option example
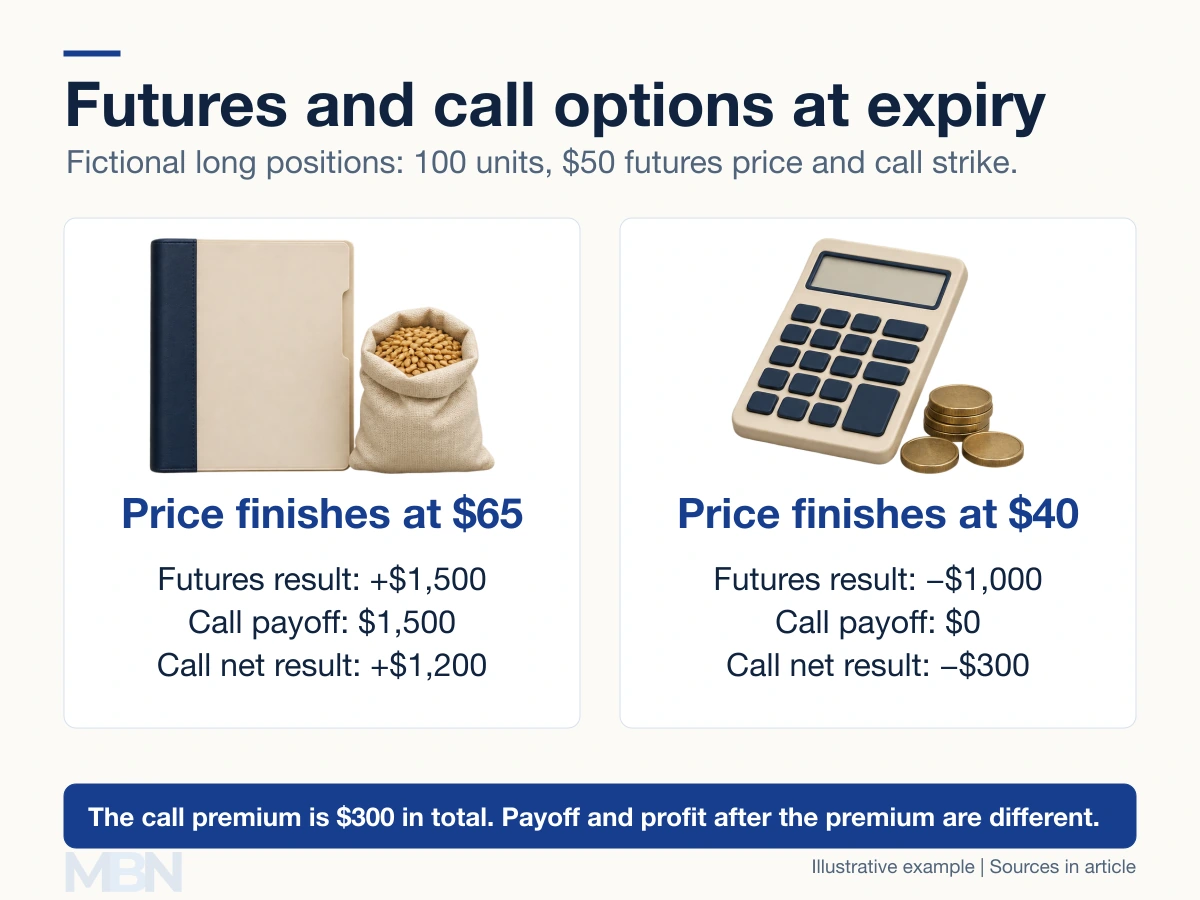
Assume two separate fictional long positions covering 100 units: a cash-settled futures position entered at $50 per unit, and a cash-settled call with a $50 strike and a $3 premium per unit. Ignore fees, financing and margin-funding costs.
At an expiry price of $65, the futures result is ($65 − $50) × 100 = $1,500. The call payoff is also $1,500, but subtracting its $300 premium leaves $1,200.
At $40, the futures result is −$1,000. The call’s payoff is zero, leaving a $300 loss from its premium. The buyer’s choice and premium make an option different from a futures obligation.
Swaps exchange defined cash flows
A swap exchanges payments using agreed formulas. For example, an interest-rate swap can exchange fixed-rate payments for payments based on a floating benchmark, calculated on a notional principal. The CFTC glossary describes swaps and other derivative contracts.
Notional is a reference for calculating obligations, not automatically the contract’s market value or maximum loss. The BIS distinguishes notional amounts from replacement market values. Whether principal changes hands depends on the contract.
Uses and remaining risks
Hedgers seek to reduce an existing exposure; speculators deliberately take exposure. A hedge may be imperfect because quantities, timing or reference prices differ. Derivatives also carry counterparty, liquidity, leverage and operational risks.
ASIC’s Moneysmart explains that futures losses can exceed the initial deposit. Clearing and collateral reduce some risks but do not make trading risk-free. Exchange and over-the-counter markets both exist, and legal treatment differs between derivative products; not all derivatives are securities.
Last checked and updated on November 4, 2026 by the MBN editorial team.