
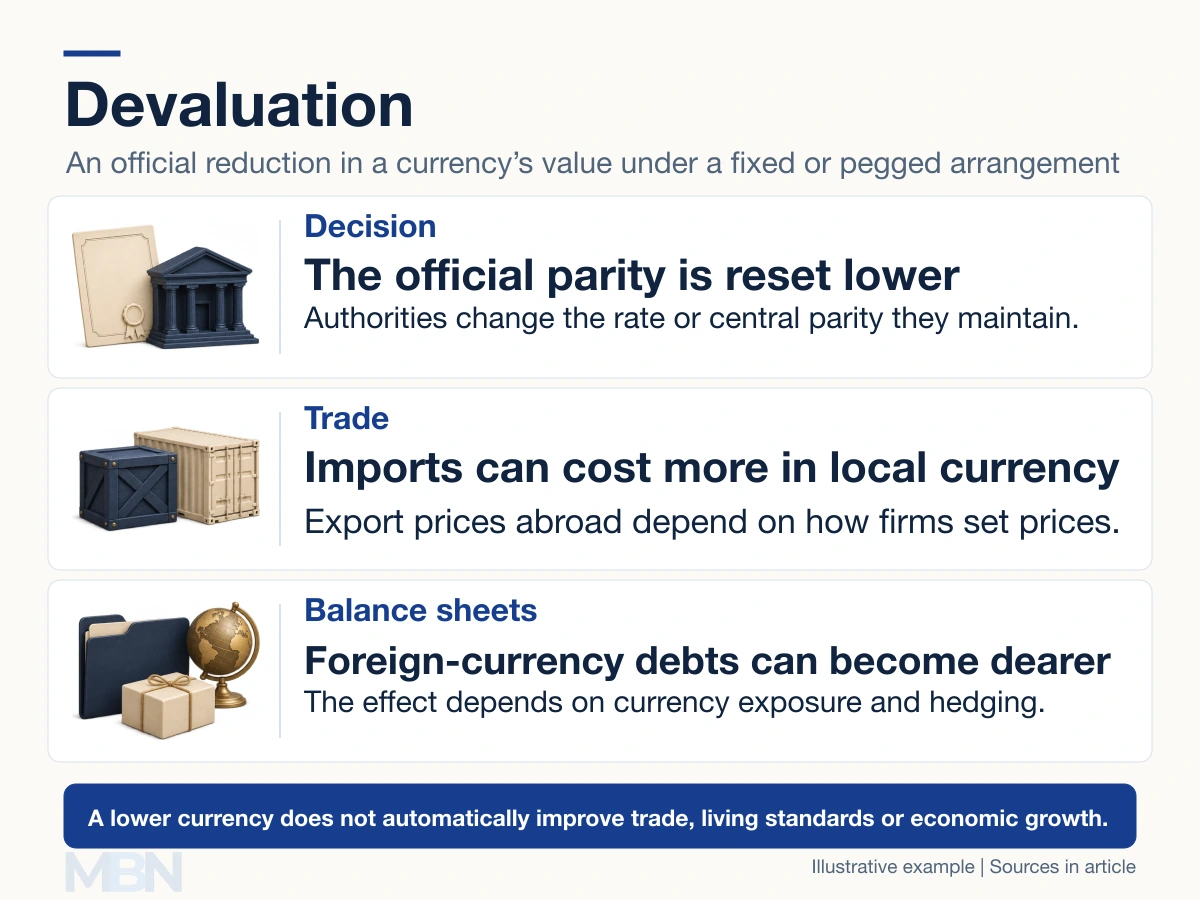
Devaluation is an official reduction in a currency’s value against another currency or a currency basket under a fixed or pegged exchange-rate arrangement. Authorities reset the parity, meaning the official rate they undertake to maintain. The opposite adjustment is a revaluation.
A devaluation changes an exchange rate. It does not directly reduce the number printed on a banknote or cancel part of a domestic bank balance. Its economic effects arise through prices, purchasing power, trade and financial exposures.
Devaluation and depreciation
Depreciation describes a fall in a currency’s market value. Under a floating exchange rate, that value responds to supply and demand, including expectations about interest rates, inflation and economic conditions.
Devaluation refers more specifically to an official downward reset. The IMF explains pegged arrangements as commitments to maintain a rate or band against an anchor currency. Actual arrangements include adjustable pegs, crawling pegs and managed floats, so a simple division into permanently fixed and completely free currencies misses important cases.
A government or central bank can influence a floating currency through policy or intervention without declaring a new official parity. A resulting market fall is normally called depreciation rather than formal devaluation.
A worked exchange-rate example
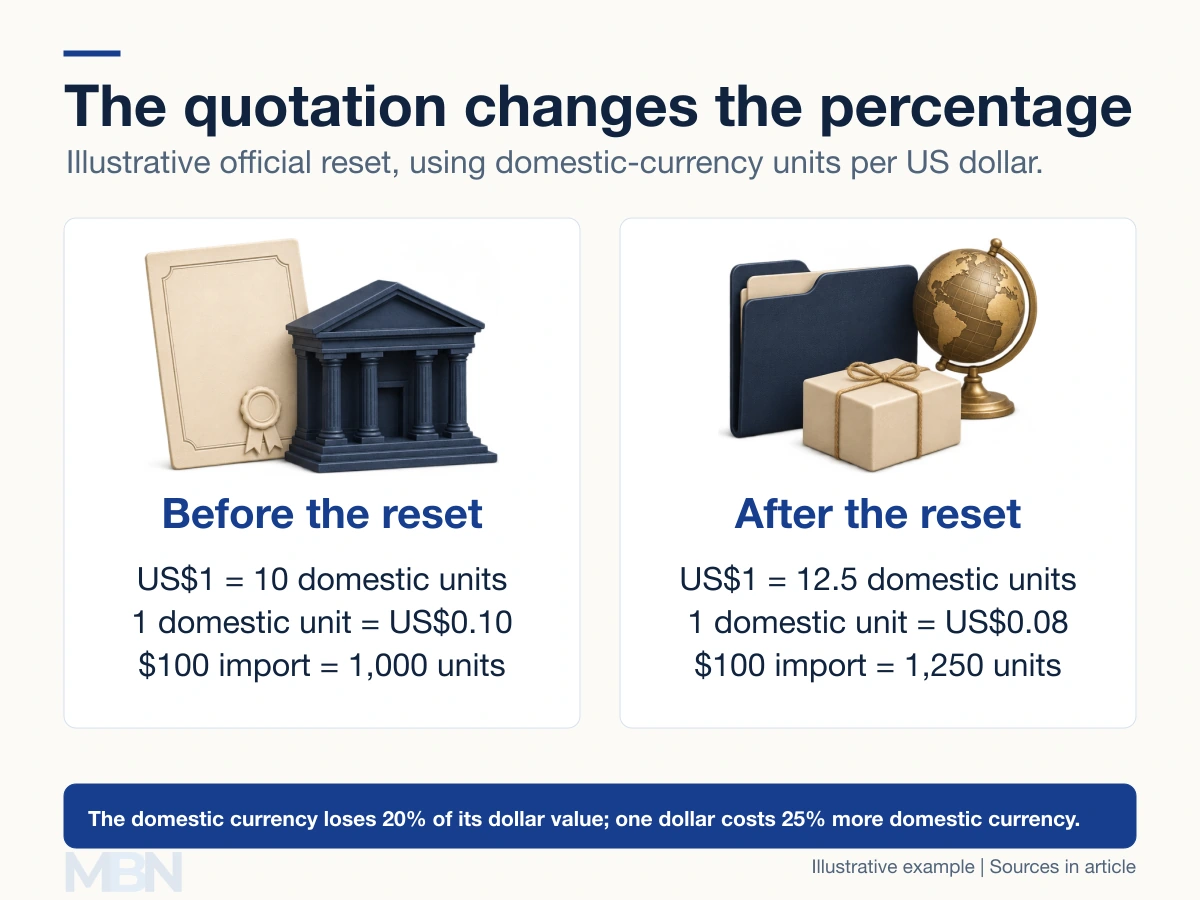
Suppose the official rate changes from 10 to 12.5 domestic-currency units per US dollar. A domestic unit previously bought $0.10; it now buys $0.08. Its dollar value has fallen 20%.
Viewed the other way around, the domestic price of one dollar has risen 25%. An unchanged $100 import now costs 1,250 domestic units instead of 1,000, before taxes, transport or other charges. Always state which way an exchange rate is quoted.
Why exports do not automatically surge
If an exporter keeps its domestic-currency price unchanged, a foreign buyer may pay less after devaluation. But firms may instead hold foreign-currency prices steady, use imported inputs or face capacity constraints.
IMF research on trade invoicing shows why the currency used to set prices affects the response. Contracts, demand and production lead times also matter. Import volumes may adjust slowly even as the import bill rises, so the trade balance can initially worsen rather than improve immediately.
Inflation, debt and purchasing power
Higher import costs can feed into consumer prices and businesses’ input costs. Households may lose purchasing power, particularly where fuel, food or equipment are imported. Devaluation does not inevitably cause hyperinflation.
A borrower owing dollars but earning domestic currency needs more local money to service the same dollar debt. Foreign-currency income or hedging contracts can offset some exposure. The RBA discusses these balance-sheet and inflation risks.
Whether output or employment improves depends on the economy’s trade structure, financial exposures and accompanying policies. The RBA’s exchange-rate explanation describes several channels, rather than a guaranteed growth dividend.
Last checked and updated on November 11, 2026 by the MBN editorial team.