
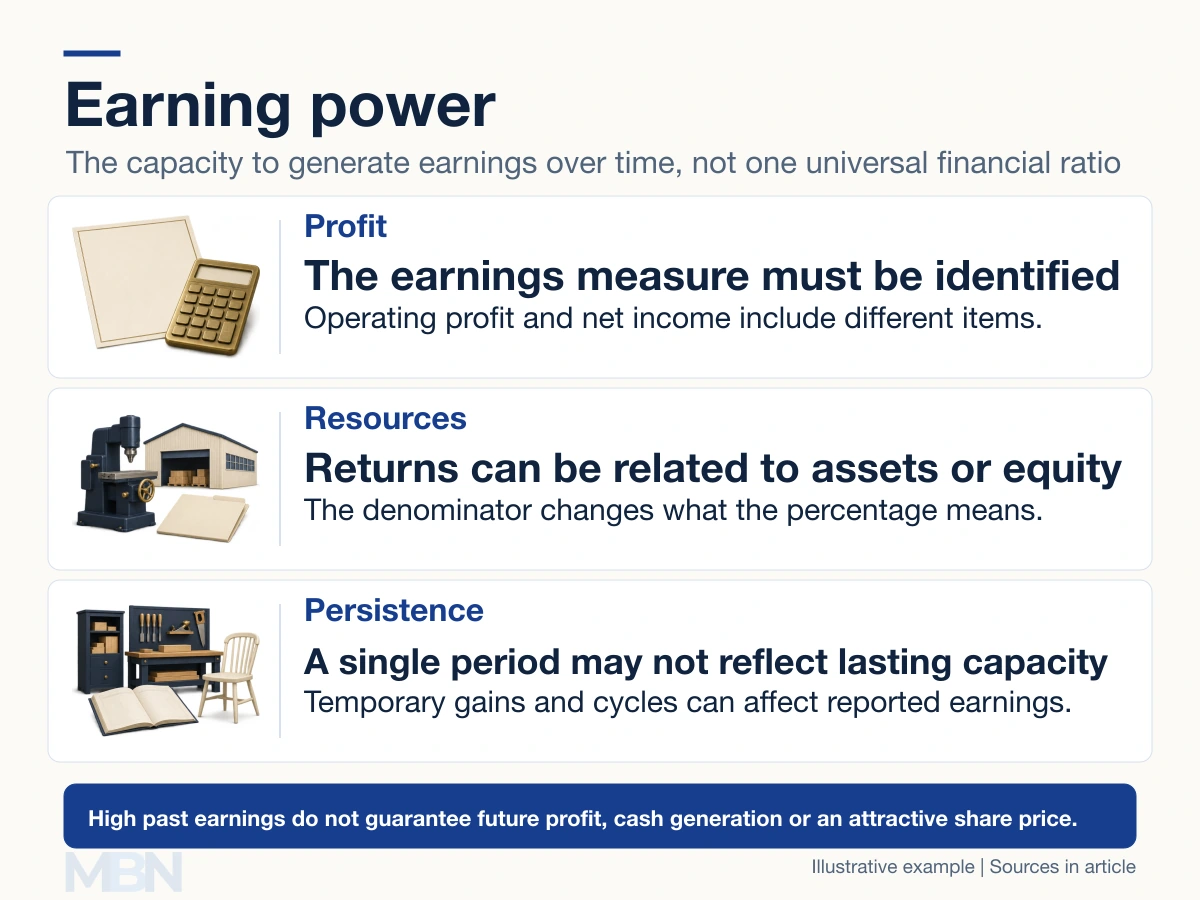
Earning power is the capacity to generate earnings over time. For a company, it usually concerns the ability of its business activities and resources to produce profit. For a person, it can describe the capacity to earn income. It is not the name of one universally defined calculation.
Analysts assess the amount, sources and persistence of earnings, as well as the resources and risk involved. A high profit in one year can reflect a lasting business advantage, a temporary price rise or a one-time gain.
The basic earning power ratio
A specific measure called the basic earning power ratio divides earnings before interest and taxes, or EBIT, by total assets, usually expressed as a percentage. Iowa State University lists that formula in its financial-ratios guide.
For example, $1.6 million of annual EBIT divided by $20 million of total assets gives 8%. An analysis using average assets should identify that variation and use the same basis for comparisons. A year-end asset balance and an average balance can produce different answers.
Operating profit measures income from operations after operating costs. Net income also reflects relevant financing, tax and non-operating items. EBIT and operating profit can differ when non-operating items remain in earnings; the SEC’s guidance distinguishes EBIT from the operating-income starting point. The numerator should not be described simply as net income with every other effect removed.
Return on assets and return on equity
A common return on assets, or ROA, formula is net income divided by average total assets. Return on equity, or ROE, commonly divides the relevant net income by average book shareholders’ equity. OpenStax explains these profitability ratios. Other conventions exist, so the earnings and capital definitions should be explicit.
Suppose a company earns $1 million in a year and has average total assets of $20 million. ROA on that net-income basis is 5%. If opening equity is $12 million and closing equity is $14 million, a simple average is $13 million.
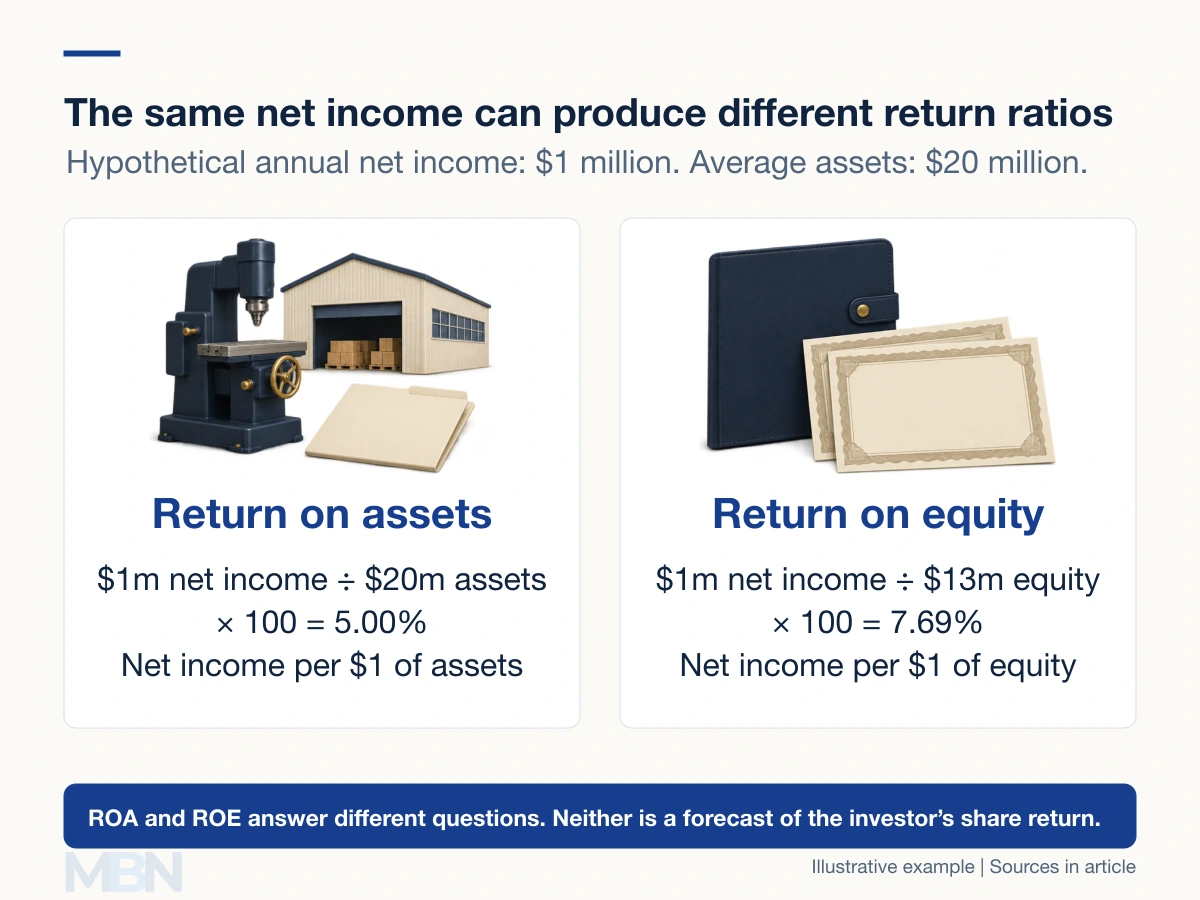
ROE is $1 million ÷ $13 million × 100 = approximately 7.69%. That is a return on accounting equity, not the shareholder’s stock-market return or the business’s overall earning power reduced to one number.
A simple opening-and-closing average may be inadequate after a major acquisition, disposal or share issue. More frequent balances can better represent resources employed during the year. Profit and capital must cover the same entity and ownership interests.
Why a higher ratio needs explanation
Borrowing can reduce the share of assets financed by equity and affect ROE. A share repurchase can also reduce the equity denominator. Neither change automatically means the underlying operation has become more profitable.
The NYU Stern accounting primer discusses how book values and financing affect profitability measures. An asset-heavy manufacturer and a service business with few recognized assets can have very different ratios even when both are profitable.
Very small or negative equity can make ROE difficult to interpret. Depreciation methods, asset age, acquired goodwill and the treatment of internally developed resources can also affect comparisons.
Lasting earnings, reported earnings and cash
Assessment of lasting earning capacity can separate recurring operations from unusual items and consider a business cycle rather than one peak year. Damodaran’s discussion of normalizing earnings explains the assumptions involved. A normalized figure remains an estimate, not a guaranteed recovery.
Profit also differs from cash generation. Receivables, inventory, capital spending and debt payments affect cash available. Removing a cost from an adjusted earnings measure does not remove the business’s need to fund it.
Valuation adds another question: the price paid for expected future earnings. Strong earning power does not, by itself, establish that a share is cheaply priced or that a borrower can meet every payment when due.
Last checked and updated on November 11, 2026 by the MBN editorial team.