
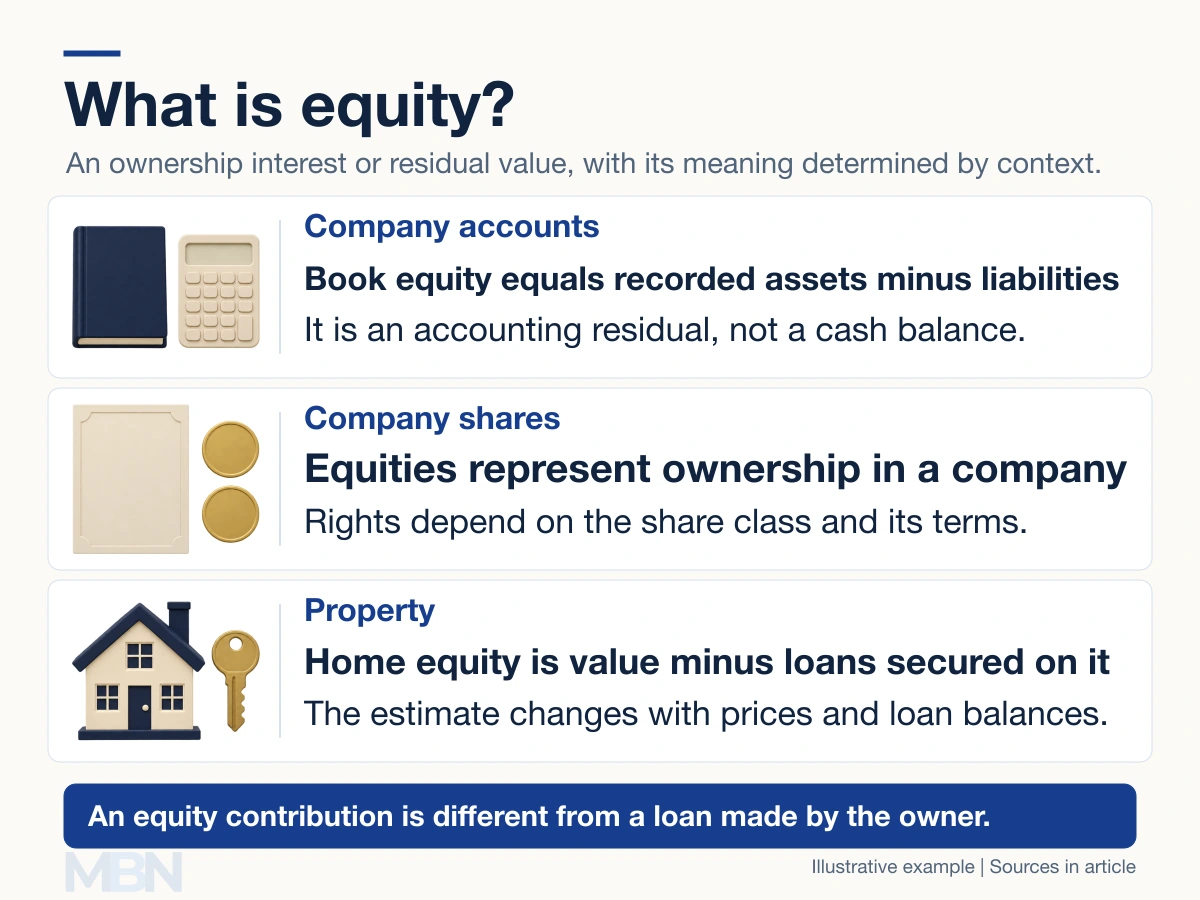
Equity is an ownership interest. In company accounts, it is the residual value of recorded assets after liabilities are deducted. In a house, it is the property’s estimated value minus the loans secured on it.
The context matters. Shares, accounting equity and home equity are related ideas, but their values are measured differently. The IFRS Conceptual Framework defines equity as the residual interest after liabilities.
How does company equity work?
Assets = liabilities + equity. Rearranging gives equity = assets − liabilities. The SEC’s financial-statement guide explains this balance-sheet relationship.
A fictional company with $400,000 of recorded assets and $250,000 of liabilities has $150,000 of book equity. This is not a separate pot of cash. Its assets could include equipment, inventories and customer receivables.
An owner’s contribution in exchange for equity is recorded separately from liabilities. If the owner instead lends money to the company, the loan can be a liability. The transaction’s terms determine the treatment.
Is book equity the same as market value?
No. Book equity uses amounts recognised in the accounts. Market capitalization generally multiplies outstanding shares by their current market price. NYU Stern’s financial definitions distinguish book values from market equity.
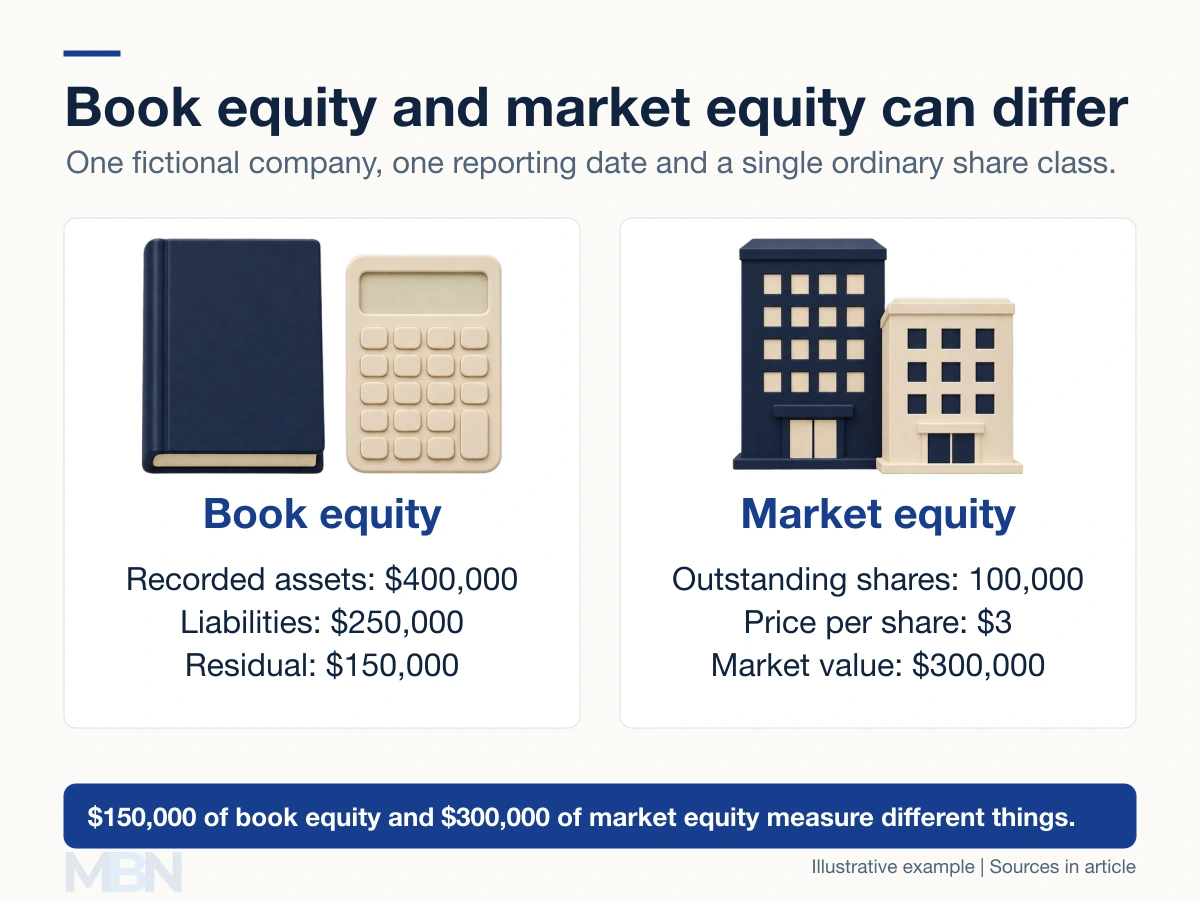
If the company has 100,000 outstanding ordinary shares trading at $3 each, their market value is $300,000. That can coexist with $150,000 of book equity. Neither is a promise of the proceeds from selling all the company’s assets.
What rights does a shareholder have?
A share represents an ownership position in a corporation. Dividend and voting rights depend on the share class and its terms. Owning shares does not guarantee a dividend or give unrestricted control over company assets.
Investor.gov distinguishes common and preferred shares. Preferred shares often have priority over common shares for dividends and liquidation distributions, while voting rights can differ. Common shareholders receive a liquidation distribution only if value remains after higher-priority claims.
How is home equity calculated?
The Consumer Financial Protection Bureau defines home equity using property value and outstanding mortgage debt. A $400,000 home with $300,000 of loans secured on it has estimated equity of $100,000 before selling costs.
If its value falls to $280,000 while those loans remain $300,000, equity becomes negative $20,000. Equity can change because of prices, additional borrowing or principal repayments.
Property equity is not immediately spendable cash. Selling or borrowing against it involves separate transactions, costs and conditions. In everyday language, equity can also mean fairness, a distinct use from financial ownership.
Last checked and updated on November 3, 2026 by the MBN editorial team.