
In business reporting, earnings usually means a company’s profit, or net income, over a stated period. It reflects recognized revenue and other income less expenses and losses, including relevant interest and taxes. A loss occurs when the resulting amount is negative.
The word also describes a worker’s pay in everyday language. In company accounts, identify the measure being discussed: net income, earnings per share and adjusted earnings are related but different figures.
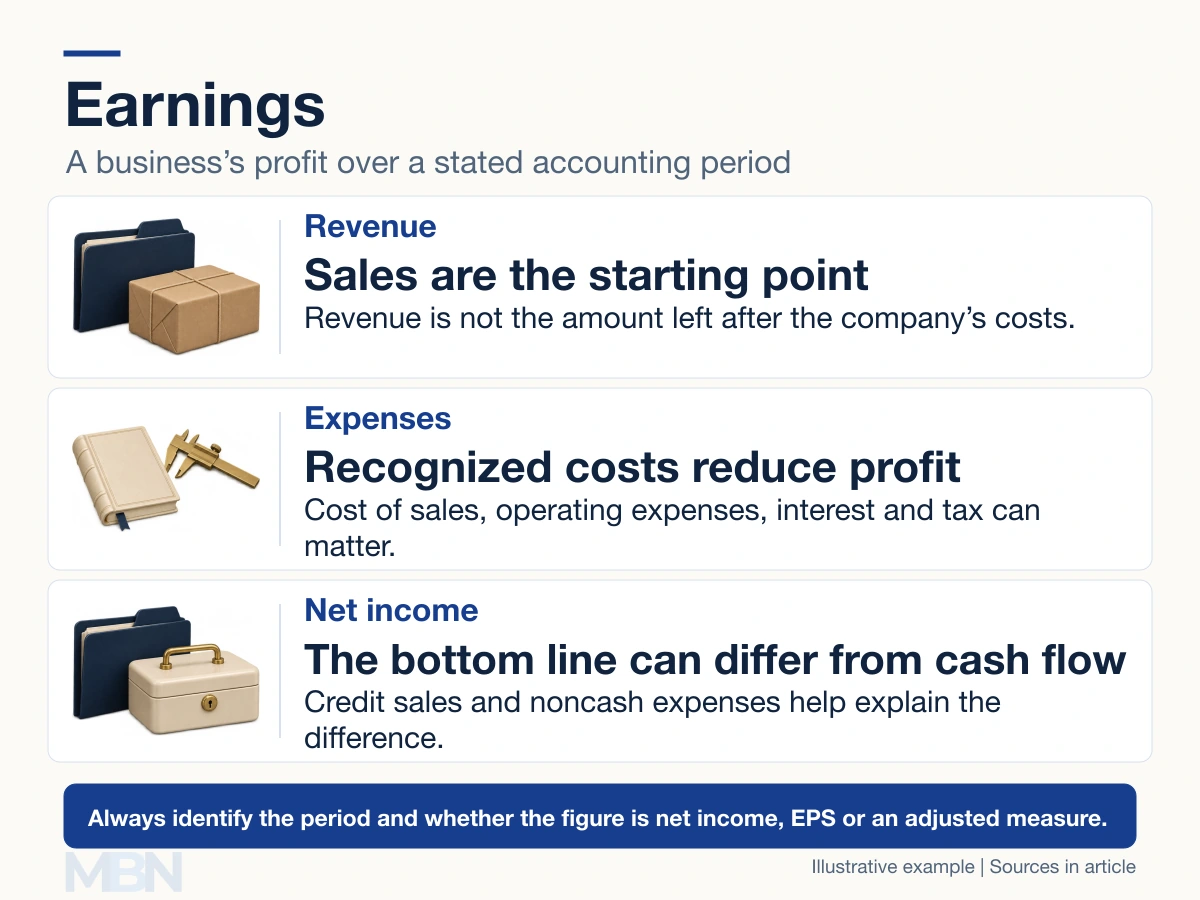
How earnings differ from revenue and cash
Revenue generally measures sales before the costs of running the business are deducted. Net income is the bottom line after the relevant expenses and other items. The SEC’s financial-statement guide explains how the income statement builds from revenue to profit or loss.
Earnings are not necessarily cash received. Under accrual accounting, a credit sale may be recognized before the customer pays. Depreciation spreads an asset’s cost over its useful life without requiring a matching cash payment each period. Cash-flow statements help explain these differences.
A simple earnings example
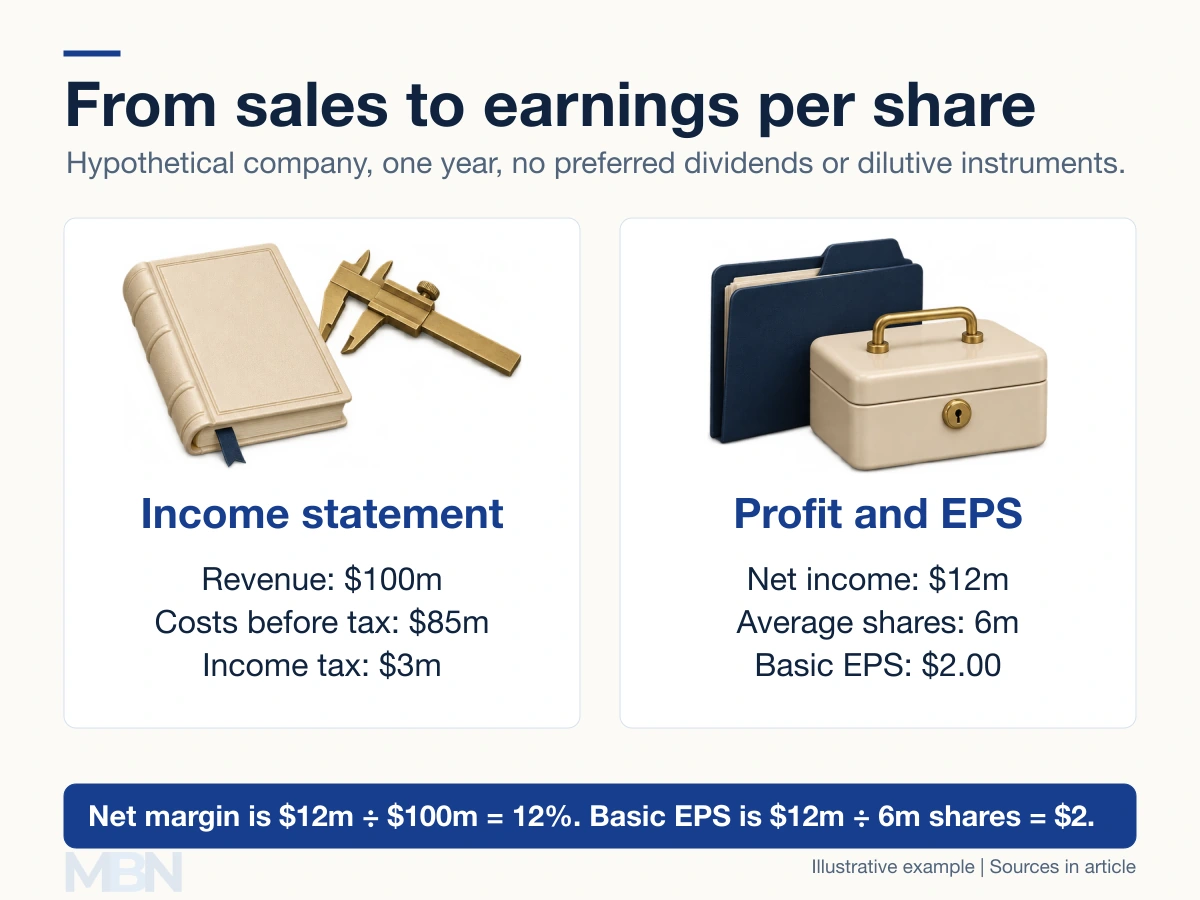
Suppose a company reports $100 million in annual revenue, $85 million in costs before tax and $3 million in income tax, with no other items. Net income is $100 million minus $85 million minus $3 million, or $12 million. Its net profit margin is 12%.
If $12 million is available to common shareholders and weighted-average common shares outstanding are six million, basic earnings per share, or EPS, is $2. Using the weighted average matters when shares are issued or repurchased during the period.
IAS 33 distinguishes basic from diluted EPS. Diluted EPS considers potential common shares, such as qualifying options or convertible securities, when their effect is dilutive. It is not simply net profit divided by the number of shares on the final day of the year.
EBIT, EBITDA and adjusted earnings
EBIT means earnings before interest and taxes. EBITDA means earnings before interest, taxes, depreciation and amortization. Neither is interchangeable with net income or operating cash flow. Excluding a cost from a performance measure does not remove the underlying economic obligation.
Adjusted earnings may exclude items chosen by management. Definitions can differ between companies and periods. The SEC’s non-GAAP guidance addresses misleading adjustments and reconciliation to comparable figures prepared under generally accepted accounting principles, or GAAP. Read that reconciliation rather than assuming an adjusted figure is more informative.
What earnings can and cannot show
Earnings help describe profitability, but a single quarter does not establish a durable trend. Asset sales, tax changes, impairment charges and accounting estimates can affect the result. Research spending can reduce current profit without guaranteeing a successful future product.
An earnings announcement can move a share price, but beating an analyst estimate does not guarantee a rise. Expectations, valuation, forecasts and other information also matter. A loss-making business may grow successfully or continue losing money.
The Investor.gov guide to reading company filings explains the value of financial-statement notes, management discussion and risk disclosures. Those provide context for the headline profit figure and the judgments behind it.
Last checked and updated on November 11, 2026 by the MBN editorial team.