
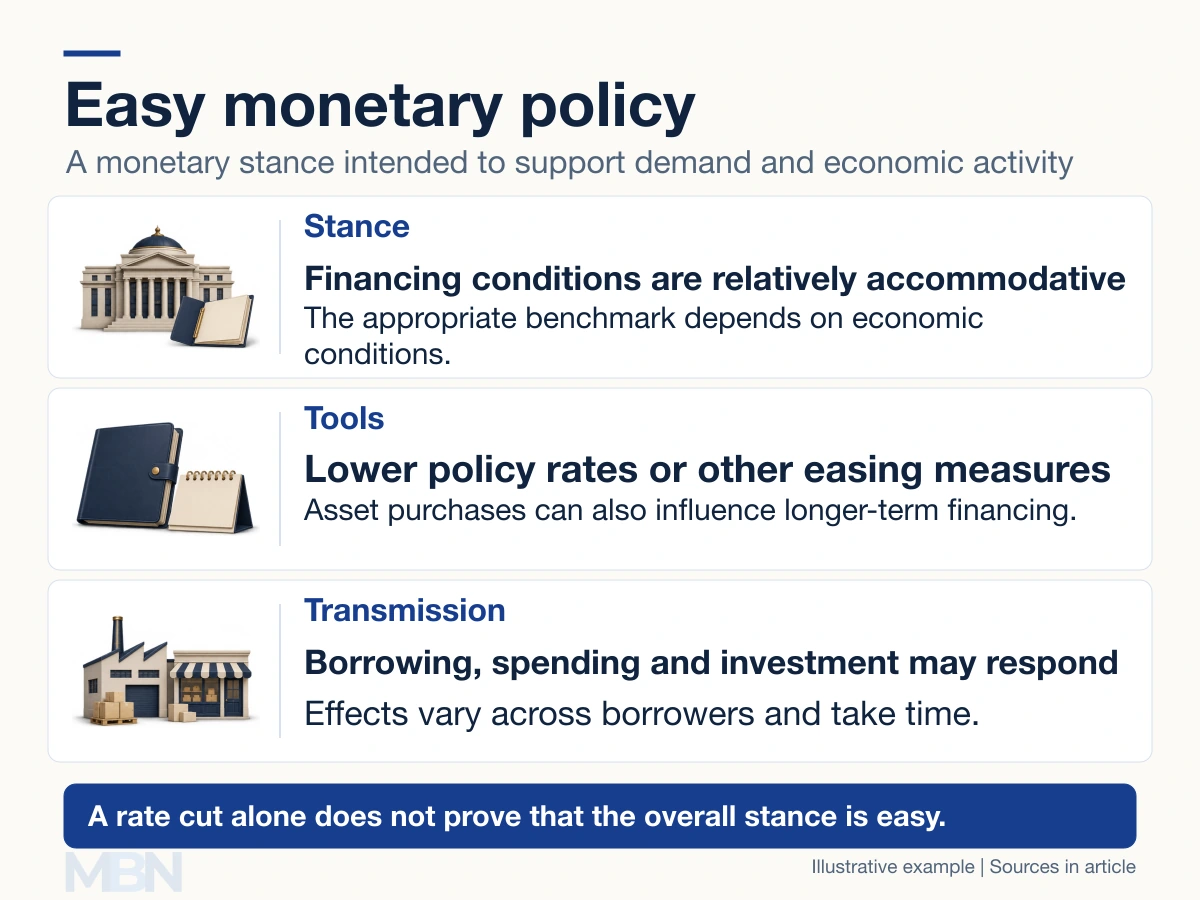
Easy monetary policy is an accommodative central-bank stance intended to support spending, investment and economic activity. It can involve relatively low policy interest rates or other measures that ease financing conditions.
Easy money policy, accommodative policy and expansionary monetary policy are related expressions. They describe the direction or stance of monetary policy, rather than a guarantee that borrowing will be cheap or available to everyone.
Easy policy is different from a rate cut
Easing means reducing restraint or adding support. The resulting policy stance can still be restrictive. For example, cutting a very high rate may leave borrowing conditions tight relative to what the economy needs.
One benchmark is the neutral interest rate, an estimated rate consistent with neither stimulating nor restraining the economy under specified conditions. It is not directly observable or permanently fixed. The Cleveland Fed explains why estimates of neutral rates matter when assessing the stance.
Which tools can central banks use?
Policy rates: A lower official rate can influence money-market rates, bank lending and deposit rates, and expectations of future financing costs. The change does not pass through equally to every product or borrower.
Asset purchases: Quantitative easing, or QE, involves central-bank purchases of assets such as bonds using newly created central-bank reserves. The Bank of England explains how purchases can affect bond prices, longer-term yields and wider financing conditions.
Communication: Guidance about future policy can influence expectations. Credibility and the conditions attached to that guidance matter. The tools and legal framework differ between central banks.
QE is an asset purchase, rather than the same transaction as government spending or handing a loan directly to every household. The existence of more bank reserves does not by itself establish how much new credit customers will receive.
Why expected inflation matters
A nominal interest rate is the quoted rate. An expected real rate adjusts it for expected inflation over a comparable period. A common approximation is nominal interest minus expected inflation, as the St. Louis Fed explains.
Suppose the nominal rate falls from 5% to 4%, while expected inflation falls from 4% to 2%. The approximate real rate rises from 1% to 2%. These are hypothetical matching-horizon rates, not current policy figures.
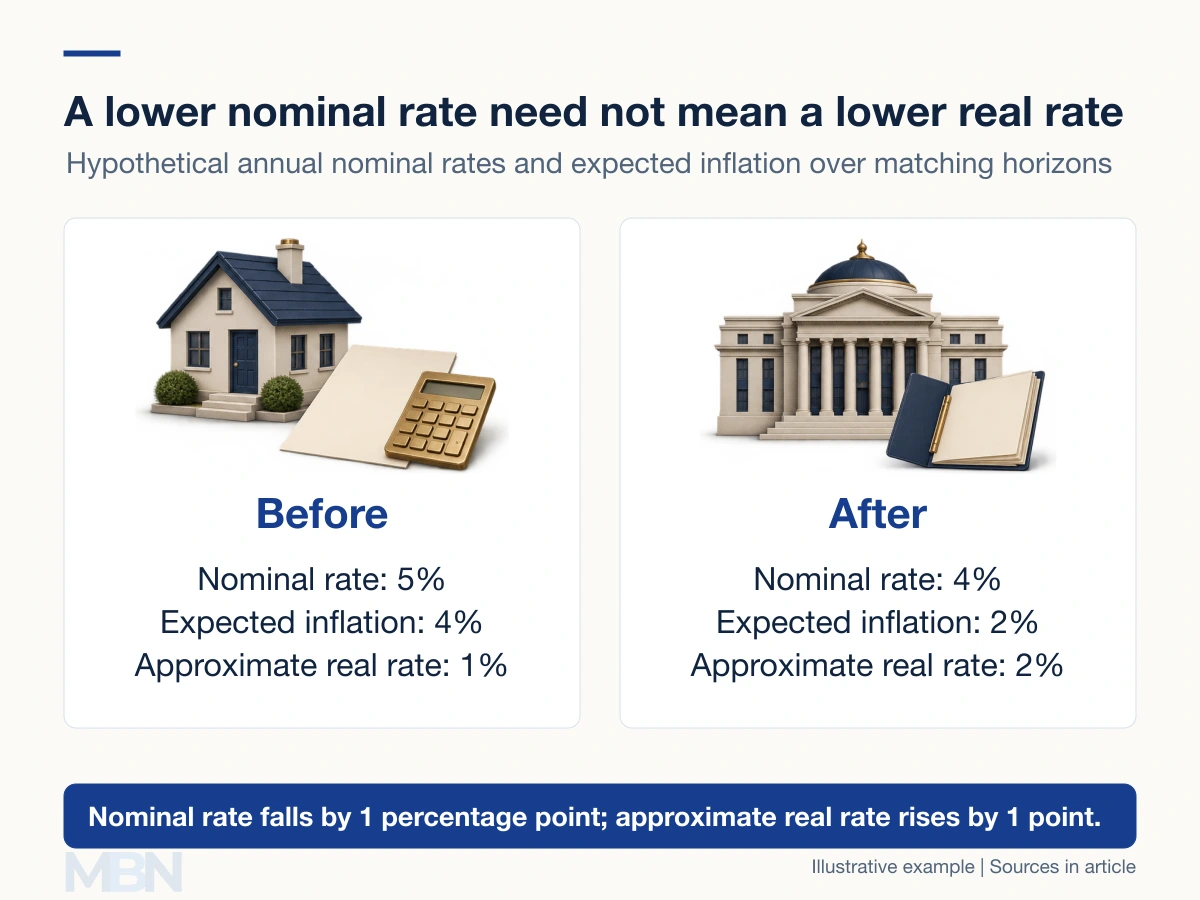
This example does not prove the overall policy stance has tightened: the neutral rate and other financial conditions can also change. It shows why looking only at a nominal rate cut can miss part of the picture.
How can easier policy affect the economy?
Lower financing costs can make some purchases and investment projects more attractive. Policy can also affect asset values, exchange rates and the availability of credit. Changes in spending then influence production, employment and price pressures.
These are channels, not automatic steps. A firm facing weak sales may postpone expansion despite a cheaper loan. A borrower may be unable to obtain finance if its lender tightens approval standards. Existing fixed-rate borrowers may see no immediate payment change.
The European Central Bank describes transmission as having long, variable and uncertain lags. The timing and size of the response depend on conditions in the economy and financial system.
Do stock prices always rise?
No. Lower discount rates can support asset values, all else equal, but prices also reflect expected earnings, risk and what investors had already anticipated. A cut associated with a worsening outlook need not produce a stock-market gain.
Monetary policy is not a reliable rule for predicting an individual share’s return. Market prices can react before an announcement or move differently from the initial expectation.
What are the trade-offs?
Easier conditions can help address weak demand or inflation below the central bank’s objective. If demand is stimulated beyond the economy’s capacity, inflation pressures can increase. Prolonged low financing costs can also encourage risk-taking and leverage, meaning greater use of borrowing.
Conversely, too much restraint can weaken activity. Policymakers weigh these risks against their mandate and changing evidence. They do not simply alternate mechanically between cheap and tight money, and a growing money measure alone cannot establish the eventual inflation outcome.
Last checked and updated on November 10, 2026 by the MBN editorial team.