
Economic analysis examines how resources are used and how choices affect costs, benefits, behavior or wider economic outcomes. It can concern a household, business, project, market or whole economy.
The purpose might be to explain an observed change, forecast demand or compare alternatives. A company’s profit is one possible measure, but economic analysis is broader than reviewing its accounts or cutting its spending.
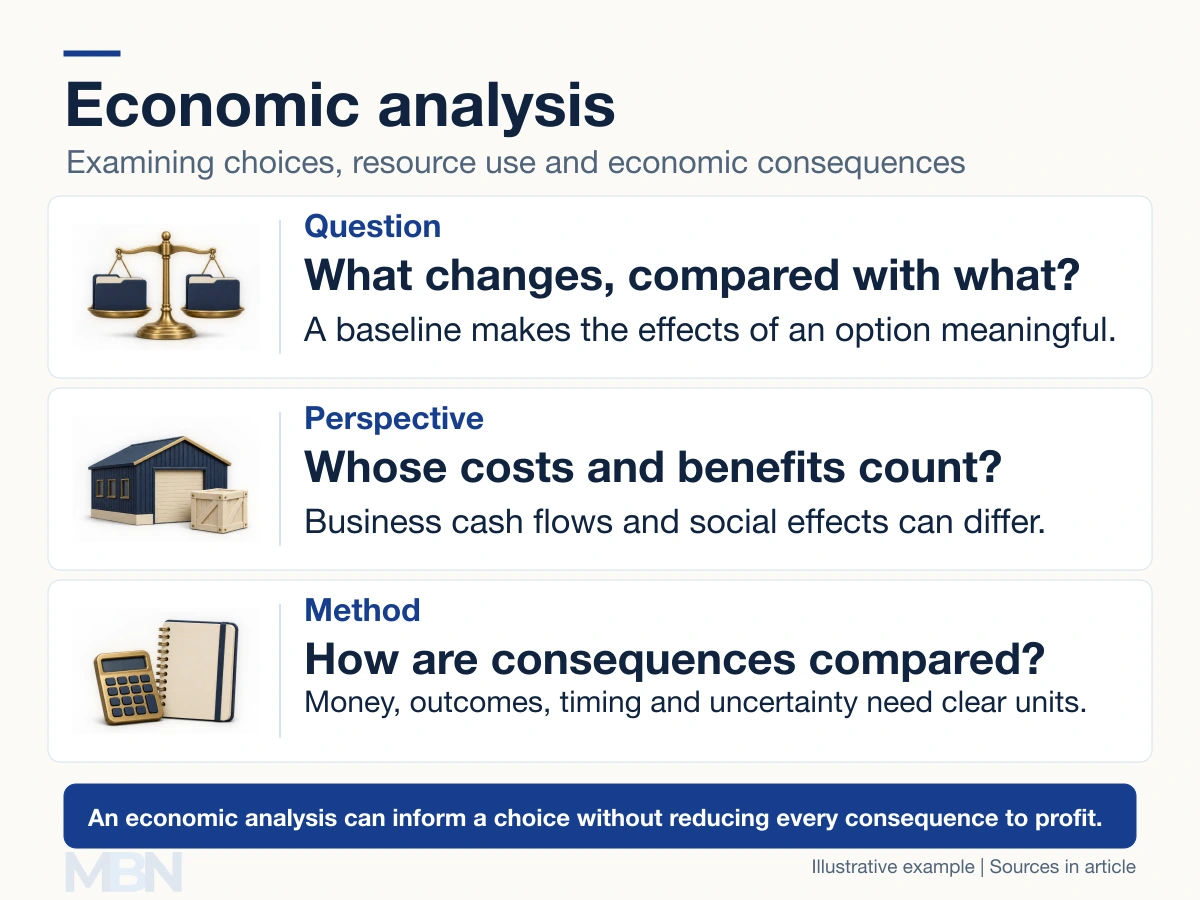
Start with a comparison and a perspective
A project appraisal compares an option with a baseline, such as continuing the existing operation. Only changes attributable to the option belong in that comparison. A wider feasibility study also considers whether an option can be delivered technically, legally and operationally.
Financial analysis examines cash flows and affordability for an organization. A social economic appraisal considers effects on the population within its stated scope, including consequences that do not appear in the organization’s accounts. HM Treasury’s Green Book provides an official framework for public appraisal.
Opportunity cost is the value of the best alternative forgone. An owned building can therefore have an economic cost even without a new rent payment, if using it prevents a valuable alternative use. Unrecoverable past spending is a sunk cost; it does not change with the new decision.
Cost-benefit analysis
Cost-benefit analysis compares relevant benefits and costs in monetary terms, with later amounts discounted to a common present value. Some effects are difficult to value, so limitations and unmonetized consequences also need to be visible.
Consider a hypothetical project costing $10,000 immediately and producing net cash inflows of $5,000 at the end of each of the next two years. Assume there are no other costs, benefits or resale proceeds.
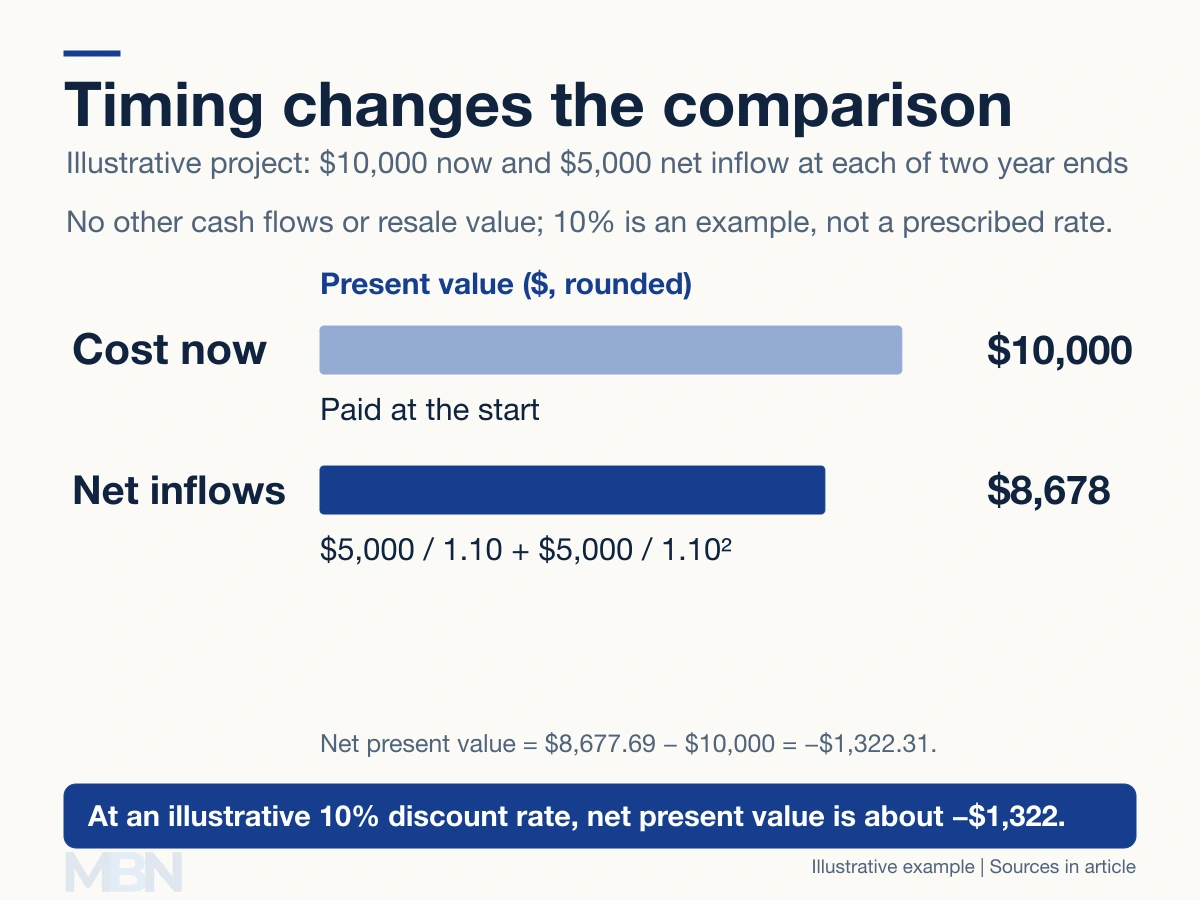
The undiscounted inflows total $10,000. At an illustrative 10% annual discount rate, their present value is $5,000 ÷ 1.10 + $5,000 ÷ 1.10² = $8,677.69. Net present value is therefore −$1,322.31.
This example explains the effect of timing, not an investment recommendation. Another rate, useful life or set of consequences changes the calculation. Inflation assumptions and the discount rate also need to be consistent.
Cost-effectiveness analysis
Cost-effectiveness analysis relates costs to outcomes measured in a common non-monetary unit. The CDC describes its use in comparing interventions affecting the same health outcome. The general distinction is that the outcome is not converted into a monetary benefit.
For a hypothetical business comparison, suppose option A costs $12,000 and prevents 600 comparable defects, while B costs $15,000 and prevents 1,000. Average costs are $20 and $15 per defect prevented. Choosing B rather than A costs an additional $3,000 for 400 additional prevented defects, or $7.50 each.
The comparison assumes the defects and measurement periods are comparable. Quality, budgets and uncertainty can affect the decision. The CDC glossary distinguishes cost-benefit and cost-effectiveness methods.
What a calculation can miss
An automation appraisal may need installation, energy, training, downtime, quality, worker transitions and residual value, rather than only purchase prices and salaries. A firm’s wage saving is not automatically an equal net benefit to society.
Sensitivity analysis shows how results change when assumptions change. Scenarios can examine different demand, cost or performance conditions. Results should identify their baseline, perspective, period and material uncertainties so readers can understand what supports the conclusion.
Last checked and updated on November 10, 2026 by the MBN editorial team.