
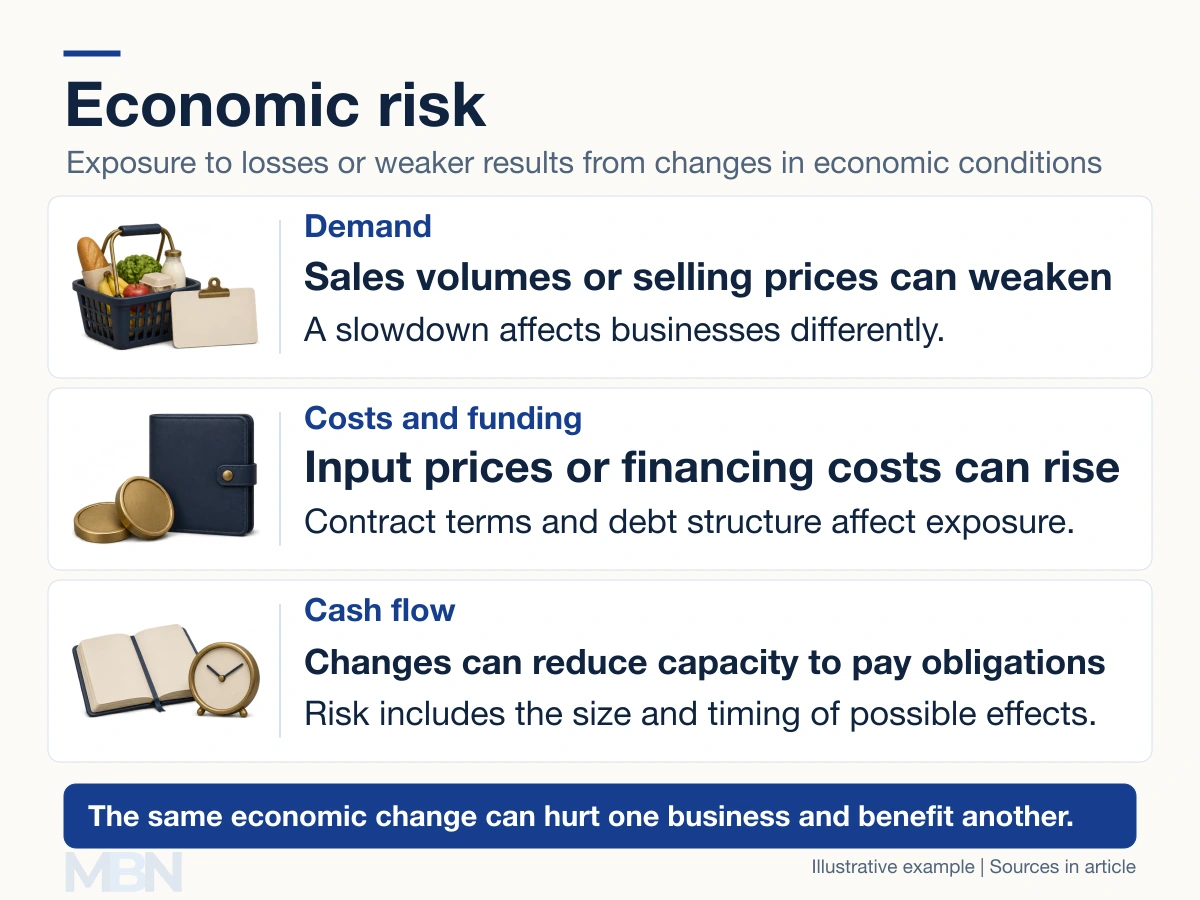
Economic risk is exposure to losses or weaker results caused by changes in economic conditions. For a business or investment, those changes can affect demand, selling prices, input costs, funding, exchange rates and the timing of cash flows.
The term applies to domestic and international activity. It describes more than the chance that something happens: the size of the exposure, possible impact and ability to meet obligations also matter.
How economic conditions reach a business
A slowdown can reduce customer spending and sales volumes. Inflation can increase wages, materials or energy costs. Whether a business can raise prices, and how quickly, affects its margins and cash flow.
Higher interest rates can increase the cost of new borrowing or floating-rate debt. Fixed-rate contracts may delay that effect until refinancing. The BIS explains interest-rate risk in its banking framework; the precise exposure depends on the relevant assets, liabilities and terms.
Exchange-rate changes can alter the local-currency cost of imports or the value of overseas receipts. A currency depreciation may hurt an importer while helping some exporters, although imported inputs and foreign-currency debt can complicate the result.
The IMF’s World Economic Outlook assesses growth, inflation and risks. Economy-wide forecasts provide context, but do not establish the outcome for an individual company.
An example of debt-service exposure
Suppose a project expects $150,000 of annual cash flow available for debt service after operating costs, tax and required maintenance. Scheduled loan principal and interest total $120,000.
Its debt-service coverage ratio, using those definitions, is $150,000 divided by $120,000, or 1.25 times. Now suppose weaker sales and higher input costs reduce the available cash flow to $90,000, with debt service unchanged.
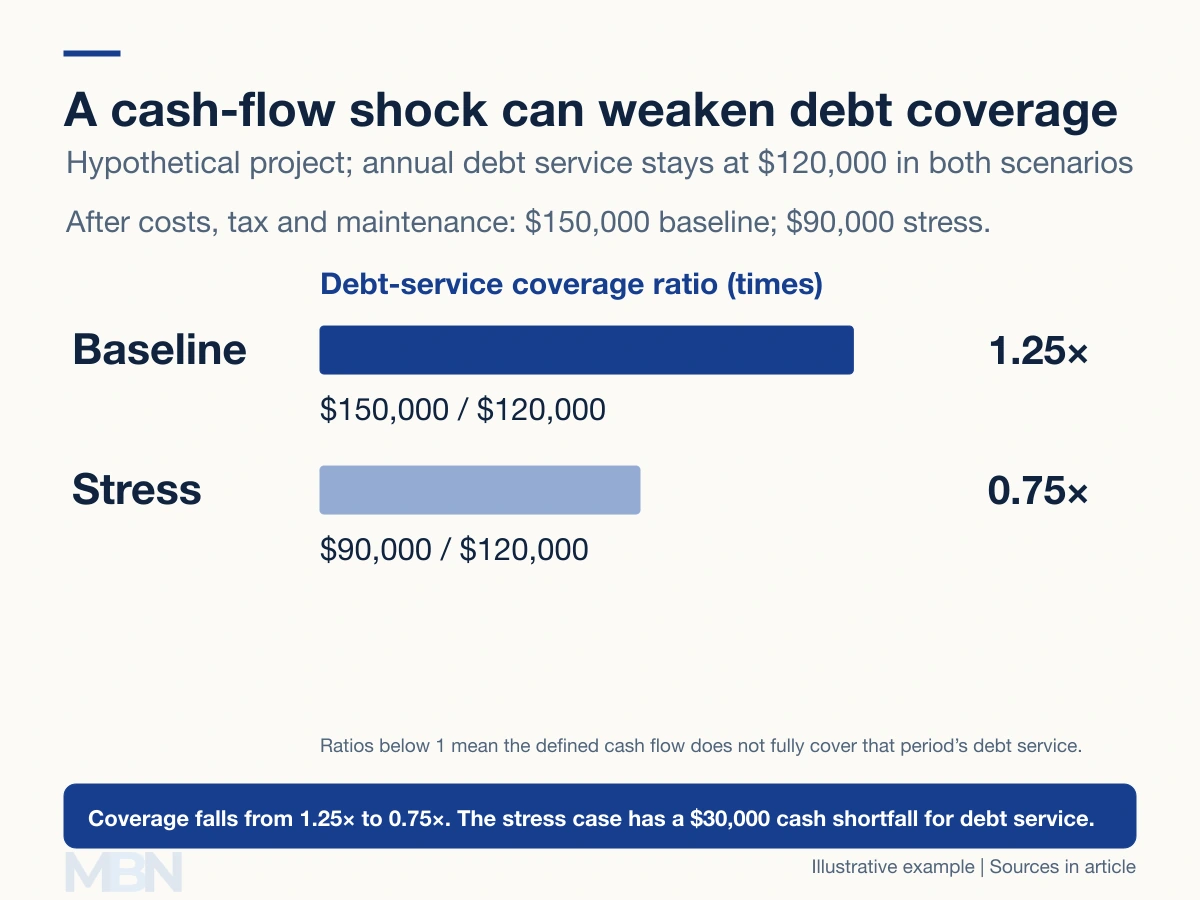
Coverage falls to 0.75 times, leaving a $30,000 shortfall against that period’s scheduled debt service. The example isolates a cash-flow effect; it does not assign a probability to the scenario or assume a particular loan covenant.
Actual financing agreements define cash flow, debt service, reserve accounts and covenant tests. An accounting profit figure should not automatically be substituted for cash available to make payments.
Political and country risks can overlap
Economic risk can interact with policy changes, sanctions, exchange controls, political instability or expropriation. These categories overlap, but a political event and an ordinary market-price movement are not identical risks.
For example, MIGA describes expropriation insurance for specified government actions. Whether compensation, insurance or legal recovery is available depends on the facts and governing terms. A party’s political label alone cannot establish that an investment will be nationalized or that recovery will fail.
Indicators and scenarios have limits
Analysts use data, forecasts, sensitivity analysis and scenarios to explore exposure. A sensitivity calculation changes an input, while a scenario combines assumptions about several conditions. Neither is automatically a prediction.
The Economic Policy Uncertainty methodology explains a news-based uncertainty index. An index value is not itself the probability of a recession, default or loss. A provider’s banking-sector trend assessment also should not be treated as a universal probability applying to every company.
How risk management changes exposure
Diversification, contractual price adjustments, cash reserves, insurance and hedging can change particular exposures. Their effectiveness depends on coverage, cost, timing, counterparties and the risks that remain.
A currency hedge may address a specified exchange-rate exposure while leaving sales-volume or customer-default risk. No single instrument removes all economic risk, and the same business can face several interacting channels at once.
Last checked and updated on November 11, 2026 by the MBN editorial team.