
Financial analysis examines financial information to understand a business, project or investment. It assesses performance, the ability to meet payments and the risks behind the figures.
Managers may use it to compare expansion plans. Lenders examine repayment capacity, while investors assess returns and risk. Financial statement analysis is an important part of this work; broader financial analysis can also include forecasts, valuations and project scenarios.
The information analysts use
The SEC’s financial-statement guide distinguishes the balance sheet, which records financial position at a date, from statements covering activity over a period. Analysts read the income statement, cash flow statement, statement of changes in equity and explanatory notes together.
They also consider debt terms, budgets, customer payment patterns and industry conditions. A ratio calculated correctly from incomplete information can still give a misleading impression.
Profitability, liquidity, solvency and stability
Profitability concerns earnings relative to sales, costs or the capital employed. For example, operating profit divided by revenue gives an operating profit margin. The numerator must be identified: gross, operating and net profit margins measure different things.
Liquidity concerns cash available to meet near-term payments. A business can report profit while waiting for customers to pay. A positive cash flow in every individual period is not a universal requirement, but payment obligations still need funding.
Solvency concerns the capacity to meet obligations over time. Assets divided by liabilities is not a universal pass-or-fail test. Recorded asset values, future cash generation, debt maturities and contingent obligations all matter.
Legal tests depend on jurisdiction. For example, section 123 of Britain’s Insolvency Act 1986 includes inability to pay debts as they fall due and an assets-versus-liabilities test that takes contingent and prospective liabilities into account. A simple accounting ratio does not settle either question.
Stability describes resilience to changing conditions. Analysts might examine dependence on one customer, variable interest payments or exposure to a fall in sales. It is an assessment, rather than one standard accounting measure.
A business can make profit and use cash
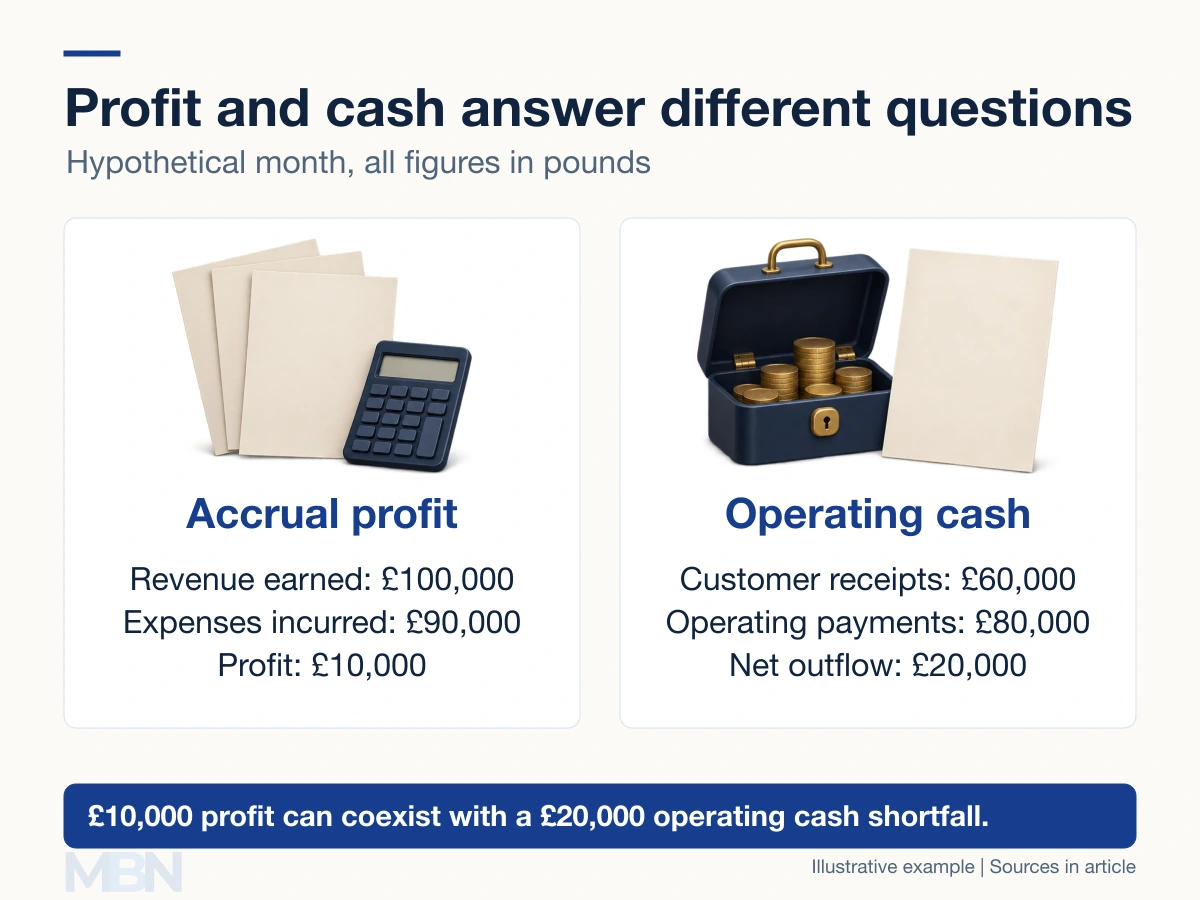
Suppose a hypothetical business earns £100,000 revenue in a month and incurs £90,000 expenses, producing £10,000 profit. It collects £60,000 from customers and makes £80,000 operating payments, so its operating cash movement is negative £20,000.
The amounts differ because earning revenue and receiving payment need not happen together. Expense recognition and cash payments can also occur at different times. Opening cash, borrowing or other funding could cover the shortfall; profit alone does not show whether the bills can be paid.
Ratios need comparisons
ACCA groups common ratios into profitability, liquidity, efficiency and gearing, meaning the use of debt relative to capital. A current ratio of £120,000 current assets divided by £80,000 current liabilities is 1.5. That does not guarantee access to £120,000 cash today: some assets may be slow-moving inventory or overdue receivables.
Compare consistent definitions across periods and suitable businesses. Seasonality, accounting policies, acquisitions and one-off events can affect comparisons. ACCA’s performance-appraisal guidance explains why a ratio needs interpretation in its business setting.
How analysis informs a decision
For a proposed machine purchase, an analyst might compare upfront cost, expected operating savings, maintenance, financing and alternative uses of the money. Testing lower sales or higher costs shows how sensitive the proposal is to assumptions.
The analysis provides evidence for a decision. It cannot remove uncertainty or guarantee a return.
Last checked and updated on November 5, 2026 by the MBN editorial team.