
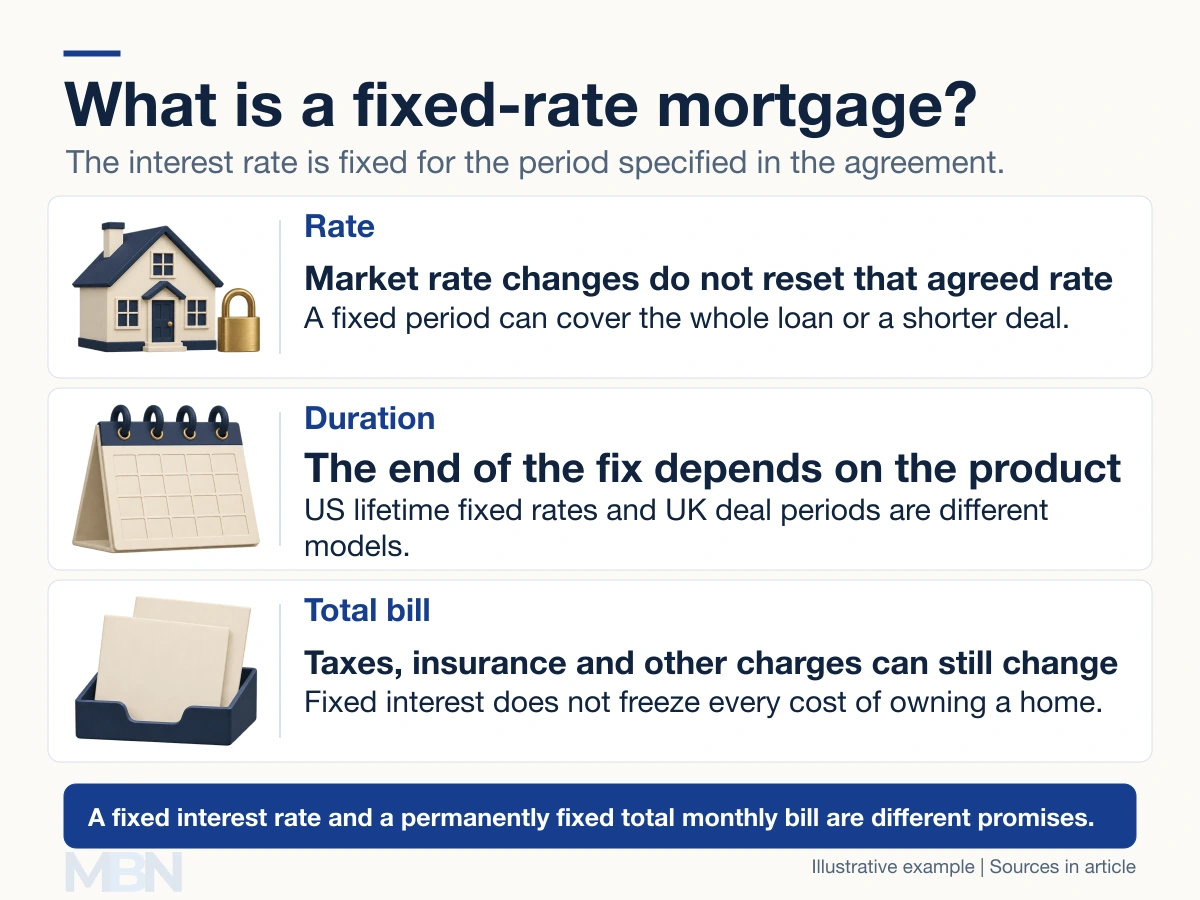
A fixed-rate mortgage has an interest rate that stays unchanged for the period specified in the agreement. That can mean the whole loan term or a shorter fixed-rate deal, depending on the country and product.
For a standard fixed-rate repayment loan, the scheduled principal-and-interest payment is stable during the relevant period. Principal is the amount borrowed. The total amount collected each month can still change because of other charges.
US and UK fixed-rate structures differ
The Consumer Financial Protection Bureau contrasts a US fixed-rate mortgage with an adjustable-rate mortgage. A conventional US 30-year fixed-rate loan keeps its interest rate for the loan’s life. It does not normally switch to a lender’s variable rate after two or five years.
In the UK, MoneyHelper explains fixed-rate deals lasting a specified number of years. A two-year or five-year deal can be part of a much longer mortgage repayment term. When the deal ends, the borrower commonly moves to the lender’s standard variable rate, or SVR, unless a new arrangement is made.
The SVR is a rate set by the lender, not necessarily a fixed margin above the central bank’s rate. The deal’s fixed period and the time needed to repay the mortgage should not be confused.
What happens when market rates move?
A rise in market interest rates does not change the rate already fixed in the agreement. A fall does not automatically reduce it either. Changing to a new deal or refinancing is a separate transaction, with its own eligibility, costs and terms.
An adjustable-rate mortgage changes according to its contract, often using an index plus a lender’s margin and subject to caps. It does not necessarily mirror every central-bank decision immediately or exactly.
Why can the monthly bill still rise?
The CFPB explains that changing property taxes and insurance can alter escrow payments. Escrow is money a mortgage servicer collects to pay those bills. Those charges are separate from the interest rate.
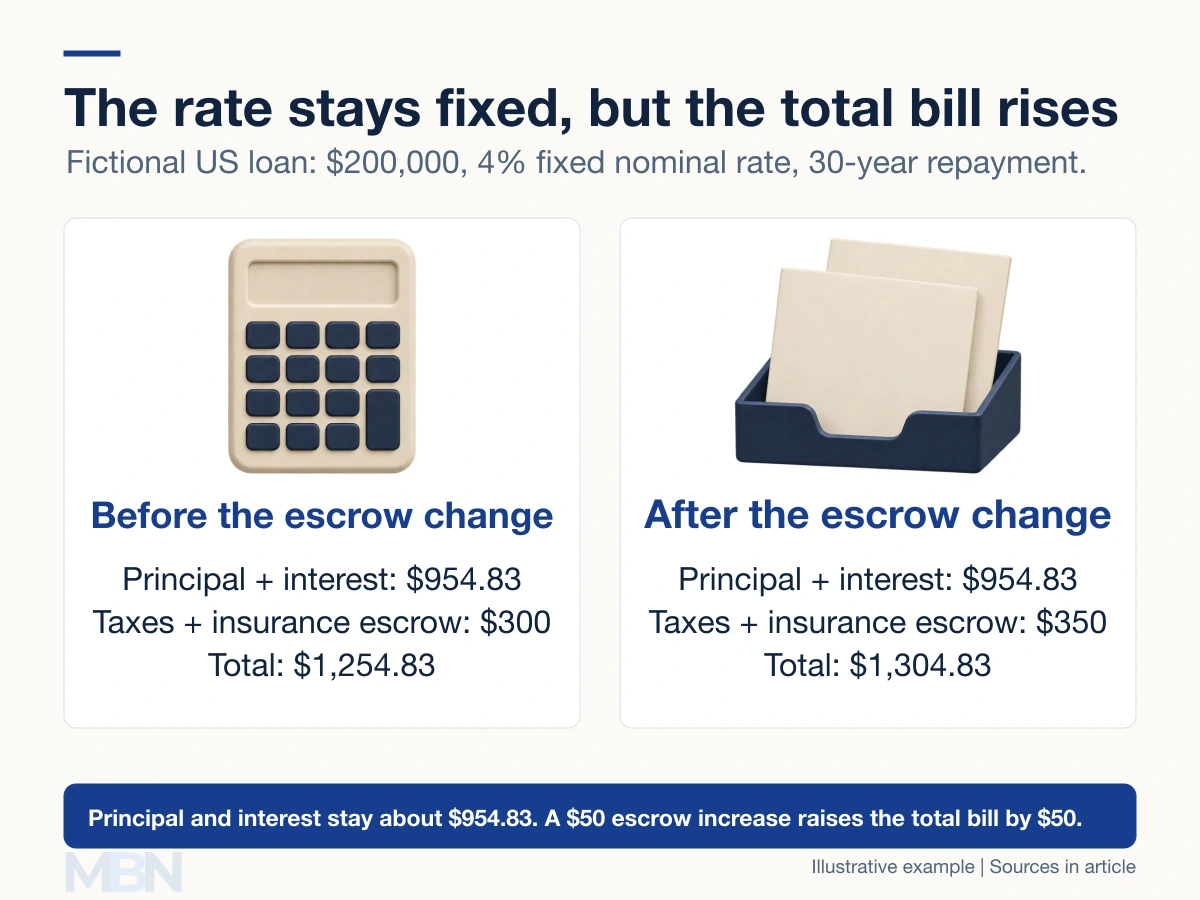
For this fictional $200,000 mortgage, 4% nominal annual interest with monthly amortization over 30 years gives a principal-and-interest payment of about $954.83. Adding $300 in monthly escrow produces a $1,254.83 bill. If escrow increases to $350, the bill becomes $1,304.83, even though the mortgage rate is still 4%.
Does fixed mean cheaper or penalty-free?
No product label guarantees either. Rates, arrangement costs and other fees differ between offers. A fixed-rate loan need not be more expensive than every variable-rate alternative, and the lowest headline rate need not produce the lowest total cost.
Early-repayment conditions also vary. The CFPB says some mortgages include prepayment penalties. MoneyHelper likewise explains that leaving a UK fixed-rate deal early can involve a charge. A fixed rate provides interest-rate certainty for its stated period, rather than a guarantee about every future housing cost.
Last checked and updated on November 4, 2026 by the MBN editorial team.