
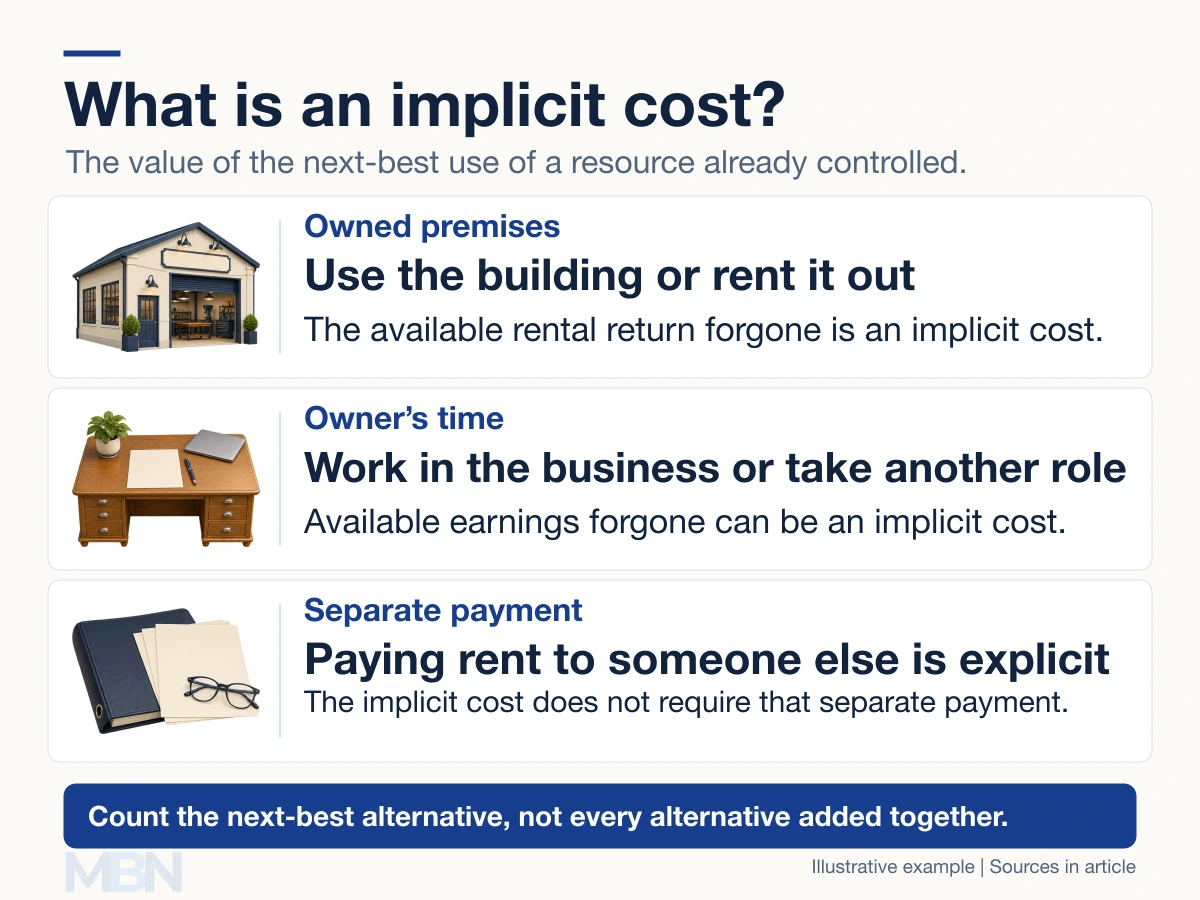
An implicit cost is the value of the next-best alternative use of a resource that a person or business already controls. It does not require a separate payment. Forgone rent on an owned building is one example.
OpenStax distinguishes implicit and explicit costs. An explicit cost involves a payment, such as wages paid to an employee or rent paid to a landlord.
The alternative use matters
If a business occupies its own building, the relevant alternative might be renting it to another business. The rent realistically available, allowing for relevant costs, is forgone when the owner uses the space.
Opportunity cost means the next-best alternative forgone. It is not the difference between the chosen option and that alternative, or the sum of every rejected option.
A sunk cost is different: it has already been incurred and cannot be recovered. An implicit cost concerns an alternative use being given up, rather than simply an expense missing from the accounts.
Forgone earnings
Suppose a fictional dentist could earn $180,000 over a year in an available job but chooses to spend that year away from paid work. The gross earnings forgone are $180,000.
Taxes, work expenses, benefits and the value of the chosen use of time need separate treatment in a fuller comparison. Forgone earnings do not mean that taking time away is necessarily the wrong choice.
Accounting and economic profit
An introductory economic model calculates accounting profit as revenue less explicit costs. Economic profit also deducts implicit opportunity costs.
Suppose annual revenue is $120,000, explicit costs are $90,000 and the relevant implicit cost is $40,000. In this simplified example, accounting profit is $30,000 and economic profit is negative $10,000.
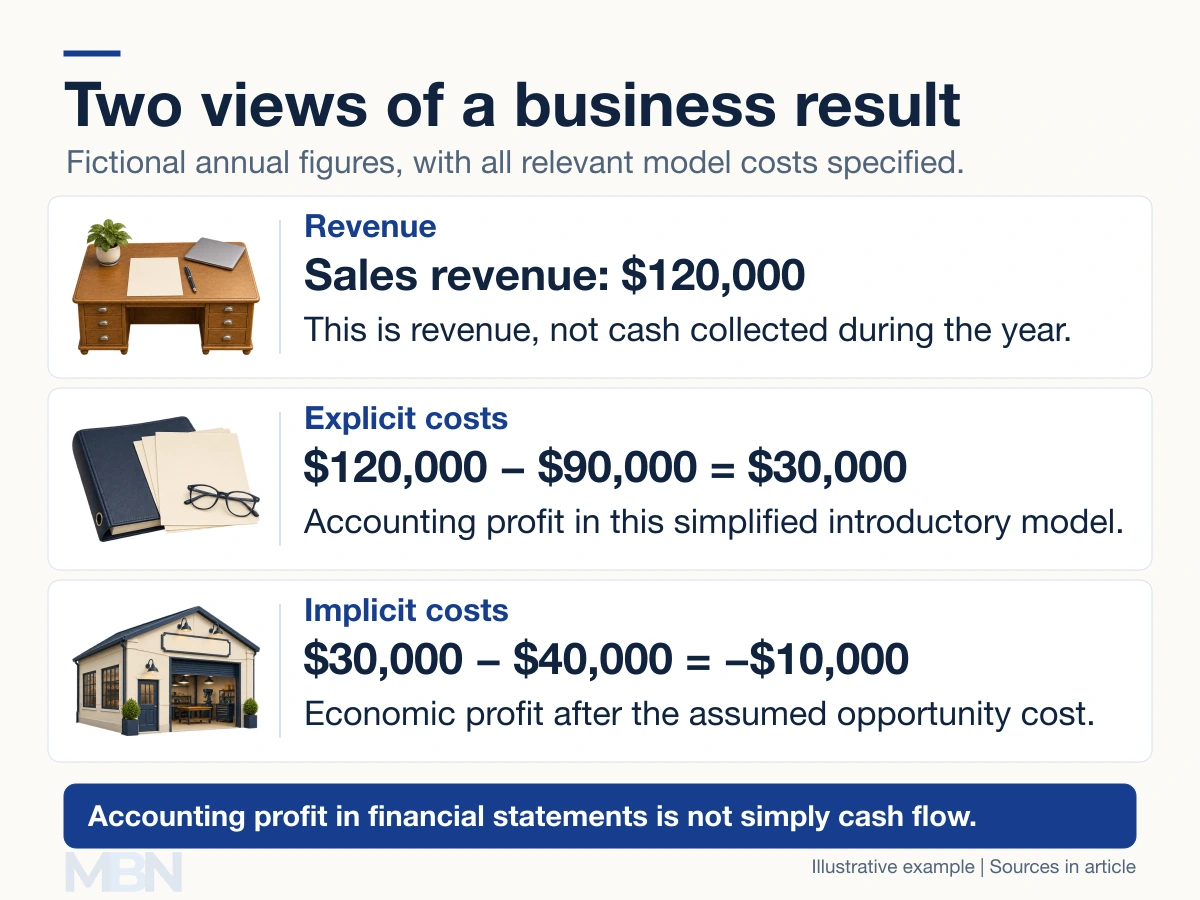
Actual financial statements apply accounting rules, including accruals and non-cash expenses. Profit is therefore not simply cash received minus cash paid. IAS 7 describes adjusting profit for non-cash items and timing differences when presenting operating cash flow using the indirect method.
Last checked and updated on November 2, 2026 by the MBN editorial team.